Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Digital Banking Platforms Market Size, CAGR & Forecast 2026-2031
Digital Banking Platforms Market
Financial Services and Investment Intelligence / MARKET REPORT
Digital Banking Platforms Market | Insight Market Data
Digital Banking Platforms Market by Deployment (Cloud, On-Premises), by Banking Type (Retail Banking, Corporate/SME Banking, Investment Banking), by Component (Platforms, Services), by Service Model (SaaS Subscription, Licensed, Banking-as-a-Service), by Access Mode (Mobile Banking, Online/Web Banking), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia-Pacific (China, Japan, India), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, Saudi Arabia, UAE) Forecast 2026-2034
The Golfer Insurance Report market is projected to reach USD 45.12 million by 2032, growing at a 5.34% CAGR. Explore coverage types, regional insights, and key players.
The global credit derivative market is set to grow from $9.16B in 2026 to $14.51B by 2035, at a 5.25% CAGR, driven by risk management demand.
Nov 2026|219 pages
$2900.00
India mutual fund industry valued at USD 3.00 Bn in 2026, projected to reach USD 6.23 Bn by 2034, growing at 9.24% CAGR, driven by SIP inflows and retail participation.
Nov 2026|223 pages
$2900.00
Islamic finance market to reach USD 8.46 Trillion by 2031 at 10.7% CAGR from USD 5.10 Trillion in 2026. Explore Shariah-compliant banking, sukuk & takaful trends.
Nov 2026|270 pages
$2900.00
Angel Investment Market valued at $62.84 Billion in 2025, projected to reach $217.91 Billion by 2035, growing at a CAGR of 13.24%.
Executive Overview: The Platform Imperative in Global Banking
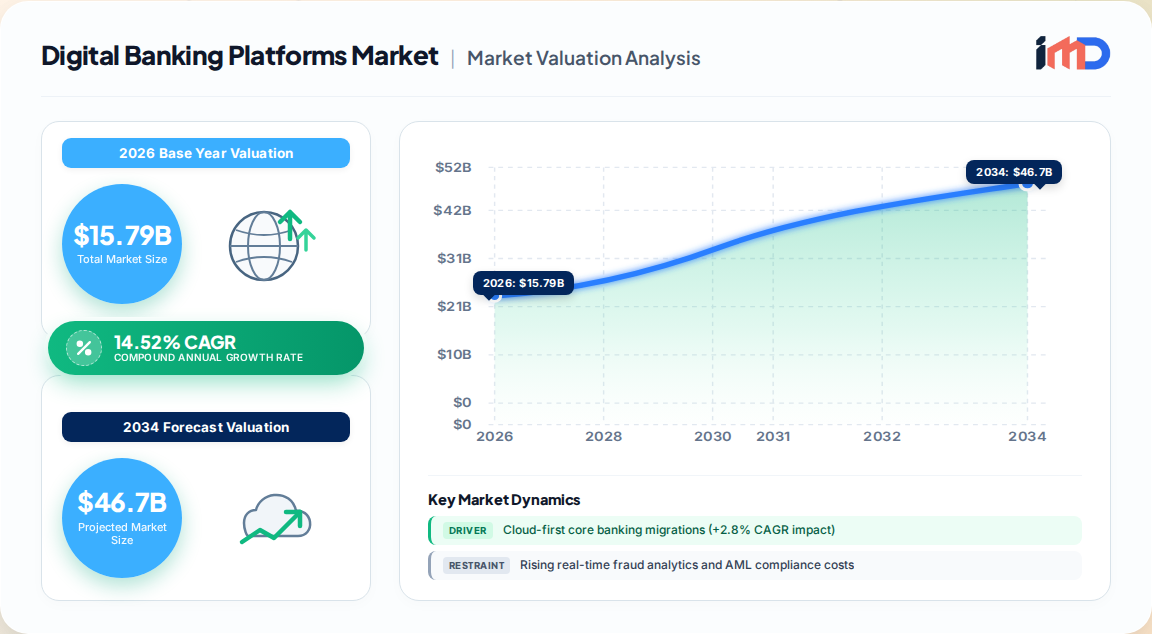
The global digital banking platforms market is undergoing a structural re-platforming cycle that is redefining how financial institutions architect, deliver, and monetize customer experiences. Our proprietary primary research estimates the market at USD 15.79 billion in 2026, expanding at a 14.52% CAGR to reach USD 31.08 billion by 2031. This growth is not merely a continuation of channel digitization; it reflects a decisive shift from monolithic legacy cores to cloud-native, composable, and API-first banking platforms.
Digital Banking Platforms Market Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
13.79 B
2025
15.79 B
2026
18.08 B
2027
20.71 B
2028
23.71 B
2029
27.16 B
2030
31.10 B
2031
Three forces converge to accelerate refresh cycles. First, cloud-first core migrations are moving from pilot to production at Tier-1 institutions, compressing product launch cycles by up to 50%. Second, open-banking and API-standard mandates across Europe, North America, and Asia-Pacific are forcing platform readiness as a compliance non-negotiable. Third, generative-AI-driven hyper-personalization is moving from experimentation to embedded servicing layers, delivering productivity gains of approximately 20% in software delivery and contact-center throughput.
Regionally, North America remains the largest market, accounting for an estimated 36% of global revenue in 2026, while Asia-Pacific is the fastest-growing region, posting a CAGR above 16% through 2031. Competitive intensity is moderate but rising, as incumbent core vendors defend installed bases against cloud-native challengers that compete on speed, API breadth, and AI differentiation.
Market Drivers: What Is Accelerating Platform Adoption
Our demand-side interviews with banking technology executives reveal that platform investment is increasingly framed as a strategic lever rather than a discrete IT purchase. The following drivers carry the highest impact on forecast CAGR:
Cloud-first core banking migrations (+2.8% CAGR impact): Tier-1 banks are fast-tracking multi-cloud deployments to lower fixed infrastructure costs and compress time-to-market. Institutions report 50% shorter product launch cycles after migration, reinforcing cloud as a strategic enabler rather than a cost play.
Smartphone-centric lifestyle banking (+2.1% CAGR impact): Mobile-first adoption is short-circuiting branch expansion economics across Asia-Pacific and Latin America. Digital wallets underpin more than 70% of regional e-commerce spend, compelling banks to recast front ends as lifestyle super-apps.
Open-banking and API-standard regulations (+1.9% CAGR impact): Successive PSD2 extensions and new data-access rules compel banks to adopt API-first architectures. Approximately 84% of banks now field requests for embedded services inside non-bank apps, signaling an ecosystem model where platform readiness trumps product exclusivity.
Generative-AI-driven hyper-personalization (+1.6% CAGR impact): Banks are weaving generative AI into servicing layers to deliver conversational support, predictive budgeting nudges, and contextual product offers, with early deployments yielding measurable productivity gains.
Green-IT mandates for energy-efficient SaaS (+1.2% CAGR impact): Sustainability requirements in Europe and North America are increasingly factored into procurement scorecards for cloud-based platforms.
Restraints and Challenges: The Friction Points Tempering Velocity
Despite robust demand, platform adoption faces material friction that moderates near-term velocity. Our analysis identifies four principal restraints:
Rising real-time fraud analytics and AML compliance costs (−1.4% CAGR impact): Global AML spending has reached USD 213.9 billion annually, yet illicit flows persist at scale. Banks must balance innovation velocity with operational resilience, diverting near-term technology budgets toward fraud mitigation and security hardening.
Vendor lock-in risk with hyperscaler clouds (−1.1% CAGR impact): Multi-national banks are increasingly wary of concentration risk in cloud infrastructure, extending procurement cycles and favoring vendors with multi-cloud portability.
Cloud-native talent scarcity (−0.8% CAGR impact): Shortages are most acute in Asia-Pacific, Latin America, and Africa, where demand for microservices and API engineering skills outpaces supply, extending integration timelines.
Interoperability gaps with legacy stacks (−0.7% CAGR impact): Deep operational dependencies on legacy cores extend integration timelines and increase implementation risk, particularly for mid-tier institutions with limited transformation budgets.
Segmentation Analysis: Where Growth Is Concentrating
The market is segmented by deployment, banking type, component, service model, and access mode. The following table summarizes revenue shares and growth trajectories based on our 2026 base-year estimates.
Highest projected growth; integration and managed services
Service Model
SaaS subscription
48.05% share (2025)
Recurring revenue model dominates new deployments
Service Model
Banking-as-a-Service
16.68% CAGR
Fastest-growing model despite tightening oversight
Access Mode
Online/web banking
56.12% share (2025)
Retains installed-base relevance
Access Mode
Mobile banking
17.02% CAGR
Consumers prefer location-agnostic interactions
The retail banking segment's dominance reflects its evolution beyond transactional interfaces into holistic lifestyle ecosystems. Meanwhile, corporate/SME banking is the fastest-growing banking type, driven by demand for predictive cash-flow forecasting, automated treasury management, and digital lending platforms that reduce error rates by approximately 15% through front-to-back office automation.
Regional Outlook: North America Leads, Asia-Pacific Accelerates
Regional dynamics reveal a market where maturity and momentum are diverging. North America accounted for 37.35% of global market size in 2025, supported by early cloud adoption, a mature BaaS ecosystem, and strong embedded-finance models. Asia-Pacific records the strongest CAGR at 16.34% to 2031, propelled by smartphone penetration, government financial-inclusion programs, and digital wallet adoption. In this region, KYC automation has reduced onboarding times by over 60% in some markets.
Digital Banking Platforms Market Regional Market Share
Loading chart...
Europe remains a regulatory pioneer, with open-banking API compliance and DORA-aligned operational-resilience requirements shaping platform procurement. Latin America and the Middle East & Africa are emerging growth frontiers: digital-only neo-bank expansion in Latin America and demand for Shariah-compliant digital banking in the Middle East are creating specialized platform requirements.
Region
2026 Market Share (Est.)
Growth Outlook
Primary Demand Driver
North America
36%
Moderate, steady
BaaS, embedded finance, cloud migration
Europe
26%
Moderate, regulation-led
Open-banking API compliance, DORA
Asia-Pacific
27%
Fastest (>16% CAGR)
Mobile-first adoption, financial inclusion
South America
6%
High growth
Neo-bank expansion, digital wallets
Middle East & Africa
5%
Emerging
Shariah-compliant platforms, inclusion programs
Competitive Landscape and Strategic Developments
The competitive landscape is moderately concentrated, with incumbent core vendors defending installed bases while cloud-native challengers capitalize on speed, API breadth, and AI differentiation. The top five players collectively hold an estimated 35.1% market share in 2025, indicating a fragmented but consolidating vendor ecosystem.
Key strategic developments observed in our primary research include:
2025: JPMorgan Chase completed a multi-cloud roll-out, while Santander's ten-market overhaul underlined the commitment required to sunset legacy cores.
2025: Banco Itaú announced a target to complete a 100% cloud migration by 2028, signaling that measurable efficiency gains outweigh transition risk.
2024: Nubank demonstrated scale advantage, growing its customer base from 33.3 million in 2020 to 93.9 million in 2023 while sustaining a 27% pre-tax ROE.
2025: Commerce Bank integrated FedNow via the Temenos stack, illustrating regulation acting as a catalyst for real-time payment upgrades.
2025: Temenos partnered with NVIDIA to package on-premises generative AI inside compliant banking frameworks, exemplifying how vendors are embedding advanced models within regulated environments.
Vendors with pre-certified, standards-compliant offerings and multi-jurisdiction implementation support are best positioned to capture share as compliance expenditure for open-banking API infrastructure becomes structurally non-cyclical.
Strategic White-Space Analysis
Our analysis identifies three high-potential white spaces where demand exceeds current platform supply:
Corporate/SME cash-flow intelligence: The corporate banking segment is growing at 16.19% CAGR, yet few platforms offer integrated predictive cash-flow forecasting with automated short-term financing recommendations. This represents a significant opportunity for vendors to differentiate beyond retail-focused offerings.
Shariah-compliant digital banking: Demand in the Middle East is rising for platforms that embed Shariah-compliant mobile banking features, a niche that remains underserved by global vendors.
RegTech-integrated platforms: Successful implementation of RegTech solutions reduces compliance-related overhead by an average of 18%, creating a compelling value proposition for platforms that bundle regulatory reporting, AML analytics, and real-time fraud detection into the core offering.
Import/Export & Supplier Dynamics
As a software-centric market, digital banking platforms do not follow traditional goods trade flows; however, supplier dynamics are shaped by cloud infrastructure concentration and talent availability. North American and European hyperscalers dominate infrastructure supply, creating dependency risks that banks are actively managing through multi-cloud strategies. Meanwhile, cloud-native talent scarcity in Asia-Pacific, Latin America, and Africa is driving vendors to establish regional engineering hubs and partner-led delivery models to maintain implementation velocity.
Digital Banking Platforms Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Digital Banking Platforms Market REPORT HIGHLIGHTS
3.5.3. Balancing innovation velocity with operational resilience
3.5.4. Regulatory fragmentation across multiple jurisdictions
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Deployment
5.1.1. Cloud
5.1.2. On-Premises
5.2. Market Analysis, Insights and Forecast - by Banking Type
5.2.1. Retail Banking
5.2.2. Corporate/SME Banking
5.2.3. Investment Banking
5.3. Market Analysis, Insights and Forecast - by Component
5.3.1. Platforms
5.3.2. Services
5.4. Market Analysis, Insights and Forecast - by Service Model
5.4.1. SaaS Subscription
5.4.2. Licensed
5.4.3. Banking-as-a-Service
5.5. Market Analysis, Insights and Forecast - by Access Mode
5.5.1. Mobile Banking
5.5.2. Online/Web Banking
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Deployment
6.1.1. Cloud
6.1.2. On-Premises
6.2. Market Analysis, Insights and Forecast - by Banking Type
6.2.1. Retail Banking
6.2.2. Corporate/SME Banking
6.2.3. Investment Banking
6.3. Market Analysis, Insights and Forecast - by Component
6.3.1. Platforms
6.3.2. Services
6.4. Market Analysis, Insights and Forecast - by Service Model
6.4.1. SaaS Subscription
6.4.2. Licensed
6.4.3. Banking-as-a-Service
6.5. Market Analysis, Insights and Forecast - by Access Mode
6.5.1. Mobile Banking
6.5.2. Online/Web Banking
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Deployment
7.1.1. Cloud
7.1.2. On-Premises
7.2. Market Analysis, Insights and Forecast - by Banking Type
7.2.1. Retail Banking
7.2.2. Corporate/SME Banking
7.2.3. Investment Banking
7.3. Market Analysis, Insights and Forecast - by Component
7.3.1. Platforms
7.3.2. Services
7.4. Market Analysis, Insights and Forecast - by Service Model
7.4.1. SaaS Subscription
7.4.2. Licensed
7.4.3. Banking-as-a-Service
7.5. Market Analysis, Insights and Forecast - by Access Mode
7.5.1. Mobile Banking
7.5.2. Online/Web Banking
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Deployment
8.1.1. Cloud
8.1.2. On-Premises
8.2. Market Analysis, Insights and Forecast - by Banking Type
8.2.1. Retail Banking
8.2.2. Corporate/SME Banking
8.2.3. Investment Banking
8.3. Market Analysis, Insights and Forecast - by Component
8.3.1. Platforms
8.3.2. Services
8.4. Market Analysis, Insights and Forecast - by Service Model
8.4.1. SaaS Subscription
8.4.2. Licensed
8.4.3. Banking-as-a-Service
8.5. Market Analysis, Insights and Forecast - by Access Mode
8.5.1. Mobile Banking
8.5.2. Online/Web Banking
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Deployment
9.1.1. Cloud
9.1.2. On-Premises
9.2. Market Analysis, Insights and Forecast - by Banking Type
9.2.1. Retail Banking
9.2.2. Corporate/SME Banking
9.2.3. Investment Banking
9.3. Market Analysis, Insights and Forecast - by Component
9.3.1. Platforms
9.3.2. Services
9.4. Market Analysis, Insights and Forecast - by Service Model
9.4.1. SaaS Subscription
9.4.2. Licensed
9.4.3. Banking-as-a-Service
9.5. Market Analysis, Insights and Forecast - by Access Mode
9.5.1. Mobile Banking
9.5.2. Online/Web Banking
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Deployment
10.1.1. Cloud
10.1.2. On-Premises
10.2. Market Analysis, Insights and Forecast - by Banking Type
10.2.1. Retail Banking
10.2.2. Corporate/SME Banking
10.2.3. Investment Banking
10.3. Market Analysis, Insights and Forecast - by Component
10.3.1. Platforms
10.3.2. Services
10.4. Market Analysis, Insights and Forecast - by Service Model
10.4.1. SaaS Subscription
10.4.2. Licensed
10.4.3. Banking-as-a-Service
10.5. Market Analysis, Insights and Forecast - by Access Mode
10.5.1. Mobile Banking
10.5.2. Online/Web Banking
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Backbase B.V.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Temenos Headquarters SA
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Finastra Group Holdings Limited
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Infosys Ltd. (Finacle)
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Oracle Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. FIS Global
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Fiserv Inc.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. SAP SE
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Tata Consultancy Services (TCS)
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. EdgeVerve Systems Limited
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Intellect Design Arena
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Appway
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Kony Inc.
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Q2 Software Inc.
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Jack Henry & Associates
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Digital Banking Platforms Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Digital Banking Platforms Market Revenue (Billion), by Deployment 2026 & 2034
Figure 3: North America Digital Banking Platforms Market Revenue Share (%), by Deployment 2026 & 2034
Figure 4: North America Digital Banking Platforms Market Revenue (Billion), by Banking Type 2026 & 2034
Figure 5: North America Digital Banking Platforms Market Revenue Share (%), by Banking Type 2026 & 2034
Figure 6: North America Digital Banking Platforms Market Revenue (Billion), by Component 2026 & 2034
Figure 7: North America Digital Banking Platforms Market Revenue Share (%), by Component 2026 & 2034
Figure 8: North America Digital Banking Platforms Market Revenue (Billion), by Service Model 2026 & 2034
Figure 9: North America Digital Banking Platforms Market Revenue Share (%), by Service Model 2026 & 2034
Figure 10: North America Digital Banking Platforms Market Revenue (Billion), by Access Mode 2026 & 2034
Figure 11: North America Digital Banking Platforms Market Revenue Share (%), by Access Mode 2026 & 2034
Figure 12: North America Digital Banking Platforms Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Digital Banking Platforms Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Digital Banking Platforms Market Revenue (Billion), by Deployment 2026 & 2034
Figure 15: Europe Digital Banking Platforms Market Revenue Share (%), by Deployment 2026 & 2034
Figure 16: Europe Digital Banking Platforms Market Revenue (Billion), by Banking Type 2026 & 2034
Figure 17: Europe Digital Banking Platforms Market Revenue Share (%), by Banking Type 2026 & 2034
Figure 18: Europe Digital Banking Platforms Market Revenue (Billion), by Component 2026 & 2034
Figure 19: Europe Digital Banking Platforms Market Revenue Share (%), by Component 2026 & 2034
Figure 20: Europe Digital Banking Platforms Market Revenue (Billion), by Service Model 2026 & 2034
Figure 21: Europe Digital Banking Platforms Market Revenue Share (%), by Service Model 2026 & 2034
Figure 22: Europe Digital Banking Platforms Market Revenue (Billion), by Access Mode 2026 & 2034
Figure 23: Europe Digital Banking Platforms Market Revenue Share (%), by Access Mode 2026 & 2034
Figure 24: Europe Digital Banking Platforms Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Digital Banking Platforms Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia-Pacific Digital Banking Platforms Market Revenue (Billion), by Deployment 2026 & 2034
Figure 27: Asia-Pacific Digital Banking Platforms Market Revenue Share (%), by Deployment 2026 & 2034
Figure 28: Asia-Pacific Digital Banking Platforms Market Revenue (Billion), by Banking Type 2026 & 2034
Figure 29: Asia-Pacific Digital Banking Platforms Market Revenue Share (%), by Banking Type 2026 & 2034
Figure 30: Asia-Pacific Digital Banking Platforms Market Revenue (Billion), by Component 2026 & 2034
Figure 31: Asia-Pacific Digital Banking Platforms Market Revenue Share (%), by Component 2026 & 2034
Figure 32: Asia-Pacific Digital Banking Platforms Market Revenue (Billion), by Service Model 2026 & 2034
Figure 33: Asia-Pacific Digital Banking Platforms Market Revenue Share (%), by Service Model 2026 & 2034
Figure 34: Asia-Pacific Digital Banking Platforms Market Revenue (Billion), by Access Mode 2026 & 2034
Figure 35: Asia-Pacific Digital Banking Platforms Market Revenue Share (%), by Access Mode 2026 & 2034
Figure 36: Asia-Pacific Digital Banking Platforms Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia-Pacific Digital Banking Platforms Market Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Digital Banking Platforms Market Revenue (Billion), by Deployment 2026 & 2034
Figure 39: South America Digital Banking Platforms Market Revenue Share (%), by Deployment 2026 & 2034
Figure 40: South America Digital Banking Platforms Market Revenue (Billion), by Banking Type 2026 & 2034
Figure 41: South America Digital Banking Platforms Market Revenue Share (%), by Banking Type 2026 & 2034
Figure 42: South America Digital Banking Platforms Market Revenue (Billion), by Component 2026 & 2034
Figure 43: South America Digital Banking Platforms Market Revenue Share (%), by Component 2026 & 2034
Figure 44: South America Digital Banking Platforms Market Revenue (Billion), by Service Model 2026 & 2034
Figure 45: South America Digital Banking Platforms Market Revenue Share (%), by Service Model 2026 & 2034
Figure 46: South America Digital Banking Platforms Market Revenue (Billion), by Access Mode 2026 & 2034
Figure 47: South America Digital Banking Platforms Market Revenue Share (%), by Access Mode 2026 & 2034
Figure 48: South America Digital Banking Platforms Market Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Digital Banking Platforms Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Digital Banking Platforms Market Revenue (Billion), by Deployment 2026 & 2034
Figure 51: Middle East & Africa Digital Banking Platforms Market Revenue Share (%), by Deployment 2026 & 2034
Figure 52: Middle East & Africa Digital Banking Platforms Market Revenue (Billion), by Banking Type 2026 & 2034
Figure 53: Middle East & Africa Digital Banking Platforms Market Revenue Share (%), by Banking Type 2026 & 2034
Figure 54: Middle East & Africa Digital Banking Platforms Market Revenue (Billion), by Component 2026 & 2034
Figure 55: Middle East & Africa Digital Banking Platforms Market Revenue Share (%), by Component 2026 & 2034
Figure 56: Middle East & Africa Digital Banking Platforms Market Revenue (Billion), by Service Model 2026 & 2034
Figure 57: Middle East & Africa Digital Banking Platforms Market Revenue Share (%), by Service Model 2026 & 2034
Figure 58: Middle East & Africa Digital Banking Platforms Market Revenue (Billion), by Access Mode 2026 & 2034
Figure 59: Middle East & Africa Digital Banking Platforms Market Revenue Share (%), by Access Mode 2026 & 2034
Figure 60: Middle East & Africa Digital Banking Platforms Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Digital Banking Platforms Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Digital Banking Platforms Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 2: Global Digital Banking Platforms Market Revenue Billion Forecast, by Banking Type 2020 & 2034
Table 3: Global Digital Banking Platforms Market Revenue Billion Forecast, by Component 2020 & 2034
Table 4: Global Digital Banking Platforms Market Revenue Billion Forecast, by Service Model 2020 & 2034
Table 5: Global Digital Banking Platforms Market Revenue Billion Forecast, by Access Mode 2020 & 2034
Table 6: Global Digital Banking Platforms Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Digital Banking Platforms Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 8: North America Digital Banking Platforms Market Revenue Billion Forecast, by Banking Type 2020 & 2034
Table 9: North America Digital Banking Platforms Market Revenue Billion Forecast, by Component 2020 & 2034
Table 10: North America Digital Banking Platforms Market Revenue Billion Forecast, by Service Model 2020 & 2034
Table 11: North America Digital Banking Platforms Market Revenue Billion Forecast, by Access Mode 2020 & 2034
Table 12: North America Digital Banking Platforms Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Digital Banking Platforms Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 17: Europe Digital Banking Platforms Market Revenue Billion Forecast, by Banking Type 2020 & 2034
Table 18: Europe Digital Banking Platforms Market Revenue Billion Forecast, by Component 2020 & 2034
Table 19: Europe Digital Banking Platforms Market Revenue Billion Forecast, by Service Model 2020 & 2034
Table 20: Europe Digital Banking Platforms Market Revenue Billion Forecast, by Access Mode 2020 & 2034
Table 21: Europe Digital Banking Platforms Market Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Asia-Pacific Digital Banking Platforms Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 26: Asia-Pacific Digital Banking Platforms Market Revenue Billion Forecast, by Banking Type 2020 & 2034
Table 27: Asia-Pacific Digital Banking Platforms Market Revenue Billion Forecast, by Component 2020 & 2034
Table 28: Asia-Pacific Digital Banking Platforms Market Revenue Billion Forecast, by Service Model 2020 & 2034
Table 29: Asia-Pacific Digital Banking Platforms Market Revenue Billion Forecast, by Access Mode 2020 & 2034
Table 30: Asia-Pacific Digital Banking Platforms Market Revenue Billion Forecast, by Country 2020 & 2034
Table 31: China Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Japan Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: India Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: South America Digital Banking Platforms Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 35: South America Digital Banking Platforms Market Revenue Billion Forecast, by Banking Type 2020 & 2034
Table 36: South America Digital Banking Platforms Market Revenue Billion Forecast, by Component 2020 & 2034
Table 37: South America Digital Banking Platforms Market Revenue Billion Forecast, by Service Model 2020 & 2034
Table 38: South America Digital Banking Platforms Market Revenue Billion Forecast, by Access Mode 2020 & 2034
Table 39: South America Digital Banking Platforms Market Revenue Billion Forecast, by Country 2020 & 2034
Table 40: Brazil Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Argentina Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Middle East & Africa Digital Banking Platforms Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 43: Middle East & Africa Digital Banking Platforms Market Revenue Billion Forecast, by Banking Type 2020 & 2034
Table 44: Middle East & Africa Digital Banking Platforms Market Revenue Billion Forecast, by Component 2020 & 2034
Table 45: Middle East & Africa Digital Banking Platforms Market Revenue Billion Forecast, by Service Model 2020 & 2034
Table 46: Middle East & Africa Digital Banking Platforms Market Revenue Billion Forecast, by Access Mode 2020 & 2034
Table 47: Middle East & Africa Digital Banking Platforms Market Revenue Billion Forecast, by Country 2020 & 2034
Table 48: South Africa Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 49: Saudi Arabia Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: UAE Digital Banking Platforms Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the digital banking platforms market size in 2026?
The global digital banking platforms market is estimated at USD 15.79 billion in 2026 and is projected to reach USD 31.08 billion by 2031, expanding at a 14.52% CAGR during the forecast period.
2Which region is the fastest-growing market for digital banking platforms?
Asia-Pacific is the fastest-growing region, recording a CAGR above 16% through 2031, driven by smartphone penetration, government financial-inclusion programs, and digital wallet adoption. North America remains the largest market, accounting for approximately 36% of global revenue.
3What are the key drivers of the digital banking platforms market?
Cloud-first core banking migrations, smartphone-centric lifestyle banking demand, open-banking and API-standard regulations, and generative-AI-driven hyper-personalization are the primary growth drivers, each contributing between 1.6% and 2.8% to the forecast CAGR.
4Which deployment mode dominates the digital banking platforms market?
Cloud deployment captured 60.74% of the market share in 2025, driven by banks' preference for scalable subscription models, cost-effectiveness, and the ability to manage peak transaction volumes without major hardware investments.
5Who are the leading companies in the digital banking platforms market?
Major players include Backbase B.V., Temenos Headquarters SA, Finastra Group Holdings Limited, Infosys Ltd. (Finacle), Oracle Corporation, FIS Global, Fiserv, SAP SE, Tata Consultancy Services, and EdgeVerve Systems. The top five players collectively held 35.1% market share in 2025.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research effort is allocated to primary research, including structured interviews and surveys with senior decision-makers across the digital banking platform value chain.
We conduct interviews with 4–5 specific company types: core banking platform vendors, cloud infrastructure providers, system integrators and implementation partners, digital-only neo-banks, and retail/commercial banks procuring platforms.
Stakeholder job titles interviewed include Chief Technology Officer, Head of Digital Banking, Chief Compliance Officer, and Director of Core Banking Transformation.
We consult 3–4 real, globally recognized industry associations and regulatory bodies: the Basel Committee on Banking Supervision, the European Banking Authority, the Open Banking Implementation Entity (UK), and the Bank for International Settlements.
All interviews are conducted under strict anonymity protocols to ensure candor on procurement timelines, vendor performance, and budget allocations.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Technology Officer
30%
Head of Digital Banking
28%
Chief Compliance Officer
22%
Director of Core Banking Transformation
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Core Banking Platform Vendors
35%
Cloud Infrastructure Providers
20%
System Integrators & Implementation Partners
20%
Digital-Only Neo-Banks
15%
Retail & Commercial Banks (Procurement)
10%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on secondary sources, including audited financial filings, investor presentations, and regulatory disclosures.
Standard financial databases consulted include Bloomberg, Factiva, Hoovers, and PitchBook, alongside official multilateral sources such as the World Bank, OECD, and national statistical agencies.
We benchmark platform adoption against 3–4 specific quantitative metrics: cloud deployment share (60.74%), retail banking revenue share (63.12%), SaaS subscription share (48.05%), and mobile banking CAGR (17.02%).
All secondary data is triangulated against primary interview findings to ensure consistency and eliminate single-source bias.
Demand Modeling & Market Estimation
We employ top-down and bottom-up methodologies simultaneously, validating results via multi-level data triangulation.
The bottom-up model aggregates platform licensing, subscription, and services revenue across 3–4 specific quantitative metrics: per-institution deployment spend, cloud migration volumes, API transaction throughput, and vendor contract values.
The top-down model applies regional banking IT expenditure ratios to platform-specific allocations, cross-checked against regulatory filing disclosures.
Demand-side indicators include mobile money transaction values, open-banking API call volumes, and digital onboarding completion rates.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, supported by multi-source validation and expert review.
Every report is updated to the date of purchase, incorporating the latest available data and insights.
Quality assurance protocols include triangulation across at least three independent data sources, outlier detection, and reconciliation of vendor-reported revenues against regulatory filings.
Final estimates are reviewed by a senior analyst panel before publication to ensure internal consistency and methodological rigor.