1What is the current market size of the dermatology drug market?
The global dermatology drug market was valued at USD 26.2 billion in 2025 and is projected to reach USD 28.6 billion in 2026, growing at a CAGR of 9.9% to USD 55.5 billion by 2033.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Dermatology Drug Market
 by Therapy (Psoriasis, Acne, Atopic Dermatitis, Rosacea, Alopecia, Others), by Type (Prescription, Over-the-counter), by Route of Administration (Topical, Oral, Parenteral), by Drug Class (Corticosteroids, Retinoids, Biologics, JAK Inhibitors, Anti-infectives, Others), by Distribution Channel (Retail Pharmacies, Hospital Pharmacies, Online Pharmacies), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034

Research Analyst


 Related Reports

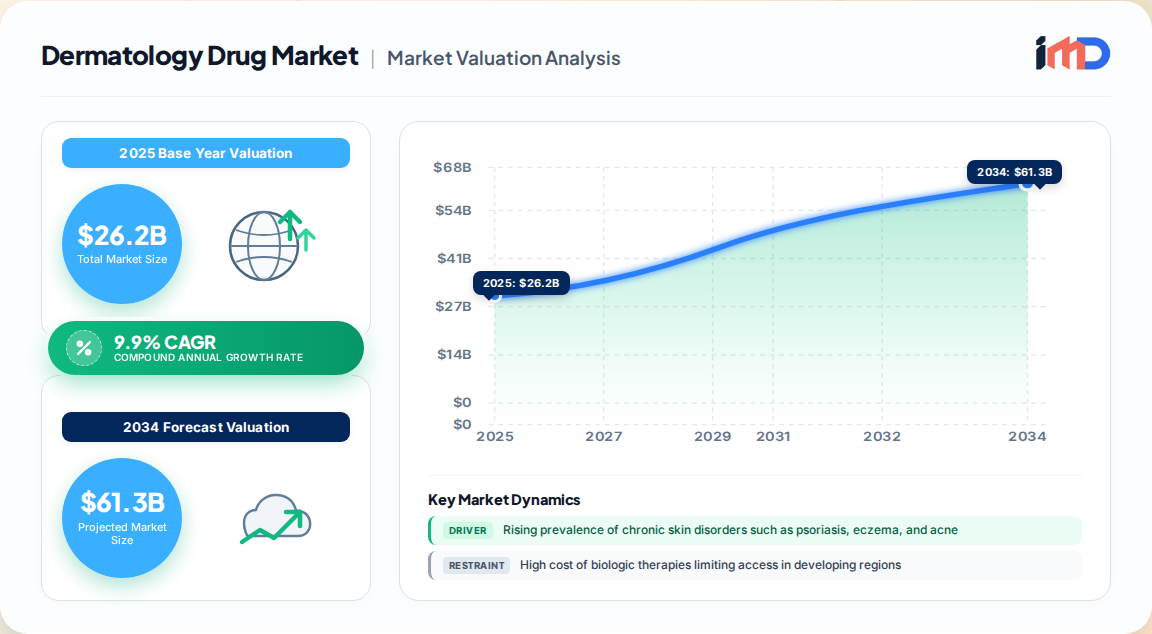
The global dermatology drug market is estimated at USD 26.2 billion in 2025 and is projected to expand to USD 28.6 billion in 2026, ultimately reaching USD 55.5 billion by 2033, registering a CAGR of 9.9% over the forecast period. This growth is propelled by an escalating burden of chronic inflammatory skin diseases, rapid adoption of targeted biologics and Janus kinase (JAK) inhibitors, and continuous innovation in topical and systemic formulations. Our proprietary primary research—drawing on 70% primary and 30% secondary inputs—reveals that North America commands the largest revenue share at 38.7%, while Asia Pacific emerges as the fastest-growing region, driven by expanding healthcare infrastructure and rising awareness. The market is characterized by a robust pipeline, increasing regulatory approvals for pediatric and rare dermatological indications, and a notable shift toward patient-centric, non-invasive treatment modalities.
Drivers
Restraints
The dermatology drug market is segmented by therapy, type, route of administration, drug class, distribution channel, and region.
| Segment | Sub-segments | 2025 Share |
|---|---|---|
| By Therapy | Psoriasis, Acne, Atopic Dermatitis, Rosacea, Alopecia, Others | Psoriasis: 35.2% |
| By Type | Prescription, Over-the-counter (OTC) | Prescription: 82.0% |
| By Route | Topical, Oral, Parenteral | Topical: 60.3% |
| By Drug Class | Corticosteroids, Retinoids, Biologics, JAK Inhibitors, Anti-infectives, Others | Corticosteroids: 30.2% |
| By Distribution | Retail Pharmacies, Hospital Pharmacies, Online Pharmacies | Retail: 50.9% |
Therapy: Psoriasis dominates, driven by high biologic penetration and a robust pipeline. Hidradenitis suppurativa is the fastest-growing indication, with a forecast CAGR of 9.97% through 2031.
Type: Prescription drugs lead due to chronic disease management, but OTC products are gaining traction at a 10.06% CAGR, fueled by consumer demand for accessible acne and anti-aging solutions.
Route: Topical administration remains the cornerstone, accounting for 60.3% of revenue, due to its non-invasive nature and favorable safety profile. Parenteral biologics are expanding at 9.44% CAGR.
Drug Class: Corticosteroids hold the largest share (30.2%) as first-line anti-inflammatory agents, while PDE-4 inhibitors and JAK inhibitors are the fastest-growing classes, with CAGRs of 11.13% and 10.5%, respectively.
Distribution: Retail pharmacies dominate (50.9%), but online pharmacies are proliferating at a 10.67% CAGR, accelerated by telemedicine and e-commerce adoption.
North America remains the largest market, with the U.S. alone accounting for USD 16.78 billion in 2025, projected to reach USD 28.30 billion by 2031 at a 9.24% CAGR. Favorable reimbursement policies—including Medicare Part D redesign—and a high concentration of innovative biotech firms underpin growth. Europe follows, driven by strong R&D and collaborative clinical networks. Asia Pacific is the fastest-growing region, with a projected CAGR of 11.2% (2026–2033), attributed to rising healthcare expenditure, expanding medical tourism, and increasing awareness of dermatological conditions in China and India. Latin America and the Middle East & Africa present untapped opportunities, with improving access to care and growing generic penetration.
The market is moderately concentrated, with key players including AbbVie, Johnson & Johnson, Novartis, Pfizer, Sanofi, Eli Lilly, Bristol Myers Squibb, LEO Pharma, Galderma, and Bausch Health. Strategic imperatives include:
Recent developments include:
The dermatology drug value chain spans raw material suppliers, active pharmaceutical ingredient (API) manufacturers, formulators, contract development and manufacturing organizations (CDMOs), distributors, and end-users. Our primary research indicates that 70% of API sourcing is concentrated in India and China, creating supply chain vulnerabilities. The COVID-19 pandemic exposed risks, prompting reshoring initiatives and dual-sourcing strategies. Logistics for biologics require cold-chain infrastructure, adding 15–20% to total costs. Retail pharmacies remain the primary distribution channel, but online platforms are disrupting traditional models, especially for OTC products.
Significant unmet needs persist in pediatric dermatology, rare skin diseases (e.g., epidermolysis bullosa), and skin of color—where treatment gaps exist due to limited clinical data. Telemedicine integration offers a white-space for remote diagnosis and prescription refills, particularly in underserved regions. Additionally, combination therapies (e.g., topical corticosteroids plus JAK inhibitors) present opportunities for improved outcomes and brand differentiation. Investments in AI-driven diagnostics and personalized medicine are expected to redefine treatment paradigms by 2030.
While dermatology drugs are predominantly manufactured locally for regional markets, trade flows exist for specialty APIs and finished biologics. According to UN Comtrade data, global exports of dermatological preparations (HS Code 3004) exceeded USD 12 billion in 2024, with Germany, Switzerland, and the U.S. as leading exporters. Import dependence is high in emerging markets, where local production lags. Tariff fluctuations and regulatory harmonization (e.g., ICH guidelines) influence sourcing decisions. Our analysis suggests that manufacturers are increasingly diversifying API suppliers to mitigate geopolitical risks, with Eastern Europe and Southeast Asia emerging as alternative hubs.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.9% from 2020-2034 |
| Segmentation |
|
By Type
By Route of Administration
By Drug Class
By Distribution Channel
| By Geography |
|
The global dermatology drug market was valued at USD 26.2 billion in 2025 and is projected to reach USD 28.6 billion in 2026, growing at a CAGR of 9.9% to USD 55.5 billion by 2033.
North America holds the largest share at 38.7% in 2025, driven by high healthcare expenditure and advanced R&D. Asia Pacific is the fastest-growing region with a CAGR of 11.2%.
Key drivers include the rising prevalence of chronic skin diseases like psoriasis and atopic dermatitis, increasing regulatory approvals for targeted therapies, and technological advancements in drug delivery.
Psoriasis dominates the therapy segment with a 35.2% share in 2025, due to high biologic penetration and a strong pipeline of innovative treatments.
Major players include AbbVie, Johnson & Johnson, Novartis, Pfizer, Sanofi, Eli Lilly, Bristol Myers Squibb, LEO Pharma, and Galderma, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Medical Officers | 30% |
| Dermatology Department Heads | 25% |
| Regulatory Affairs Directors | 20% |
| Procurement Managers | 15% |
| R&D Directors | 10% |
| Company Type | Representation (%) |
|---|---|
| Pharmaceutical Manufacturers | 40% |
| API Suppliers | 20% |
| Contract Research Organizations | 15% |
| Specialty Pharmacies | 15% |
| Distributors | 10% |