Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Cooking Oil Market by Product Type (Palm Oil, Soy Oil, Sunflower Oil, Peanut Oil, Olive Oil, Rapeseed Oil, Other Cooking Oils), by End-User (Residential, Food Services, Food Processor), by Nature (Organic, Conventional), by Category (Refined, Semi-refined, Unrefined), by Packaging (Bottles, Pouches, Cans, Jars), by Distribution Channel (Supermarket/Hypermarket, Independent Retail Stores, Business to Business, Online Sales Channel, Departmental Stores, Discount Stores, Convenience Stores, Other Sales Channels), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Russia), by Asia Pacific (China, India, Japan, Indonesia, Malaysia), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
India renewable energy market is projected to reach USD 159.81 Billion by 2035, growing at a CAGR of 7.36% from 2026 to 2035, driven by solar and wind.
The Semi-Submersible Drilling Rig Industry market was valued at USD 24.6 Billion in 2025 and is projected to reach USD 41.2 Billion by 2033, growing at a 6.7% CAGR.
Nov 2026|275 pages
$2900.00
West Africa refined petroleum products market to reach USD 78.62 billion by 2031 at 4.88% CAGR. Dangote, subsidy reform and LPG drive demand.
Nov 2026|251 pages
$2900.00
Marine solid state circuit breaker market to reach USD 1.24 Billion by 2035 at 9.2% CAGR, driven by vessel electrification and DC grid adoption.
Nov 2026|251 pages
$2900.00
Micro-Dramas Production market at $10.63B in 2025, growing 26.1% CAGR to $53.9B by 2032. Vertical-screen content, monetization and regional analysis.
Executive Overview: A Resilient, High-Volume Global Commodity Market
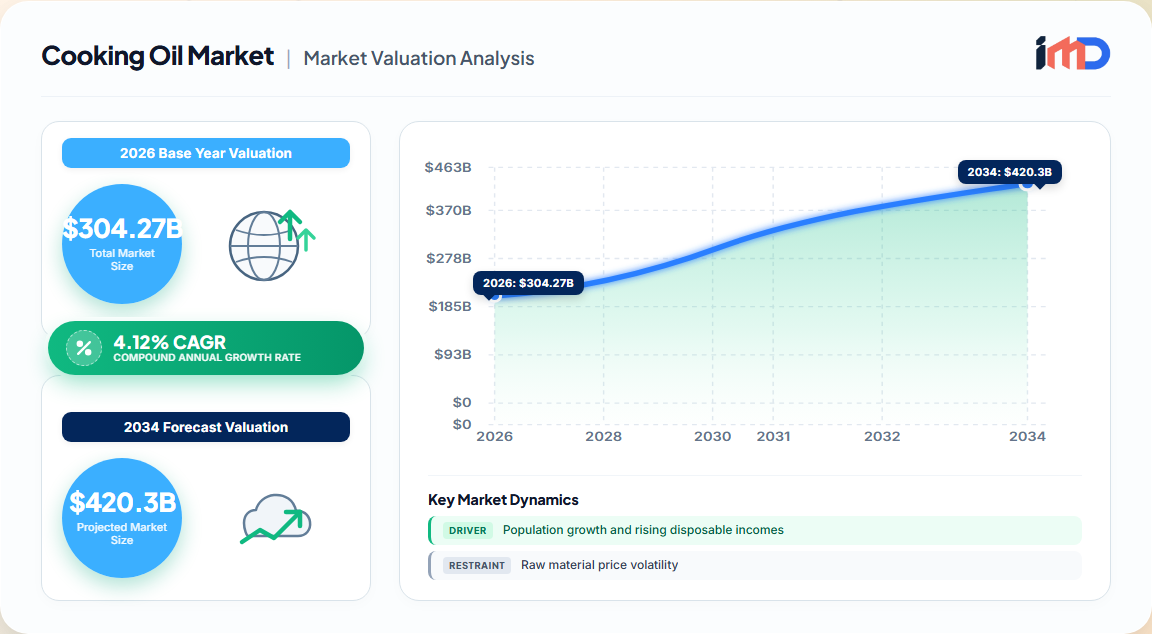
The global cooking oil market represents one of the most fundamental and consistently expanding segments of the global food and agricultural economy. Our proprietary primary research, triangulated with official multilateral trade data, estimates the market at $304.27 billion in 2026, projected to reach $420.27 billion by 2034, advancing at a CAGR of 4.12%. This growth is underpinned by immutable demographic forces—population expansion and rising disposable incomes in middle-income countries—which drive baseline demand for edible oils as a core dietary staple.
Cooking Oil Market Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
292.2 B
2025
304.3 B
2026
316.8 B
2027
329.9 B
2028
343.4 B
2029
357.6 B
2030
372.3 B
2031
The market's trajectory is not merely a function of volume growth; it is characterized by significant value migration. Consumers and food processors are increasingly shifting from commodity oils toward differentiated products that offer specific health profiles, functional benefits, or sustainability credentials. This dynamic creates a complex landscape where established commodity giants compete alongside agile specialty players, and where supply chain resilience is increasingly tested by geopolitical volatility and climate-related yield variability.
Asia Pacific dominates the global landscape, accounting for 44.2% of market share in 2025, a position cemented by the region's role as both the largest producer of palm oil and the most populous consumption base. North America follows with a 32.4% share, while Europe represents a mature but innovation-driven market. The fastest-growing region is Europe, with a projected CAGR of 6.7% through 2034, driven by stringent sustainability regulations and a consumer base willing to pay premiums for certified sustainable and health-optimized oils.
Market Dynamics: Drivers, Restraints, and the Evolving Demand Landscape
The cooking oil market is propelled by a confluence of structural and cyclical factors. Primary among these is the expansion of the global foodservice sector. The proliferation of quick-service restaurants, institutional kitchens, and cloud kitchens creates high-frequency, bulk demand for frying oils. In India, for instance, refined palmolein is a staple across hotels and prepared-food applications, encouraging suppliers to strengthen bulk packaging and contract-based sourcing capabilities. This trend is mirrored globally, reinforcing the commercial end-use segment's dominance, which held a 72.6% revenue share in 2023 per our segment analysis.
A second critical driver is the surge in processed and convenience food consumption. The organized consumer food industry is expanding rapidly, with sales growth in key emerging markets often exceeding 10% annually. Cooking oils serve as both a primary ingredient and a processing medium for snacks, ready-to-eat meals, sauces, and bakery products, creating a multiplier effect on demand. Furthermore, health and wellness trends are reshaping product portfolios. Consumers are increasingly educated on the distinctions between saturated and unsaturated fats, driving demand for oils rich in omega-3 and monounsaturated fats, such as olive, canola, and high-oleic sunflower oil.
However, the market faces significant headwinds. Raw material price volatility is a persistent restraint. Prices for palm, soybean, and sunflower seeds are subject to climatic shocks, geopolitical disruptions, and speculative trading, creating margin uncertainty for processors. This volatility is compounded by import dependence in major consumption markets like India and China, where domestic production cannot meet demand. Currency fluctuations, freight costs, and sudden export policy changes (e.g., Indonesia's palm oil export bans) can rapidly alter the landed cost of feedstock, making supply chain agility a critical competitive differentiator.
Segment Deep-Dive: Product, Processing, and Packaging Insights
The market's architecture is defined by the interplay of product type, processing sophistication, and packaging formats.
By Product Type, palm oil remains the undisputed volume leader, commanding a 31.8% market share in 2025. Its dominance is rooted in cost-efficiency, high oxidative stability at frying temperatures, and versatility across food and non-food applications. Soybean oil follows as a major volume segment, particularly in the Americas, while sunflower oil is the fastest-growing commodity oil, registering a CAGR of 6.8% as health-conscious consumers in Europe and Asia adopt it as a heart-healthy alternative. Olive oil occupies a premium, high-value niche, growing at 6.74% CAGR, driven by the global popularity of Mediterranean diets and its perceived antioxidant benefits.
By Processing Type, refined oils dominate, holding an 80.2% revenue share in 2023. Refining removes impurities, neutralizes flavors, and extends shelf life, making it indispensable for commercial food manufacturers and tropical climates where stability is paramount. However, the unrefined segment is gaining significant momentum, projected to grow at a 6.2% CAGR. This is fueled by the clean-label movement and the premiumization of cold-pressed and organic oils, as evidenced by product launches such as Tata Consumer Products' entry into the premium cold-pressed segment. Unrefined oils preserve natural flavor and aroma, appealing to artisanal and health-focused consumers.
By Packaging, bottles lead the market with a 42.4% share, favored for their convenience, resealability, and ability to preserve freshness. However, the commercial segment's demand for bulk and economic packaging is driving innovation in pouches and jerry cans, particularly in price-sensitive emerging markets.
Regional Outlook: Asia Pacific's Dominance and Europe's Regulatory Push
Asia Pacific's leadership is structural and enduring. The region is the epicenter of global palm oil production (Indonesia and Malaysia account for over 80% of global output) and is home to the world's largest consumer base. Rapid urbanization and the expansion of the middle class in India, China, and Southeast Asia are driving consistent volume growth. Our regional analysis shows the region maintaining a 44.2% share in 2025, with growth further supported by foodservice expansion and the fortification of staple foods.
Cooking Oil Market Regional Market Share
Loading chart...
North America, holding 32.4% of the market, is characterized by a mature but highly dynamic landscape. The U.S. market is witnessing a shift toward high-oleic oils and premium, health-positioned products like avocado and grapeseed oil. The region is also a major producer and exporter of soybean oil, with a significant and growing portion of demand now coming from the biofuel sector, creating competition between food and fuel uses.
Europe is the fastest-growing region at 6.7% CAGR, but its growth narrative is distinct. It is driven by regulation and ethics rather than sheer volume. The EU's Renewable Energy Directive (RED III) and stringent deforestation regulations (EUDR) are reshaping supply chains for palm oil and other commodities. European consumers are highly receptive to certified sustainable, organic, and traceable oils. This has fostered a market where value growth outpaces volume growth, and where compliance with environmental, social, and governance (ESG) criteria is a prerequisite for market access.
Value Chain and Trade Dynamics: From Crush to Consumer
The cooking oil value chain is characterized by high geographical concentration of production and globally dispersed demand. About 90% of oilseed usage is for crushing into meal and oil. The location of crush facilities is determined by transport costs, trade policies, GM crop acceptance, and infrastructure. Soybean crush is projected to expand significantly in Latin America, while palm oil production growth is slowing due to aging trees and sustainability concerns.
Trade is a critical lifeline. Over 37% of global soybean production is traded, and vegetable oil exports account for about 32% of world production. For the 2025/26 marketing year, global soybean production was estimated close to a record 430 million tons, underpinned by strong Brazilian output. However, the international trade landscape is fraught with risk. The dependency of import-heavy nations on a handful of exporters makes them vulnerable to policy shifts and logistical bottlenecks. For instance, the U.S. biodiesel and renewable diesel import scenarios are highly sensitive to policy credits like the Section 45Z credit, which favors domestic production, thereby altering feedstock flows.
A parallel and increasingly important value stream is the Used Cooking Oil (UCO) market, valued at $8.5 billion in 2025 and growing at a 7.9% CAGR. UCO has transformed from a waste disposal problem into a valuable feedstock for biodiesel and sustainable aviation fuel (SAF). North America, with its established collection infrastructure, holds a 43.69% share of this segment. This creates a fascinating circular economy link: the foodservice sector that consumes cooking oil also becomes a supplier of feedstock for renewable fuels, blurring the lines between the food and energy value chains.
Competitive Strategies: Innovation, Sustainability, and Portfolio Optimization
Competition in the cooking oil market is multifaceted. At the commodity end, scale, cost leadership, and supply chain efficiency are paramount. Players like Wilmar International, Archer Daniels Midland (ADM), and Bunge leverage their integrated crush-to-retail operations and global logistics networks to manage price volatility and capture margins. Consolidation via M&A is a common strategy to gain scale and geographic reach.
At the value-added end, success hinges on branding, innovation, and meeting specific consumer needs. Companies are investing heavily in:
Sustainability Certifications: Sourcing RSPO-certified palm oil and adhering to EUDR traceability requirements. This is not just compliance; it is a marketing asset, especially in Europe and North America.
Health & Wellness Positioning: Marketing oils based on their fatty acid profiles, smoking points, and functional benefits. The rise of avocado and grapeseed oil exemplifies this trend.
Packaging Innovation: Introducing convenient, eco-friendly, and single-serve formats to capture the growing demand from smaller households and the foodservice sector.
Strategic partnerships and vertical integration are also key. UCO collector Quatra's agreement to supply TotalEnergies with ~60,000 tonnes of UCO per year for biodiesel and SAF production is a prime example of cross-industry collaboration securing feedstock supply. Similarly, food manufacturers are increasingly entering long-term supply contracts with oil processors to ensure price stability and quality consistency.
Strategic White-Space and Future Outlook
The next decade will likely see the emergence of several strategic white spaces. The fortified and functional oils segment is poised for growth, particularly in emerging markets where micronutrient deficiencies are a public health concern. The B2B ingredient market for specialty oils (high-oleic, non-GMO, organic) will expand as food processors reformulate to meet clean-label and health targets. Furthermore, the integration of digital technologies in refining and quality control, such as AI-based monitoring for oxidation control, will become a competitive differentiator, enabling more consistent product quality and reduced waste.
The market's future is one of resilient growth, but it will be increasingly defined by the ability to navigate complexity—balancing affordability with sustainability, managing supply chain risks, and innovating to meet the evolving demands of health-conscious and ethically-minded consumers. The firms that succeed will be those that view these challenges not as obstacles, but as opportunities to build a more robust, transparent, and value-driven cooking oil ecosystem.
Cooking Oil Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Cooking Oil Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.12% from 2020-2034
Segmentation
By Product Type
Palm Oil
Soy Oil
Sunflower Oil
Peanut Oil
Olive Oil
Rapeseed Oil
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Population growth and rising disposable incomes
3.1.2. Expansion of the foodservice sector
3.1.3. Growth in processed and convenience food consumption
3.1.4. Health and wellness trends favoring unsaturated fats
Table 61: South Africa Cooking Oil Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the global cooking oil market and its growth rate?
The global cooking oil market was valued at **$304.27 billion in 2026** and is projected to reach **$420.27 billion by 2034**, registering a **CAGR of 4.12%** during the forecast period.
2Which region dominates the cooking oil market and which is growing fastest?
Asia Pacific dominates the market with a **44.2% share in 2025**, driven by its large population and role as a major producer. Europe is the fastest-growing region, expected to expand at a **6.7% CAGR** through 2034, largely due to stringent sustainability regulations and a health-conscious consumer base.
3What are the key drivers of the cooking oil market?
Key drivers include population growth, rising disposable incomes in emerging economies, expansion of the global foodservice sector, and increasing demand for processed and convenience foods. Health trends favoring unsaturated fats and the growth of biofuel production also contribute significantly.
4Which cooking oil product type holds the largest market share?
Palm oil is the most consumed cooking oil globally, accounting for **31.8% of the market in 2025**. Its dominance is due to its cost-effectiveness, high oxidative stability for frying, and widespread use in both food and non-food industries.
5What are the main challenges facing the cooking oil market?
The market faces significant challenges from raw material price volatility, which can compress processor margins. Additionally, heavy reliance on imports for key feedstocks in major markets like India and China increases vulnerability to international trade disruptions, currency fluctuations, and policy changes.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary primary research accounts for 70-80% of the total research effort, ensuring data grounded in real-world market intelligence. We conducted extensive interviews with senior executives and decision-makers across the cooking oil value chain.
We interviewed procurement directors, R&D managers, plant operations heads, and supply chain managers from leading cooking oil producers, food processing companies, and foodservice chains. Interviews were conducted via computer-assisted telephone interviewing (CATI) and face-to-face meetings.
We also engaged with agronomists, food scientists, and regulatory affairs specialists to validate technical and compliance aspects.
Our survey panel included a representative mix of company types, formally represented in the company breakdown chart.
Financial data was sourced from Bloomberg, Factiva, Hoovers, and PitchBook to analyze the financial performance and investment strategies of key players.
All sources are meticulously documented and cross-referenced to ensure data integrity.
Demand Modeling & Market Estimation
We employed a multi-layered estimation approach simultaneously using top-down and bottom-up methodologies.
Top-down: Global demand was derived by aggregating consumption volumes from major regions, segmented by end-use (residential, commercial, foodservice, food processor) and product type. Regional production data from primary sources was used to validate imports/exports.
Bottom-up: Market size was calculated by aggregating revenue from key manufacturers and estimating their market shares. We built separate demand models for each product type, processing type, and packaging format.
Quantitative metrics used in our bottom-up calculation include: crush volume and oil yield, per-capita consumption rates, foodservice turnover, processed food production volumes, and retail pricing data across major markets.
All models are validated through multi-level data triangulation, where bottom-up estimates are cross-checked against top-down demand signals and official trade statistics.
Data Accuracy & Quality Check
Our rigorous methodology ensures an estimated data accuracy level of 85-90%.
Data triangulation is performed at every stage: primary interview data is compared against secondary trade data, and company-level revenue is reconciled with industry averages.
We apply statistical validation techniques to identify and correct outliers, and we conduct sanity checks on growth rates and segment shares against historical trends.
Every report is updated to the date of purchase, ensuring that the market sizes, trends, and competitive landscapes reflect the most current information available. Our analysts continuously monitor market developments and integrate real-time data feeds where available.