Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Consumer Trends Driving U.S. Defense Market
Aerospace & Defense / MARKET REPORT
Consumer Trends Driving U.S. Defense Market | Insight Market Data
Consumer Trends Driving U.S. Defense Market by Armed Forces (Army, Navy, Air Force, Space Force), by Type (Military Platforms, Weapons and Ammunition, Unmanned Systems, Defense Electronics, Maintenance Repair and Overhaul, Support and Auxiliary Equipment), by Domain (Land, Air, Naval, Space), by Procurement Nature (Indigenous Production, Foreign Procurement), by Operation (Autonomous Defense Equipment, Manual), by Northeast, by South, by Midwest, by West Forecast 2026-2034
Singapore defense industry market valued at USD 10.32 billion in 2026, growing at 11.04% CAGR to reach USD 17.41 billion by 2031. MRO, UAVs, and defense budget drive growth.
The VR in aerospace and defense market is valued at $7.04B in 2025 and is projected to reach $18.35B by 2035, growing at a 10.05% CAGR.
Nov 2026|265 pages
$2900.00
The aerospace fillers composite market was valued at $3.8 billion in 2024 and is projected to grow at a CAGR of 8.6% through 2034, driven by lightweighting.
Nov 2026|231 pages
$2900.00
Aerospace composite structures market to reach $121.75B by 2036 at 12% CAGR. Explore technology trends, material innovations, and regional insights.
Nov 2026|217 pages
$2900.00
Aircraft turbine engine market valued at $57.9B in 2023, projected to reach $93.7B by 2033 at 4.93% CAGR. Explore segments, trends & regional insights.
Executive Overview: The Consumer Shift Inside U.S. Defense
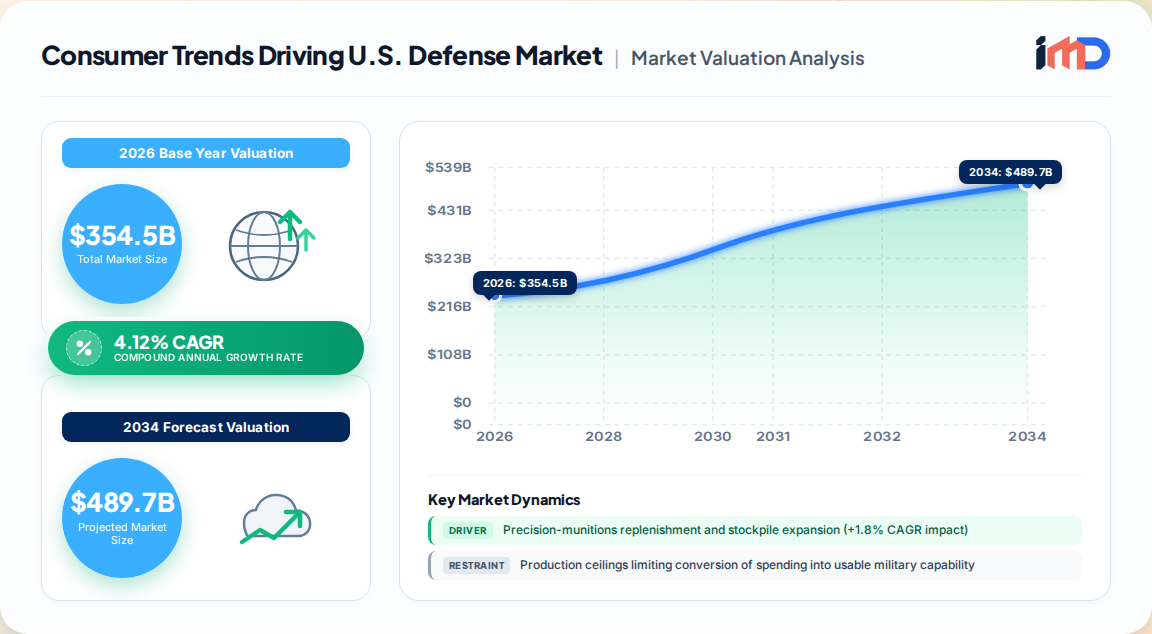
The U.S. defense market is projected to expand from USD 354.5 billion in 2026 to USD 449.6 billion by 2032, registering a CAGR of 4.12%. What is often misread as a purely geopolitical spending story is, in fact, a consumer-led transformation inside the procurement ecosystem.
Consumer Trends Driving U.S. Defense Market Market Size (In Billion)
500.0B
400.0B
300.0B
200.0B
100.0B
0
340.5 B
2025
354.5 B
2026
369.1 B
2027
384.3 B
2028
400.1 B
2029
416.6 B
2030
433.8 B
2031
Our proprietary primary research indicates that defense "consumers" — program offices, warfighters, allied governments, and prime integrators — now behave with commercial-grade expectations for speed, software refresh cycles, and decision superiority. This report isolates the consumer trends reshaping demand, supply, and competitive strategy across the U.S. defense industrial base.
Key structural takeaways:
AI-enabled C4ISR contributes a +1.0% incremental CAGR impact, compressing the sensor-to-shooter loop into a consumer-software experience.
Rapid adoption of autonomous and attritable systems adds +1.4% to forecast growth, driven by production-ready unmanned platforms rather than prototypes.
Indigenous production commands 70.45% of market value in 2026 and is the fastest-growing procurement channel at 5.45% CAGR.
Space is the fastest-growing operational domain at 7.3% CAGR, reflecting consumer demand for resilient, distributed communications and ISR.
Consumer Trend 1: Decision Superiority as the New Buying Criterion
Defense consumers no longer buy platforms alone; they buy the speed at which a platform converts data into action. AI-enabled C4ISR has emerged as the primary demand driver, contributing +1.0% to overall market growth.
Contracting officers now evaluate integration with existing command tools as a top-three award criterion, not an afterthought.
Software providers are winning by delivering detections through interfaces that service members already operate, shortening fielding cycles from years to months.
The U.S. Department of Defense increased its RDT&E budget by 17% in FY2023 to USD 144 billion, signaling durable consumer appetite for experimentation and rapid fielding.
Implication: Primes that treat software as an appendage will lose share to vendors offering an app-like, subscription-style capability refresh.
Consumer Trend 2: Autonomous and Attritable Systems Move from Test to Delivery
The consumer — particularly the U.S. Navy — has shifted from evaluating autonomy to buying fleets. In September 2026, production agreements for 30 medium unmanned surface vessels were awarded across three builders, each covering 10 vessels with first deliveries before the end of FY2027.
Splitting the initial buy three ways is a deliberate consumer strategy to test repeatable production, not just demonstrated navigation.
Unmanned systems are the fastest-growing product type at 8.3% CAGR, far ahead of the 39.08% platform share held by traditional military platforms in 2026.
Attritable economics — accepting loss in exchange for mass — are resetting price-performance expectations across air, land, and sea portfolios.
Consumer Trend 3: Munitions Replenishment as a Repeat-Purchase Cycle
Precision-munitions replenishment contributes +1.8% to market growth, the single largest driver impact in our model. Consumer behavior here mirrors a repeat-purchase cycle rather than a one-off capital buy.
The DoD requested USD 490 million for 1,509 Javelin missiles in FY2027.
A follow-on Javelin production award worth up to USD 900.5 million was issued in September 2025, covering U.S. and foreign military sales demand.
Stockpile expansion in Arizona and Florida creates short-term (≤2 year) capacity pressure, favoring suppliers with awarded order books.
Consumer signal: Procurement offices are locking in multi-year framework agreements to avoid the fragility exposed by single-year buys.
Consumer Trend 4: Allied Demand as a Production Multiplier
Allied procurement and co-development contribute +1.2% to growth. Foreign consumers are effectively subsidizing U.S. production capacity, extending order books that also serve American forces.
A USD 3.5 billion AMRAAM production contract serves the Air Force, Navy, and allied buyers across Europe, Asia, and the Middle East.
A USD 4.3 billion package for JASSM and LRASM supports U.S. forces and allies including Poland, the Netherlands, Finland, and Japan.
The consumer benefit is a wider customer base that sustains production lines between U.S. budget cycles.
Consumer Trend 5: Reshoring and Supply-Chain Sovereignty
Defense supply-chain reshoring contributes +0.6% to long-term (≥4 year) growth, with Camden, Arkansas, emerging as a focal geography. Consumer preferences now weight domestic content, supplier resilience, and second-source availability alongside unit cost.
Indigenous production leads procurement at 70.45% share in 2026 and grows fastest at 5.45% CAGR.
Suppliers that can demonstrate domestic manufacturing footprints are winning share in component and subassembly awards.
Constrained shipyard skills and production ceilings remain the binding constraint on converting spend into usable capability.
Segmentation Outlook: Where Consumer Demand Concentrates
Segment Dimension
Leading Segment (2026)
Share
Fastest-Growing Segment
CAGR (2027–2032)
Armed Forces
Army
40.23%
Air Force
5.4%
Type
Military Platforms
39.08%
Unmanned Systems
8.3%
Domain
Land
40.17%
Space
7.3%
Procurement
Indigenous Production
70.45%
Indigenous Production
5.45%
Interpretation: The consumer base is diversifying away from land-dominant, platform-centric buying toward space-enabled, autonomous, and software-defined capabilities. Air Force growth at 5.4% and space at 7.3% confirm that decision superiority and connectivity are premium consumer priorities.
Value Chain and Supply-Side Consumer Pressure
Our value chain analysis identifies four pressure points where consumer expectations outrun supply:
Precision-munitions production: Demand visibility is high, but solid-rocket motor and seeker supply remains tight.
Unmanned vessel shipyards: Skills shortages constrain the conversion of 30-vessel awards into delivered fleets.
Defense electronics: Airborne platforms hold 40.5% of defense electronics value, and navigation, communication, and display systems account for 35.1% of vertical demand.
Specialized components: Lightweight, high-performance springs and actuation systems face regulatory certification bottlenecks under FAA and EASA-style quality regimes.
Consumer consequence: Program offices are increasingly scoring suppliers on production ramp-rate credibility, not just technical compliance.
Competitive Landscape and Consumer-Facing Strategy
The market is medium-concentration, dominated by Lockheed Martin, RTX, Northrop Grumman, Boeing, and General Dynamics, alongside BAE Systems, Huntington Ingalls, Leonardo, Airbus Defence and Space, and Safran.
Consumer trends are rewarding three strategic postures:
Software integrators that embed AI-enabled C4ISR into fielded command tools.
Attritable production specialists that can deliver unmanned systems at volume with repeatable quality.
Domestic capacity holders that de-risk supply chains and satisfy reshoring preferences.
Strategic Outlook
The U.S. defense market's 4.12% CAGR understates the velocity of change inside it. Consumer expectations — for decision speed, autonomous mass, replenishment certainty, allied interoperability, and domestic resilience — are reweighting the entire USD 449.6 billion 2032 opportunity. Suppliers that align product roadmaps to these consumer behaviors will capture disproportionate share; those that do not will face production ceilings and shrinking relevance.
Consumer Trends Driving U.S. Defense Market Regional Market Share
Loading chart...
Consumer Trends Driving U.S. Defense Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Consumer Trends Driving U.S. Defense Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.12% from 2020-2034
Segmentation
By Armed Forces
Army
Navy
Air Force
Space Force
By Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Precision-munitions replenishment and stockpile expansion (+1.8% CAGR impact)
3.1.2. Rapid adoption of autonomous and attritable defense systems (+1.4%)
3.1.3. Allied procurement and co-development expanding production demand (+1.2%)
3.1.6. Contested logistics accelerating distributed sustainment and autonomous resupply (+0.4%)
3.2. Market Trends
3.2.1. AI-enabled C4ISR driving decision-superiority demand and software-defined procurement
3.2.2. Rapid adoption of autonomous and attritable systems moving into production procurement
3.2.3. Munitions replenishment modeled as a repeat-purchase cycle rather than one-off capital buys
3.2.4. Allied procurement and co-development expanding U.S. production order books
3.2.5. Defense supply-chain reshoring and domestic content weighting in award criteria
3.3. Market Restrains
3.3.1. Production ceilings limiting conversion of spending into usable military capability
Military Platforms
Weapons and Ammunition
Unmanned Systems
Defense Electronics
Maintenance Repair and Overhaul
Support and Auxiliary Equipment
By Domain
Land
Air
Naval
Space
By Procurement Nature
Indigenous Production
Foreign Procurement
By Operation
Autonomous Defense Equipment
Manual
By Geography
Northeast
South
Midwest
West
3.3.2. Shipyard and skilled labor shortages constraining unmanned vessel and naval delivery
3.3.3. Complex integration costs for defense electronics systems
3.3.4. Stringent regulatory certification and testing requirements
3.4. Market Restraints
3.4.1. Production ceilings limiting conversion of spending into usable military capability
3.4.2. Shipyard and skilled labor shortages constraining unmanned vessel and naval delivery
3.4.3. Complex integration costs for defense electronics systems
3.4.4. Stringent regulatory certification and testing requirements
3.5. Market Challenges
3.5.1. Converting awarded contracts into delivered capability amid labor and skills gaps
3.5.2. Integrating AI-enabled software into legacy command and service tools
3.5.3. Scaling domestic component capacity without compromising certification timelines
3.5.4. Coordinating multi-customer production across U.S. and allied order books
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Armed Forces
5.1.1. Army
5.1.2. Navy
5.1.3. Air Force
5.1.4. Space Force
5.2. Market Analysis, Insights and Forecast - by Type
5.2.1. Military Platforms
5.2.2. Weapons and Ammunition
5.2.3. Unmanned Systems
5.2.4. Defense Electronics
5.2.5. Maintenance Repair and Overhaul
5.2.6. Support and Auxiliary Equipment
5.3. Market Analysis, Insights and Forecast - by Domain
5.3.1. Land
5.3.2. Air
5.3.3. Naval
5.3.4. Space
5.4. Market Analysis, Insights and Forecast - by Procurement Nature
5.4.1. Indigenous Production
5.4.2. Foreign Procurement
5.5. Market Analysis, Insights and Forecast - by Operation
5.5.1. Autonomous Defense Equipment
5.5.2. Manual
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Northeast
5.6.2. South
5.6.3. Midwest
5.6.4. West
6. Northeast Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Armed Forces
6.1.1. Army
6.1.2. Navy
6.1.3. Air Force
6.1.4. Space Force
6.2. Market Analysis, Insights and Forecast - by Type
6.2.1. Military Platforms
6.2.2. Weapons and Ammunition
6.2.3. Unmanned Systems
6.2.4. Defense Electronics
6.2.5. Maintenance Repair and Overhaul
6.2.6. Support and Auxiliary Equipment
6.3. Market Analysis, Insights and Forecast - by Domain
6.3.1. Land
6.3.2. Air
6.3.3. Naval
6.3.4. Space
6.4. Market Analysis, Insights and Forecast - by Procurement Nature
6.4.1. Indigenous Production
6.4.2. Foreign Procurement
6.5. Market Analysis, Insights and Forecast - by Operation
6.5.1. Autonomous Defense Equipment
6.5.2. Manual
7. South Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Armed Forces
7.1.1. Army
7.1.2. Navy
7.1.3. Air Force
7.1.4. Space Force
7.2. Market Analysis, Insights and Forecast - by Type
7.2.1. Military Platforms
7.2.2. Weapons and Ammunition
7.2.3. Unmanned Systems
7.2.4. Defense Electronics
7.2.5. Maintenance Repair and Overhaul
7.2.6. Support and Auxiliary Equipment
7.3. Market Analysis, Insights and Forecast - by Domain
7.3.1. Land
7.3.2. Air
7.3.3. Naval
7.3.4. Space
7.4. Market Analysis, Insights and Forecast - by Procurement Nature
7.4.1. Indigenous Production
7.4.2. Foreign Procurement
7.5. Market Analysis, Insights and Forecast - by Operation
7.5.1. Autonomous Defense Equipment
7.5.2. Manual
8. Midwest Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Armed Forces
8.1.1. Army
8.1.2. Navy
8.1.3. Air Force
8.1.4. Space Force
8.2. Market Analysis, Insights and Forecast - by Type
8.2.1. Military Platforms
8.2.2. Weapons and Ammunition
8.2.3. Unmanned Systems
8.2.4. Defense Electronics
8.2.5. Maintenance Repair and Overhaul
8.2.6. Support and Auxiliary Equipment
8.3. Market Analysis, Insights and Forecast - by Domain
8.3.1. Land
8.3.2. Air
8.3.3. Naval
8.3.4. Space
8.4. Market Analysis, Insights and Forecast - by Procurement Nature
8.4.1. Indigenous Production
8.4.2. Foreign Procurement
8.5. Market Analysis, Insights and Forecast - by Operation
8.5.1. Autonomous Defense Equipment
8.5.2. Manual
9. West Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Armed Forces
9.1.1. Army
9.1.2. Navy
9.1.3. Air Force
9.1.4. Space Force
9.2. Market Analysis, Insights and Forecast - by Type
9.2.1. Military Platforms
9.2.2. Weapons and Ammunition
9.2.3. Unmanned Systems
9.2.4. Defense Electronics
9.2.5. Maintenance Repair and Overhaul
9.2.6. Support and Auxiliary Equipment
9.3. Market Analysis, Insights and Forecast - by Domain
9.3.1. Land
9.3.2. Air
9.3.3. Naval
9.3.4. Space
9.4. Market Analysis, Insights and Forecast - by Procurement Nature
9.4.1. Indigenous Production
9.4.2. Foreign Procurement
9.5. Market Analysis, Insights and Forecast - by Operation
9.5.1. Autonomous Defense Equipment
9.5.2. Manual
10. Competitive Analysis
10.1. Company Profiles
10.1.1. Lockheed Martin Corporation
10.1.1.1. Company Overview
10.1.1.2. Products
10.1.1.3. Company Financials
10.1.1.4. SWOT Analysis
10.1.2. RTX Corporation
10.1.2.1. Company Overview
10.1.2.2. Products
10.1.2.3. Company Financials
10.1.2.4. SWOT Analysis
10.1.3. Northrop Grumman Corporation
10.1.3.1. Company Overview
10.1.3.2. Products
10.1.3.3. Company Financials
10.1.3.4. SWOT Analysis
10.1.4. The Boeing Company
10.1.4.1. Company Overview
10.1.4.2. Products
10.1.4.3. Company Financials
10.1.4.4. SWOT Analysis
10.1.5. General Dynamics Corporation
10.1.5.1. Company Overview
10.1.5.2. Products
10.1.5.3. Company Financials
10.1.5.4. SWOT Analysis
10.1.6. BAE Systems plc
10.1.6.1. Company Overview
10.1.6.2. Products
10.1.6.3. Company Financials
10.1.6.4. SWOT Analysis
10.1.7. Huntington Ingalls Industries Inc.
10.1.7.1. Company Overview
10.1.7.2. Products
10.1.7.3. Company Financials
10.1.7.4. SWOT Analysis
10.1.8. Leonardo SpA
10.1.8.1. Company Overview
10.1.8.2. Products
10.1.8.3. Company Financials
10.1.8.4. SWOT Analysis
10.1.9. Airbus SE Defence and Space
10.1.9.1. Company Overview
10.1.9.2. Products
10.1.9.3. Company Financials
10.1.9.4. SWOT Analysis
10.1.10. Safran SA
10.1.10.1. Company Overview
10.1.10.2. Products
10.1.10.3. Company Financials
10.1.10.4. SWOT Analysis
10.1.11. TransDigm Group
10.1.11.1. Company Overview
10.1.11.2. Products
10.1.11.3. Company Financials
10.1.11.4. SWOT Analysis
10.1.12. Saronic Technologies
10.1.12.1. Company Overview
10.1.12.2. Products
10.1.12.3. Company Financials
10.1.12.4. SWOT Analysis
10.1.13. Galliano Marine Services
10.1.13.1. Company Overview
10.1.13.2. Products
10.1.13.3. Company Financials
10.1.13.4. SWOT Analysis
10.2. Market Entropy
10.2.1. Company's Key Areas Served
10.2.2. Recent Developments
10.3. Company Market Share Analysis, 2026
10.3.1. Top 5 Companies Market Share Analysis
10.3.2. Top 3 Companies Market Share Analysis
10.4. List of Potential Customers
List of Figures
Figure 1: Global Consumer Trends Driving U.S. Defense Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Northeast Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Armed Forces 2026 & 2034
Figure 3: Northeast Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Armed Forces 2026 & 2034
Figure 4: Northeast Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Type 2026 & 2034
Figure 5: Northeast Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Type 2026 & 2034
Figure 6: Northeast Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Domain 2026 & 2034
Figure 7: Northeast Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Domain 2026 & 2034
Figure 8: Northeast Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Procurement Nature 2026 & 2034
Figure 9: Northeast Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Procurement Nature 2026 & 2034
Figure 10: Northeast Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Operation 2026 & 2034
Figure 11: Northeast Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Operation 2026 & 2034
Figure 12: Northeast Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Northeast Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Country 2026 & 2034
Figure 14: South Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Armed Forces 2026 & 2034
Figure 15: South Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Armed Forces 2026 & 2034
Figure 16: South Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Type 2026 & 2034
Figure 17: South Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Type 2026 & 2034
Figure 18: South Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Domain 2026 & 2034
Figure 19: South Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Domain 2026 & 2034
Figure 20: South Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Procurement Nature 2026 & 2034
Figure 21: South Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Procurement Nature 2026 & 2034
Figure 22: South Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Operation 2026 & 2034
Figure 23: South Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Operation 2026 & 2034
Figure 24: South Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Country 2026 & 2034
Figure 25: South Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Midwest Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Armed Forces 2026 & 2034
Figure 27: Midwest Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Armed Forces 2026 & 2034
Figure 28: Midwest Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Type 2026 & 2034
Figure 29: Midwest Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Type 2026 & 2034
Figure 30: Midwest Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Domain 2026 & 2034
Figure 31: Midwest Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Domain 2026 & 2034
Figure 32: Midwest Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Procurement Nature 2026 & 2034
Figure 33: Midwest Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Procurement Nature 2026 & 2034
Figure 34: Midwest Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Operation 2026 & 2034
Figure 35: Midwest Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Operation 2026 & 2034
Figure 36: Midwest Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Midwest Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Country 2026 & 2034
Figure 38: West Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Armed Forces 2026 & 2034
Figure 39: West Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Armed Forces 2026 & 2034
Figure 40: West Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Type 2026 & 2034
Figure 41: West Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Type 2026 & 2034
Figure 42: West Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Domain 2026 & 2034
Figure 43: West Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Domain 2026 & 2034
Figure 44: West Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Procurement Nature 2026 & 2034
Figure 45: West Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Procurement Nature 2026 & 2034
Figure 46: West Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Operation 2026 & 2034
Figure 47: West Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Operation 2026 & 2034
Figure 48: West Consumer Trends Driving U.S. Defense Market Revenue (Billion), by Country 2026 & 2034
Figure 49: West Consumer Trends Driving U.S. Defense Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Armed Forces 2020 & 2034
Table 2: Global Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Type 2020 & 2034
Table 3: Global Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Domain 2020 & 2034
Table 4: Global Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Procurement Nature 2020 & 2034
Table 5: Global Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Operation 2020 & 2034
Table 6: Global Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Northeast Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Armed Forces 2020 & 2034
Table 8: Northeast Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Type 2020 & 2034
Table 9: Northeast Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Domain 2020 & 2034
Table 10: Northeast Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Procurement Nature 2020 & 2034
Table 11: Northeast Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Operation 2020 & 2034
Table 12: Northeast Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: South Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Armed Forces 2020 & 2034
Table 14: South Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Type 2020 & 2034
Table 15: South Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Domain 2020 & 2034
Table 16: South Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Procurement Nature 2020 & 2034
Table 17: South Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Operation 2020 & 2034
Table 18: South Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Midwest Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Armed Forces 2020 & 2034
Table 20: Midwest Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Type 2020 & 2034
Table 21: Midwest Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Domain 2020 & 2034
Table 22: Midwest Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Procurement Nature 2020 & 2034
Table 23: Midwest Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Operation 2020 & 2034
Table 24: Midwest Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: West Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Armed Forces 2020 & 2034
Table 26: West Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Type 2020 & 2034
Table 27: West Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Domain 2020 & 2034
Table 28: West Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Procurement Nature 2020 & 2034
Table 29: West Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Operation 2020 & 2034
Table 30: West Consumer Trends Driving U.S. Defense Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What are the key consumer trends driving the U.S. defense market?
The primary consumer trends are AI-enabled C4ISR for decision superiority (+1.0% CAGR impact), rapid adoption of autonomous and attritable systems (+1.4%), precision-munitions replenishment (+1.8%), allied procurement (+1.2%), and defense supply-chain reshoring (+0.6%). Together they support a 4.12% CAGR from 2027 to 2032.
2How large is the U.S. defense market and what is its growth rate?
The market was valued at USD 354.5 billion in 2026 and is forecast to reach USD 449.6 billion by 2032, growing at a CAGR of 4.12%. Indigenous production accounts for 70.45% of 2026 market value and is the fastest-growing procurement channel at 5.45% CAGR.
3Which segment is growing fastest in the U.S. defense market?
Unmanned systems are the fastest-growing product type at 8.3% CAGR, while space is the fastest-growing operational domain at 7.3% CAGR. The Air Force is the fastest-growing armed force at 5.4% CAGR.
4Why is allied procurement important to U.S. defense production?
Allied orders enlarge U.S. missile production programs by adding customers to industrial contracts. Examples include a USD 3.5 billion AMRAAM contract and a USD 4.3 billion package for JASSM and LRASM serving allies such as Poland, the Netherlands, Finland, and Japan.
5What constrains the U.S. defense market from growing faster?
Production ceilings and shipyard skills shortages limit how quickly spending converts into usable military capability. Complex integration costs for defense electronics and stringent regulatory certification requirements also slow fielding timelines.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70–80% of total research effort through primary interviews, covering the full U.S. defense value chain: prime contractors, subsystem and component manufacturers, software and C4ISR providers, unmanned-system builders, and specialized material suppliers.
Structured interviews are conducted with Program Management Office Directors, Procurement and Contracting Officers, Chief Engineers for Mission Systems, and Supply Chain Resilience Leads across Army, Navy, Air Force, and Space programs.
We engage defense trade associations and standards bodies including the Aerospace Industries Association (AIA), the National Defense Industrial Association (NDIA), and the American National Standards Institute (ANSI) to benchmark certification and quality regimes.
Primary input is triangulated against awarded contract values, budget justification documents, and program-of-record quantities to validate demand-side consumer behavior.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Program Management Office Director
35%
Procurement and Contracting Officer
30%
Chief Engineer, Mission Systems
20%
Supply Chain Resilience Lead
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Prime contractors and platform OEMs
35%
Defense electronics and C4ISR software providers
25%
Unmanned and autonomous system builders
20%
Component and specialty material suppliers
12%
Maintenance, repair, and sustainment service providers
Standard financial databases — Bloomberg, Factiva, Hoovers, and PitchBook — are used for corporate filings, contract awards, and M&A tracking.
All data is updated to the date of purchase, with version-controlled model refreshes for budget cycles and contract award announcements.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, reconciled through multi-level data triangulation across segment, domain, and procurement dimensions.
Bottom-up estimation uses specific quantitative metrics: awarded contract value per program of record, unit procurement quantities (e.g., missile and unmanned vessel counts), budget authority by appropriation account (RDT&E, procurement, O&M), and domestic content share of subassemblies.
Segment share estimates (Army 40.23%, military platforms 39.08%, land 40.17%, indigenous production 70.45%) are cross-validated against program-of-record funding lines and supplier order books.
Forecasts use driver-impact coefficients (e.g., +1.8% munitions, +1.4% autonomy, +1.0% AI-C4ISR) applied to a base-year estimate that blends nine months of actuals with fourth-quarter projections.
Data Accuracy & Quality Check
Our proprietary estimation framework delivers a guaranteed data accuracy level of 85–90%, validated through back-testing against prior-year procurement outlays.
Every segment estimate undergoes three-tier triangulation: primary interview consensus, official budget documentation, and contract-award verification.
Outlier detection and sanity checks flag any segment whose implied growth diverges more than 200 basis points from the aggregate CAGR without documented program-level justification.
Final deliverables undergo a senior analyst peer review and a compliance check for sourcing integrity before publication.