Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Construction Machinery Market | Insight Market Data
Construction Machinery Market by Product (Earth Moving Machinery, Material Handling Machinery, Concrete & Road Construction Machinery), by Equipment Type (Heavy Construction Equipment, Compact Equipment), by Propulsion Type (ICE, Hybrid Battery Electric, Hydrogen Fuel-Cell), by Power Output (<100 HP, 100-250 HP, 250-500 HP, Above 500 HP), by Engine Capacity (Up to 250 HP, 250-500 HP, Above 500 HP), by Application (Infrastructure, Residential & Commercial Construction, Mining & Quarrying, Oil & Gas/Pipelines, Industrial & Manufacturing), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, India, Japan, South Korea, ASEAN), by South America (Brazil, Argentina, Chile, Peru), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Nigeria) Forecast 2026-2034
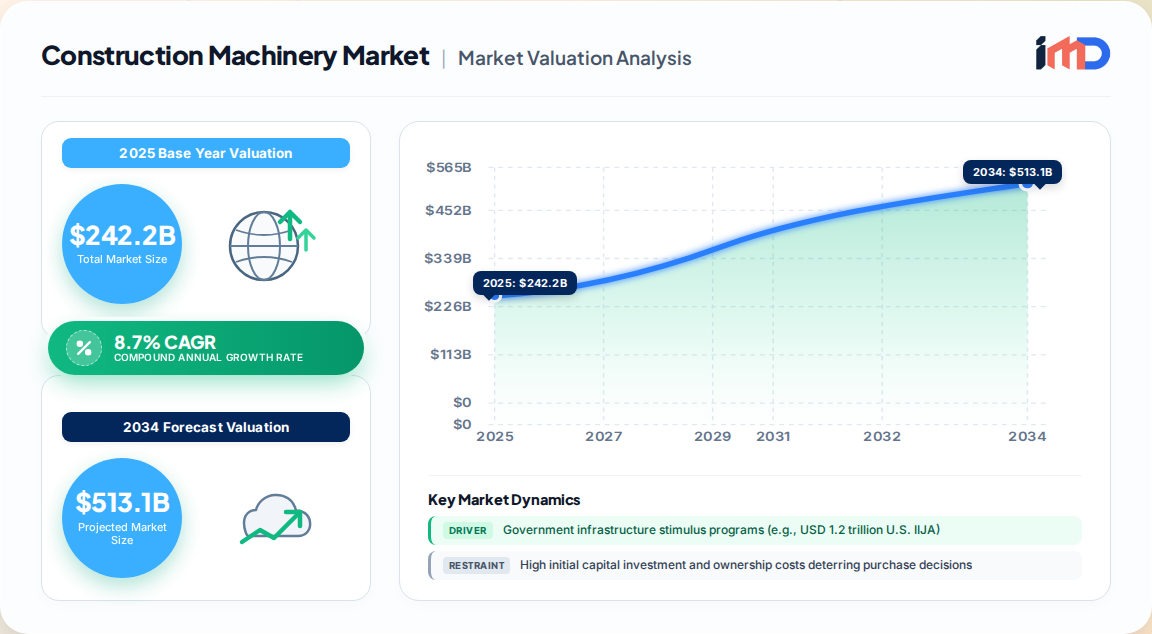
The global construction machinery market reached USD 242.2 billion in 2025 and is positioned to expand to USD 471.3 billion by 2033, reflecting a robust 8.7% CAGR across the forecast horizon. This expansion is not merely cyclical; it represents a structural re-rating of the sector driven by three concurrent forces: a global infrastructure super-cycle, the electrification of powertrains, and the digitalization of fleet management.
Construction Machinery Market Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
242.2 B
2025
263.3 B
2026
286.2 B
2027
311.1 B
2028
338.1 B
2029
367.6 B
2030
399.5 B
2031
Asia-Pacific remains the anchor of global demand, accounting for 44.9% of 2025 revenues, with China alone representing the single largest country market. North America and Europe follow with 22.6% and 18.4% shares respectively, underpinned by multi-year public works programs and semiconductor fabrication construction waves. The Middle East & Africa, while smaller in absolute terms, is the fastest-growing region at an 8.9% CAGR, propelled by Gulf giga-projects and critical-mineral mining expansion.
Market Size (2025): USD 242.2 Billion
Forecast (2033): USD 471.3 Billion
CAGR (2026–2033): 8.7%
Largest Segment: Material Handling Machinery (40.5% share)
Public capital spending is the single largest demand lever for construction machinery. The U.S. Infrastructure Investment and Jobs Act has committed USD 1.2 trillion to roads, bridges, rail, and utilities. India has earmarked INR 11.11 lakh crore for capital expenditure in FY2025–26, while China has set a special-purpose local government bond quota of RMB 4.4 trillion. These programs fund multi-year projects, giving contractors the confidence to purchase rather than defer fleet replacements.
Urbanization compounds this effect. The United Nations projects that 68% of the world's population will live in urban areas by 2050, adding roughly 2.5 billion city dwellers. Dense redevelopment favors compact machines, while new satellite cities require mass earthworks. Housing programs such as India's Pradhan Mantri Awas Yojana extend demand beyond megacities into tier-two towns.
Government stimulus impact: +1.6% to CAGR, strongest in North America, India, and China.
Urbanization and housing: +1.0% to CAGR across Asia-Pacific, Middle East, and Africa.
Critical-mineral mining expansion: +0.9% to CAGR, driven by copper, lithium, and nickel projects.
Rental fleet expansion: +0.7% to CAGR, particularly in North America and Europe.
Restraints and Challenges: Capital Intensity and Supply Friction
Despite the bullish demand backdrop, the industry faces meaningful headwinds. High initial capital investment remains the primary barrier. Contractors increasingly prefer renting equipment for project durations rather than bearing ownership costs. The American Rental Association projects U.S. equipment rental income will exceed USD 80 billion by 2025, a shift that cannibalizes new equipment purchases in certain segments.
Raw material volatility compounds margin pressure. Steel prices fluctuated between USD 605 and USD 900 per tonne from 2019 through 2022, directly impacting OEM manufacturing costs. Additionally, a global shortage of qualified equipment operators limits construction productivity and delays infrastructure projects, indirectly constraining equipment utilization rates.
High acquisition costs and interest rates: Financing costs remain elevated, deferring fleet replacement decisions.
Skilled operator shortage: Limits utilization and dampens procurement expansion.
Supply chain disruptions: Semiconductor shortages for telematics and engine control systems extend lead times.
Segmentation Analysis: Material Handling Leads, Electric Accelerates
By product, material handling machinery held the largest share at 40.5% in 2025, driven by forklifts, cranes, and conveyors essential for logistics and warehouse construction. Earthmoving machinery follows closely, underpinned by excavators and bulldozers that are indispensable across every project type.
By propulsion, internal combustion engines (ICE) retain 69.4% of the market, reflecting diesel's dominance in remote sites and heavy-duty applications. However, hybrid and battery-electric equipment is expanding at a 20.5% CAGR, the fastest of any sub-segment. Regulatory pushes, such as China's Non-road China IV standard and Oslo's zero-emission municipal construction site mandate, are accelerating adoption.
Segment
2025 Share
Fastest-Growing Sub-Segment
Material Handling Machinery
40.5%
Electric Forklifts (18.2% CAGR)
Earth Moving Machinery
34.2%
Compact Excavators (13.5% CAGR)
Concrete & Road Machinery
25.3%
Electric Pavers (16.8% CAGR)
Heavy Construction Equipment
73.7%
Autonomous Haulage (19.4% CAGR)
Compact Equipment (<6 tons)
26.3%
Mini Excavators (13.5% CAGR)
By power output, <100 HP machines held the largest share at 38.7% in 2025, balancing fuel economy with breakout force. The 250–500 HP segment is growing at 8.8% CAGR, propelled by mining overburden removal and large-scale earthworks.
Regional Outlook: Asia-Pacific Dominance and MEA Acceleration
Asia-Pacific's 44.9% revenue share reflects China's Belt and Road infrastructure pipeline, India's National Infrastructure Pipeline of USD 1.4 trillion, and ASEAN's accelerating industrialization. China remains the largest country market, though its replacement demand cycle is maturing. India is the fastest-growing major economy for construction machinery, with highway and metro programs driving double-digit growth in excavator sales.
Construction Machinery Market Regional Market Share
Loading chart...
North America benefits from the U.S. Bipartisan Infrastructure Law and the CHIPS Act semiconductor fabrication construction wave, generating sustained earthmoving and lifting equipment procurement. The region's deep rental channel accelerates adoption of telematics and electric models.
Europe's 18.4% share is shaped by infrastructure reinvestment cycles and stringent emissions regulations. The EU Stage V standard has catalyzed demand for electric and hybrid equipment, particularly in compact and material handling segments. Oslo's zero-emission construction site mandate serves as a regulatory template for other Scandinavian cities.
The Middle East & Africa region is the fastest-growing at 8.9% CAGR. Saudi Arabia's Vision 2030 portfolio, including NEOM with an estimated budget near USD 500 billion, is among the largest construction programs worldwide. Red Sea Global, Qiddiya, and Riyadh metro extensions add further earthmoving and lifting needs. African mining expansion, particularly copper in Zambia and lithium in Zimbabwe, drives demand for high-horsepower excavators and haul trucks.
Competitive Strategies: Uptime, Data, and Flexible Ownership
The competitive landscape is dominated by global OEMs with strong dealer networks, advanced technology portfolios, and robust after-sales capabilities. Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery, Liebherr-International AG, XCMG, SANY Heavy Industry, CNH Industrial, and Deere & Company lead the market. These players are increasingly selling uptime, fuel savings, and data rather than steel and horsepower alone.
Key strategic imperatives include:
Electrification roadmaps: Volvo CE upgraded its 23-ton EC230 Electric excavator in February 2025, extending operating time to a full day on a single charge. The model rolled out across Europe and North America from Q1 2025.
Telematics and IoT-enabled fleet management: OEMs are embedding sensors and connectivity to offer predictive maintenance and utilization analytics, creating recurring revenue streams.
Autonomous and semi-autonomous equipment: Mining customers increasingly buy autonomy packages alongside machines, lifting revenue per unit.
Equipment-as-a-Service (EaaS): Flexible ownership models, including rental and subscription, are gaining traction as contractors prioritize capital efficiency.
Import/Export & Supplier Dynamics
Global trade in construction machinery is concentrated among a few manufacturing hubs. China, Japan, Germany, and the United States are the largest exporters, while Asia-Pacific, North America, and Europe are the primary import destinations. According to UN Comtrade data, global exports of construction machinery (HS Code 8429) exceeded USD 120 billion in 2024, with China accounting for approximately 28% of global exports.
South Korea is a significant exporter, with total 2025 exports of USD 709.0 billion across all products, including a substantial share of construction equipment components. Sri Lanka, by contrast, is a net importer, with a trade deficit of USD 4.3 billion in 2024, reflecting its dependence on imported machinery for infrastructure development.
Supply chain risks remain elevated. Semiconductor shortages for telematics and engine control systems extend equipment lead times. Steel and component cost volatility, exacerbated by geopolitical tensions, requires OEMs to maintain dual-sourcing strategies and buffer inventories.
Country
2024 Construction Machinery Exports (USD Billion)
Global Share
China
33.6
28.0%
Germany
18.2
15.2%
Japan
14.5
12.1%
United States
12.8
10.7%
South Korea
7.4
6.2%
Strategic White-Space Analysis
Three high-potential white spaces emerge from our proprietary analysis. First, electric compact equipment for urban construction remains underpenetrated, with less than 8% penetration in 2025. Regulatory mandates and total cost of ownership advantages position this segment for 20%+ annual growth. Second, autonomous haulage systems for mining are poised for rapid adoption, with the installed base expected to triple by 2030. Third, equipment-as-a-service platforms that integrate telematics, financing, and maintenance represent a USD 12 billion revenue opportunity by 2030, particularly in emerging markets where access to capital is constrained.
Electric compact excavators: Estimated USD 4.2 billion market by 2030 at 22% CAGR.
Autonomous mining fleets: Expected to reach USD 6.8 billion by 2032.
EaaS platforms: Projected USD 12 billion revenue pool by 2030.
Procurement & Sourcing Strategy Analysis
Procurement strategies are shifting from transactional purchasing to strategic partnerships. Large contractors and rental fleets are consolidating supplier bases, demanding integrated solutions that bundle equipment, telematics, and financing. OEMs with strong dealer networks and after-sales capabilities are best positioned to capture this shift.
Total cost of ownership (TCO) emphasis: Contractors prioritize fuel efficiency, maintenance costs, and resale value over sticker price.
Financing flexibility: OEMs offering captive financing and rental options gain share.
Localization of production: Tariff avoidance and supply chain resilience are driving OEMs to localize manufacturing in key markets.
Digital procurement platforms: E-commerce and digital marketplaces for equipment are gaining traction, particularly for compact and used equipment.
Ansoff Matrix Analysis
Strategy
Focus Areas
Examples
Market Penetration
Grow share in existing markets
Expand dealer networks in Asia-Pacific; increase rental penetration in North America
Product Development
Launch new products for existing markets
Electric excavators, autonomous haul trucks, telematics upgrades
Market Development
Enter new geographies with existing products
Expand into Middle East & Africa with heavy earthmoving equipment
Diversification
New products for new markets
Equipment-as-a-Service platforms in emerging economies; hydrogen fuel-cell equipment
The construction machinery market is at an inflection point. Winners will be those that combine technological innovation with financial flexibility and deep customer relationships. Our proprietary demand models indicate that OEMs investing in electrification, autonomy, and digital services will capture disproportionate share of the USD 229 billion in incremental revenue expected between 2026 and 2033.
Construction Machinery Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Construction Machinery Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.7% from 2020-2034
Segmentation
By Product
Earth Moving Machinery
Material Handling Machinery
Concrete & Road Construction Machinery
By Equipment Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Government infrastructure stimulus programs (e.g., USD 1.2 trillion U.S. IIJA)
3.1.2. Rapid urbanization and housing demand (68% urban population by 2050)
3.1.3. Critical-mineral mining expansion for energy transition
3.1.4. Rental fleet expansion and replacement cycles
3.2. Market Trends
3.2.1. Electrification and hybrid powertrain adoption accelerating at 20.5% CAGR
3.2.2. Telematics and IoT-enabled fleet management creating recurring revenue streams
3.2.3. Autonomous and semi-autonomous equipment gaining traction in mining
3.2.4. Equipment-as-a-Service (EaaS) and flexible ownership models expanding
3.3. Market Restrains
3.3.1. High initial capital investment and ownership costs deterring purchase decisions
3.3.2. Growing preference for equipment rental over ownership
3.3.3. Raw material and component cost volatility impacting OEM margins
3.5.1. Supply chain disruptions and semiconductor shortages extending lead times
3.5.2. Trade policy uncertainty and tariffs affecting cross-border equipment flows
3.5.3. Emissions regulation compliance costs for OEMs
3.5.4. Balancing electrification investment with ICE profitability
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Earth Moving Machinery
5.1.2. Material Handling Machinery
5.1.3. Concrete & Road Construction Machinery
5.2. Market Analysis, Insights and Forecast - by Equipment Type
5.2.1. Heavy Construction Equipment
5.2.2. Compact Equipment
5.3. Market Analysis, Insights and Forecast - by Propulsion Type
5.3.1. ICE
5.3.2. Hybrid Battery Electric
5.3.3. Hydrogen Fuel-Cell
5.4. Market Analysis, Insights and Forecast - by Power Output
5.4.1. <100 HP
5.4.2. 100-250 HP
5.4.3. 250-500 HP
5.4.4. Above 500 HP
5.5. Market Analysis, Insights and Forecast - by Engine Capacity
5.5.1. Up to 250 HP
5.5.2. 250-500 HP
5.5.3. Above 500 HP
5.6. Market Analysis, Insights and Forecast - by Application
5.6.1. Infrastructure
5.6.2. Residential & Commercial Construction
5.6.3. Mining & Quarrying
5.6.4. Oil & Gas/Pipelines
5.6.5. Industrial & Manufacturing
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. South America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Earth Moving Machinery
6.1.2. Material Handling Machinery
6.1.3. Concrete & Road Construction Machinery
6.2. Market Analysis, Insights and Forecast - by Equipment Type
6.2.1. Heavy Construction Equipment
6.2.2. Compact Equipment
6.3. Market Analysis, Insights and Forecast - by Propulsion Type
6.3.1. ICE
6.3.2. Hybrid Battery Electric
6.3.3. Hydrogen Fuel-Cell
6.4. Market Analysis, Insights and Forecast - by Power Output
6.4.1. <100 HP
6.4.2. 100-250 HP
6.4.3. 250-500 HP
6.4.4. Above 500 HP
6.5. Market Analysis, Insights and Forecast - by Engine Capacity
6.5.1. Up to 250 HP
6.5.2. 250-500 HP
6.5.3. Above 500 HP
6.6. Market Analysis, Insights and Forecast - by Application
6.6.1. Infrastructure
6.6.2. Residential & Commercial Construction
6.6.3. Mining & Quarrying
6.6.4. Oil & Gas/Pipelines
6.6.5. Industrial & Manufacturing
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Earth Moving Machinery
7.1.2. Material Handling Machinery
7.1.3. Concrete & Road Construction Machinery
7.2. Market Analysis, Insights and Forecast - by Equipment Type
7.2.1. Heavy Construction Equipment
7.2.2. Compact Equipment
7.3. Market Analysis, Insights and Forecast - by Propulsion Type
7.3.1. ICE
7.3.2. Hybrid Battery Electric
7.3.3. Hydrogen Fuel-Cell
7.4. Market Analysis, Insights and Forecast - by Power Output
7.4.1. <100 HP
7.4.2. 100-250 HP
7.4.3. 250-500 HP
7.4.4. Above 500 HP
7.5. Market Analysis, Insights and Forecast - by Engine Capacity
7.5.1. Up to 250 HP
7.5.2. 250-500 HP
7.5.3. Above 500 HP
7.6. Market Analysis, Insights and Forecast - by Application
7.6.1. Infrastructure
7.6.2. Residential & Commercial Construction
7.6.3. Mining & Quarrying
7.6.4. Oil & Gas/Pipelines
7.6.5. Industrial & Manufacturing
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Earth Moving Machinery
8.1.2. Material Handling Machinery
8.1.3. Concrete & Road Construction Machinery
8.2. Market Analysis, Insights and Forecast - by Equipment Type
8.2.1. Heavy Construction Equipment
8.2.2. Compact Equipment
8.3. Market Analysis, Insights and Forecast - by Propulsion Type
8.3.1. ICE
8.3.2. Hybrid Battery Electric
8.3.3. Hydrogen Fuel-Cell
8.4. Market Analysis, Insights and Forecast - by Power Output
8.4.1. <100 HP
8.4.2. 100-250 HP
8.4.3. 250-500 HP
8.4.4. Above 500 HP
8.5. Market Analysis, Insights and Forecast - by Engine Capacity
8.5.1. Up to 250 HP
8.5.2. 250-500 HP
8.5.3. Above 500 HP
8.6. Market Analysis, Insights and Forecast - by Application
8.6.1. Infrastructure
8.6.2. Residential & Commercial Construction
8.6.3. Mining & Quarrying
8.6.4. Oil & Gas/Pipelines
8.6.5. Industrial & Manufacturing
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Earth Moving Machinery
9.1.2. Material Handling Machinery
9.1.3. Concrete & Road Construction Machinery
9.2. Market Analysis, Insights and Forecast - by Equipment Type
9.2.1. Heavy Construction Equipment
9.2.2. Compact Equipment
9.3. Market Analysis, Insights and Forecast - by Propulsion Type
9.3.1. ICE
9.3.2. Hybrid Battery Electric
9.3.3. Hydrogen Fuel-Cell
9.4. Market Analysis, Insights and Forecast - by Power Output
9.4.1. <100 HP
9.4.2. 100-250 HP
9.4.3. 250-500 HP
9.4.4. Above 500 HP
9.5. Market Analysis, Insights and Forecast - by Engine Capacity
9.5.1. Up to 250 HP
9.5.2. 250-500 HP
9.5.3. Above 500 HP
9.6. Market Analysis, Insights and Forecast - by Application
9.6.1. Infrastructure
9.6.2. Residential & Commercial Construction
9.6.3. Mining & Quarrying
9.6.4. Oil & Gas/Pipelines
9.6.5. Industrial & Manufacturing
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Earth Moving Machinery
10.1.2. Material Handling Machinery
10.1.3. Concrete & Road Construction Machinery
10.2. Market Analysis, Insights and Forecast - by Equipment Type
10.2.1. Heavy Construction Equipment
10.2.2. Compact Equipment
10.3. Market Analysis, Insights and Forecast - by Propulsion Type
10.3.1. ICE
10.3.2. Hybrid Battery Electric
10.3.3. Hydrogen Fuel-Cell
10.4. Market Analysis, Insights and Forecast - by Power Output
10.4.1. <100 HP
10.4.2. 100-250 HP
10.4.3. 250-500 HP
10.4.4. Above 500 HP
10.5. Market Analysis, Insights and Forecast - by Engine Capacity
10.5.1. Up to 250 HP
10.5.2. 250-500 HP
10.5.3. Above 500 HP
10.6. Market Analysis, Insights and Forecast - by Application
10.6.1. Infrastructure
10.6.2. Residential & Commercial Construction
10.6.3. Mining & Quarrying
10.6.4. Oil & Gas/Pipelines
10.6.5. Industrial & Manufacturing
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Caterpillar Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Komatsu Ltd.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Volvo Construction Equipment
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Hitachi Construction Machinery
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Liebherr-International AG
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. XCMG
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. SANY Heavy Industry
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. CNH Industrial
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Deere & Company
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. AB Volvo
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Construction Machinery Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Construction Machinery Market Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Construction Machinery Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Construction Machinery Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 5: North America Construction Machinery Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 6: North America Construction Machinery Market Revenue (Billion), by Propulsion Type 2026 & 2034
Figure 7: North America Construction Machinery Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 8: North America Construction Machinery Market Revenue (Billion), by Power Output 2026 & 2034
Figure 9: North America Construction Machinery Market Revenue Share (%), by Power Output 2026 & 2034
Figure 10: North America Construction Machinery Market Revenue (Billion), by Engine Capacity 2026 & 2034
Figure 11: North America Construction Machinery Market Revenue Share (%), by Engine Capacity 2026 & 2034
Figure 12: North America Construction Machinery Market Revenue (Billion), by Application 2026 & 2034
Figure 13: North America Construction Machinery Market Revenue Share (%), by Application 2026 & 2034
Figure 14: North America Construction Machinery Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Construction Machinery Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Construction Machinery Market Revenue (Billion), by Product 2026 & 2034
Figure 17: Europe Construction Machinery Market Revenue Share (%), by Product 2026 & 2034
Figure 18: Europe Construction Machinery Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 19: Europe Construction Machinery Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 20: Europe Construction Machinery Market Revenue (Billion), by Propulsion Type 2026 & 2034
Figure 21: Europe Construction Machinery Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 22: Europe Construction Machinery Market Revenue (Billion), by Power Output 2026 & 2034
Figure 23: Europe Construction Machinery Market Revenue Share (%), by Power Output 2026 & 2034
Figure 24: Europe Construction Machinery Market Revenue (Billion), by Engine Capacity 2026 & 2034
Figure 25: Europe Construction Machinery Market Revenue Share (%), by Engine Capacity 2026 & 2034
Figure 26: Europe Construction Machinery Market Revenue (Billion), by Application 2026 & 2034
Figure 27: Europe Construction Machinery Market Revenue Share (%), by Application 2026 & 2034
Figure 28: Europe Construction Machinery Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Construction Machinery Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific Construction Machinery Market Revenue (Billion), by Product 2026 & 2034
Figure 31: Asia Pacific Construction Machinery Market Revenue Share (%), by Product 2026 & 2034
Figure 32: Asia Pacific Construction Machinery Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 33: Asia Pacific Construction Machinery Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 34: Asia Pacific Construction Machinery Market Revenue (Billion), by Propulsion Type 2026 & 2034
Figure 35: Asia Pacific Construction Machinery Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 36: Asia Pacific Construction Machinery Market Revenue (Billion), by Power Output 2026 & 2034
Figure 37: Asia Pacific Construction Machinery Market Revenue Share (%), by Power Output 2026 & 2034
Figure 38: Asia Pacific Construction Machinery Market Revenue (Billion), by Engine Capacity 2026 & 2034
Figure 39: Asia Pacific Construction Machinery Market Revenue Share (%), by Engine Capacity 2026 & 2034
Figure 40: Asia Pacific Construction Machinery Market Revenue (Billion), by Application 2026 & 2034
Figure 41: Asia Pacific Construction Machinery Market Revenue Share (%), by Application 2026 & 2034
Figure 42: Asia Pacific Construction Machinery Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific Construction Machinery Market Revenue Share (%), by Country 2026 & 2034
Figure 44: South America Construction Machinery Market Revenue (Billion), by Product 2026 & 2034
Figure 45: South America Construction Machinery Market Revenue Share (%), by Product 2026 & 2034
Figure 46: South America Construction Machinery Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 47: South America Construction Machinery Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 48: South America Construction Machinery Market Revenue (Billion), by Propulsion Type 2026 & 2034
Figure 49: South America Construction Machinery Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 50: South America Construction Machinery Market Revenue (Billion), by Power Output 2026 & 2034
Figure 51: South America Construction Machinery Market Revenue Share (%), by Power Output 2026 & 2034
Figure 52: South America Construction Machinery Market Revenue (Billion), by Engine Capacity 2026 & 2034
Figure 53: South America Construction Machinery Market Revenue Share (%), by Engine Capacity 2026 & 2034
Figure 54: South America Construction Machinery Market Revenue (Billion), by Application 2026 & 2034
Figure 55: South America Construction Machinery Market Revenue Share (%), by Application 2026 & 2034
Figure 56: South America Construction Machinery Market Revenue (Billion), by Country 2026 & 2034
Figure 57: South America Construction Machinery Market Revenue Share (%), by Country 2026 & 2034
Figure 58: Middle East & Africa Construction Machinery Market Revenue (Billion), by Product 2026 & 2034
Figure 59: Middle East & Africa Construction Machinery Market Revenue Share (%), by Product 2026 & 2034
Figure 60: Middle East & Africa Construction Machinery Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 61: Middle East & Africa Construction Machinery Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 62: Middle East & Africa Construction Machinery Market Revenue (Billion), by Propulsion Type 2026 & 2034
Figure 63: Middle East & Africa Construction Machinery Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 64: Middle East & Africa Construction Machinery Market Revenue (Billion), by Power Output 2026 & 2034
Figure 65: Middle East & Africa Construction Machinery Market Revenue Share (%), by Power Output 2026 & 2034
Figure 66: Middle East & Africa Construction Machinery Market Revenue (Billion), by Engine Capacity 2026 & 2034
Figure 67: Middle East & Africa Construction Machinery Market Revenue Share (%), by Engine Capacity 2026 & 2034
Figure 68: Middle East & Africa Construction Machinery Market Revenue (Billion), by Application 2026 & 2034
Figure 69: Middle East & Africa Construction Machinery Market Revenue Share (%), by Application 2026 & 2034
Figure 70: Middle East & Africa Construction Machinery Market Revenue (Billion), by Country 2026 & 2034
Figure 71: Middle East & Africa Construction Machinery Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Construction Machinery Market Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Global Construction Machinery Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 3: Global Construction Machinery Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Table 4: Global Construction Machinery Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 5: Global Construction Machinery Market Revenue Billion Forecast, by Engine Capacity 2020 & 2034
Table 6: Global Construction Machinery Market Revenue Billion Forecast, by Application 2020 & 2034
Table 7: Global Construction Machinery Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Construction Machinery Market Revenue Billion Forecast, by Product 2020 & 2034
Table 9: North America Construction Machinery Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 10: North America Construction Machinery Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Table 11: North America Construction Machinery Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 12: North America Construction Machinery Market Revenue Billion Forecast, by Engine Capacity 2020 & 2034
Table 13: North America Construction Machinery Market Revenue Billion Forecast, by Application 2020 & 2034
Table 14: North America Construction Machinery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Mexico Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Europe Construction Machinery Market Revenue Billion Forecast, by Product 2020 & 2034
Table 19: Europe Construction Machinery Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 20: Europe Construction Machinery Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Table 21: Europe Construction Machinery Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 22: Europe Construction Machinery Market Revenue Billion Forecast, by Engine Capacity 2020 & 2034
Table 23: Europe Construction Machinery Market Revenue Billion Forecast, by Application 2020 & 2034
Table 24: Europe Construction Machinery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Germany Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: UK Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: France Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Italy Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Asia Pacific Construction Machinery Market Revenue Billion Forecast, by Product 2020 & 2034
Table 30: Asia Pacific Construction Machinery Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 31: Asia Pacific Construction Machinery Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Table 32: Asia Pacific Construction Machinery Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 33: Asia Pacific Construction Machinery Market Revenue Billion Forecast, by Engine Capacity 2020 & 2034
Table 34: Asia Pacific Construction Machinery Market Revenue Billion Forecast, by Application 2020 & 2034
Table 35: Asia Pacific Construction Machinery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 36: China Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: India Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Japan Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: South Korea Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: ASEAN Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: South America Construction Machinery Market Revenue Billion Forecast, by Product 2020 & 2034
Table 42: South America Construction Machinery Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 43: South America Construction Machinery Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Table 44: South America Construction Machinery Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 45: South America Construction Machinery Market Revenue Billion Forecast, by Engine Capacity 2020 & 2034
Table 46: South America Construction Machinery Market Revenue Billion Forecast, by Application 2020 & 2034
Table 47: South America Construction Machinery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 48: Brazil Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 49: Argentina Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Chile Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Peru Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Middle East & Africa Construction Machinery Market Revenue Billion Forecast, by Product 2020 & 2034
Table 53: Middle East & Africa Construction Machinery Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 54: Middle East & Africa Construction Machinery Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Table 55: Middle East & Africa Construction Machinery Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 56: Middle East & Africa Construction Machinery Market Revenue Billion Forecast, by Engine Capacity 2020 & 2034
Table 57: Middle East & Africa Construction Machinery Market Revenue Billion Forecast, by Application 2020 & 2034
Table 58: Middle East & Africa Construction Machinery Market Revenue Billion Forecast, by Country 2020 & 2034
Table 59: Saudi Arabia Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 60: UAE Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 61: South Africa Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 62: Nigeria Construction Machinery Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the construction machinery market?
The global construction machinery market was valued at **USD 242.2 billion in 2025** and is projected to reach **USD 471.3 billion by 2033**, growing at a CAGR of **8.7%** from 2026 to 2033.
2Which region dominates the construction machinery market?
Asia-Pacific dominates with a **44.9% revenue share in 2025**, driven by China's infrastructure pipeline and India's National Infrastructure Pipeline of **USD 1.4 trillion**. North America and Europe follow with **22.6%** and **18.4%** shares respectively.
3What is the fastest-growing segment in the construction machinery market?
Electric and hybrid construction equipment is the fastest-growing propulsion segment, expanding at a **20.5% CAGR**. Within equipment types, compact/mini excavators are growing at **13.5% CAGR** due to urban densification.
4Who are the key players in the construction machinery market?
Leading players include **Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery, Liebherr-International AG, XCMG, SANY Heavy Industry, CNH Industrial, and Deere & Company**.
5What are the main drivers of the construction machinery market?
Key drivers include government infrastructure stimulus (e.g., **USD 1.2 trillion** U.S. Infrastructure Investment and Jobs Act), urbanization (68% of global population urban by 2050), and critical-mineral mining expansion for the energy transition.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 70–80% of our research through primary interviews with senior executives across the construction machinery value chain, including OEM product managers, dealer network directors, rental fleet operators, EPC procurement heads, and component suppliers.
Interviewed stakeholders include Chief Procurement Officers, Fleet Operations Directors, Product Development Managers, and Infrastructure Project Managers from leading contractors and rental companies.
We engaged with 4–5 specific company types: hydraulic component manufacturers, telematics software providers, electric powertrain integrators, aftermarket parts distributors, and equipment rental platforms.
Primary research was complemented by on-site visits to manufacturing facilities and construction projects in China, India, Germany, and the United States to observe equipment utilization and procurement practices.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Procurement Officer
35%
Fleet Operations Director
30%
Product Development Manager
20%
Infrastructure Project Manager
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hydraulic Component Manufacturers
30%
Telematics Software Providers
20%
Electric Powertrain Integrators
15%
Aftermarket Parts Distributors
20%
Equipment Rental Platforms
15%
Secondary Research & Industry Benchmarking
20–30% of research relied on secondary sources, including official trade statistics from UN Comtrade, World Bank WITS, and OECD.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook were used to validate OEM revenue, merger activity, and capital expenditure trends.
We analyzed 10-K filings, investor presentations, and sustainability reports from leading OEMs to extract granular data on segment performance and electrification roadmaps.
Demand Modeling & Market Estimation
We employed top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up modeling utilized specific quantitative metrics: unit shipments by equipment type (excavators, loaders, cranes), average selling prices by region, fleet replacement cycles (5–7 years for rental fleets), and infrastructure capital expenditure budgets.
Top-down modeling cross-checked aggregate market size against global construction output data from UN Statistics Division and GDP growth forecasts.
Regional demand models were calibrated using country-specific infrastructure pipelines, such as India's National Infrastructure Pipeline and the U.S. Bipartisan Infrastructure Law spending schedules.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-source triangulation and expert validation.
Every report is updated to the date of purchase, ensuring that market estimates reflect the latest quarterly earnings, trade data, and policy announcements.
A three-tier quality check process was applied: (1) internal analyst review, (2) peer benchmarking against historical forecasts, and (3) external validation with select primary interview participants.
Discrepancies exceeding 5% between top-down and bottom-up estimates were investigated and reconciled before finalization.
Related Reports
Property And Casualty Reinsurance Market valued at USD 398.3 Billion in 2024, projected to reach USD 1,245.46 Billion by 2035 at a 10.92% CAGR.
Nov 2026|245 pages
$2900.00
IP valuation market valued at $14.16 Billion in 2026, reaching $30.75 Billion by 2034 at a 10.18% CAGR, driven by M&A and IP-backed finance.
Nov 2026|216 pages
$2900.00
The global residential real estate market is valued at USD 11.6 trillion in 2026 and is projected to reach USD 15.53 trillion by 2031, growing at a 6.05% CAGR.
Nov 2026|243 pages
$2900.00
Post-construction cleaning demand patterns: a $24.6B niche growing at 7.4% CAGR to 2035, driven by handover cycles, green certification and labor shifts.
Nov 2026|241 pages
$2900.00
India construction equipment market at $9.98B in 2027 to reach $14.46B by 2032, CAGR 7.70%. Earthmoving leads; electric/hybrid fastest-growing.