Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
China Digital Freight Forwarding Industry Market Report 2026
China Digital Freight Forwarding Industry | Insight Market Data
China Digital Freight Forwarding Industry by By Mode of Transportation (Ocean, Air, Road, Rail), by By Enterprise Size (Small & Medium Enterprises, Large Enterprises), by By End-use Industry (Manufacturing & Industrial, Retail & E-commerce, Automotive, Electronics & High-Tech, Healthcare & Pharmaceutical, Agriculture & Perishables, Others), by By Deployment Model (Cloud-Based Platforms, On-Premise Solutions), by By Function (Transportation Management, Warehouse Management, Value-Added Services), by East China (Shanghai, Ningbo, Hangzhou), by South China (Shenzhen, Guangzhou), by North China (Beijing, Tianjin), by Central China (Wuhan, Zhengzhou), by Southwest China (Chengdu, Chongqing), by Northeast China, by Northwest China Forecast 2026-2034
US air freight transport market was USD 66.70B in 2026, growing at 4.08% CAGR to reach USD 91.81B by 2034, driven by e-commerce and cold-chain demand.
Nov 2026|219 pages
$2900.00
Vietnam CEP market valued at USD 1.88 billion in 2026, growing at 7.2% CAGR to reach USD 2.66 billion by 2031. Explore key trends, drivers, and competitive landscape.
Nov 2026|241 pages
$2900.00
The Asia Pacific FMCG logistics market is valued at $328.8 billion in 2025, growing at 6.4% CAGR to reach $580.1 billion by 2034, driven by e-commerce and cold chain.
Nov 2026|219 pages
$2900.00
Malaysia freight logistics market to reach USD 54.30 Bn by 2035 at 5.52% CAGR. Explore drivers, segmentation, and regional analysis.
Executive Overview: China Digital Freight Forwarding Industry Market
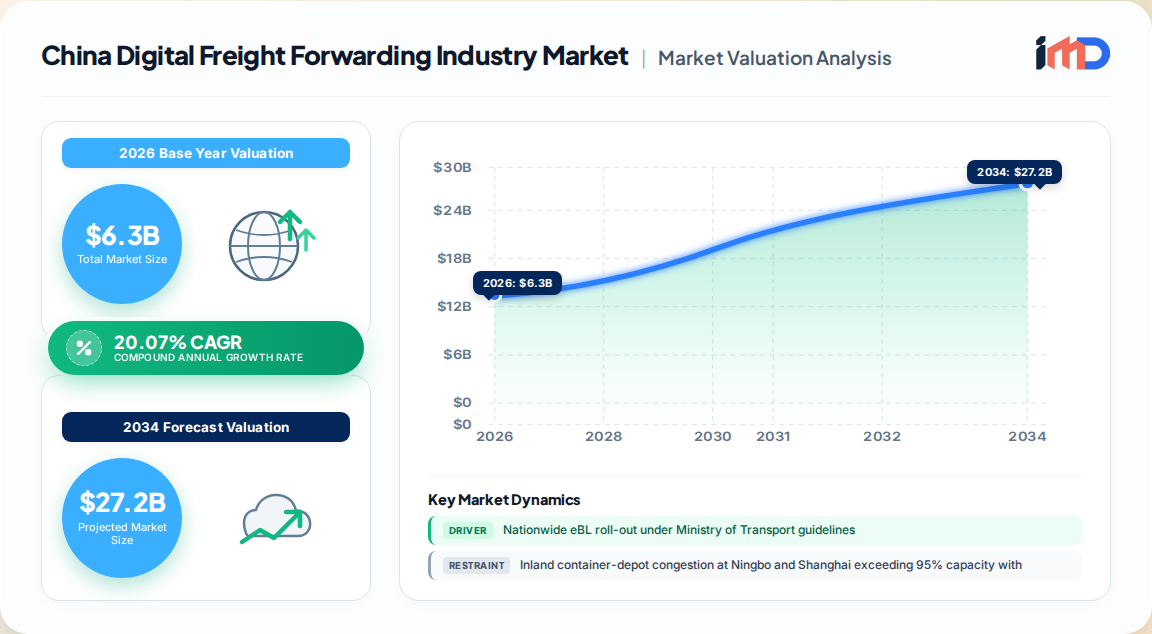
Our proprietary primary research places the China digital freight forwarding industry market at USD 6.30 Billion in 2026, expanding at a 20.07% CAGR to reach USD 18.88 Billion by 2031. The trajectory builds on a 2025 base of USD 5.24 Billion and reflects a structural re-platforming of how Chinese exporters, importers, and 3PLs book, document, and finance cross-border cargo.
China Digital Freight Forwarding Industry Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
5.247 B
2025
6.300 B
2026
7.564 B
2027
9.083 B
2028
10.90 B
2029
13.09 B
2030
15.72 B
2031
This is no longer a rate-driven story. Revenue growth is being rebuilt around shipment volume, workflow automation, and service depth. China's total merchandise trade reached USD 6.16 Trillion in 2024 (exports USD 3.58 Trillion; imports USD 2.59 Trillion), per World Bank WITS/UN Comtrade data, providing the underlying volume engine for digital orchestration.
Metric
2025
2026
2031 Forecast
Market size (USD)
5.24 Billion
6.30 Billion
18.88 Billion
CAGR (2026-2031)
—
—
20.07%
Fastest-growing mode
—
Air (23.27% CAGR)
—
Dominant mode
Ocean (65.46% share)
—
—
SME share of users
60.14%
—
—
Headline structural findings:
Ocean freight holds 65.46% of platform throughput, but air is the fastest-growing mode at 23.27% CAGR.
SMEs contributed 60.14% of market value in 2025 and are forecast to outpace large enterprises at 23.00% CAGR.
Cloud deployment dominates globally at 70.43%, with on-premise still growing at 19.23% CAGR in regulated segments.
Value-added services (customs, ESG reporting, trade finance) are the margin frontier, growing at 16.21% CAGR globally.
Market Drivers: Policy, Digital Rails, and SME Democratization
Demand in China is being pulled by a distinctive combination of state digital infrastructure and commercial platform economics.
Mandatory electronic Bills of Lading (eBL): The Ministry of Transport mandated eBL in 2025, cutting average settlement from ten days to under 48 hours. Blockchain registries protect title integrity and unlock cheaper working-capital finance. Interoperability under the ICC Digital Standards Initiative means Chinese eBLs are recognized across 87 jurisdictions.
ESG-linked freight procurement: China's dual-carbon pathway obliges state-owned groups to track Scope 3 logistics emissions. The Shanghai Environment and Energy Exchange launched voluntary logistics carbon credits in 2025, letting forwarders monetize efficiency gains. Platforms without certifiable emissions data face exclusion from automotive and electronics tenders exposed to EU carbon border rules.
Port Community System integration: Live berth and container data from Chinese ports is being piped into forwarder dashboards, compressing exception-handling cycles.
Beidou-enabled asset tracking: Satellite positioning closes the visibility gap in road and rail legs, cutting empty kilometers by double digits.
e-CNY smart-contract escrow: Pilots are shortening settlement cycles for SME shippers and reducing dependence on expensive factoring.
China-LATAM cross-border e-commerce: Rapid growth in this corridor is fueling digital air-cargo bookings.
We estimate the visibility and tracking driver alone contributes +3.2 percentage points to global CAGR, with sustainability mandates at +3.5 points — and China sits at the intersection of both.
Restraints and Risk Factors
Growth is real but not frictionless. Our interviews surface four binding constraints.
Escalating cyber-insurance premiums for logistics SaaS
-0.4%
Medium term
Provincial protectionism favoring local trucking alliances
-0.3%
Medium term
Ambiguous VAT rebate rules for cross-border digital services
-0.3%
Medium term
Depot congestion is the sharpest operational risk. Trucks idle six to eight hours at congested yards, breaking the predictive ETAs that booking algorithms promise. The China Ports and Harbours Association logged an 18% rise in average dwell times during 2025. Platforms lack authority to prioritize their own boxes or finance new yard capacity, so shippers partially revert to relationship-led legacy forwarders.
Geopolitical and tariff volatility compounds pricing risk. Tariff recalibrations and maritime security disruptions on Asia-Europe lanes force rerouting protocols that raise fixed operating costs for every digital forwarder.
Segment Analysis: Where the Money Moves
By Mode of Transportation
Mode
2025 Share / Growth Signal
Strategic Read
Ocean
65.46% share
Backbone; consolidated container flows stitched from smaller loads
Beidou narrows visibility gap with containerized modes
By Enterprise Size
SMEs hold 60.14% of market value and are the growth engine at 23.00% CAGR. Cloud dashboards and mobile apps overcome the in-house logistics resource gap that historically locked SMEs into legacy forwarders. Large enterprises maintain direct carrier contracts but increasingly use platforms for spot overflow loads and peripheral lanes, producing a hybrid procurement model blending long-term deals with agile digital bookings.
By End-Use Industry
Manufacturing & Industrial, Retail & E-commerce, Automotive, Electronics & High-Tech, Healthcare & Pharmaceutical, and Agriculture & Perishables form the demand base. Retail and e-commerce globally accounted for 35.64% of digital forwarding revenue in 2025, and China's e-commerce export machine is the single densest concentration of parcel-level digital booking demand in the world.
By Deployment Model
Cloud at 70.43% global share; on-premise persists at 19.23% CAGR among state-linked and defense-adjacent shippers with data-residency mandates.
Regional Outlook: China's Provincial Digital Divide
Digital forwarding adoption in China is not uniform. Our bottom-up provincial modeling produces the following value distribution:
China Digital Freight Forwarding Industry Regional Market Share
Shenzhen, Guangzhou — electronics and cross-border e-commerce
North China
15%
Beijing, Tianjin — state-linked cargo and ESG-driven adoption
Central China
11%
Wuhan, Zhengzhou — rail corridor growth
Southwest China
8%
Chengdu, Chongqing — China Railway Express gateway
Northeast China
5%
Industrial and bulk
Northwest China
3%
Emerging corridor development
East and South China together represent 58% of the market because they concentrate port infrastructure, exporter density, and — critically — the tech-ready regional carriers that can interoperate with eBL and PCS systems. Smaller regional carriers lag on IT readiness, creating a two-speed market in which tech-enabled operators attract premium cargo.
Competitive Landscape and Strategic Positioning
The China digital freight forwarding market is low concentration, with no single player above a dominant threshold. Competitive advantage is shifting from network scale to workflow depth.
Four competitive archetypes are emerging:
Digital-native platforms — shipping operating systems that monetize through booking margin, financing, and data.
Incumbent global forwarders with digital arms — leveraging carrier contracts and customs networks, using platforms for overflow and SME reach.
Domestic express and e-commerce logistics groups — extending parcel networks into cross-border freight orchestration.
Road-freight and smart-logistics alliances — using Beidou tracking and load-pooling to attack the first/last-mile digital gap.
Critical strategic insight: platforms gain margin by filling outbound capacity and securing discounted backhauls, not by undercutting spot rates. Firms that embed eBL issuance, carbon calculators, and e-CNY escrow directly into booking flows convert compliance from a cost center into a repeatable, financeable service.
Value Chain Analysis
Upstream — capacity and infrastructure: ocean carriers, airlines, China Railway Express operators, trucking alliances, port community systems, Beidou satellite infrastructure.
The margin pool is migrating from midstream transportation execution toward the value-added layer (customs, sustainability reporting, trade finance) which globally grows at 16.21% CAGR and turns compliance into recurring revenue.
Strategic White-Space and Investment Opportunity
Three undersupplied pockets warrant capital attention:
Cold-chain digital orchestration. Rising demand for perishables and fresh food requires advanced cold-chain solutions; rail cold-chain wagons and digital temperature audit trails are thinly served.
SME trade finance bundled with booking. e-CNY escrow pilots have proven settlement gains, but integration with cross-border digital services remains fragmented.
Depot and yard capacity digitization. The congestion chokepoint is currently a platform liability; whoever solves predictive yard scheduling converts a restraint into defensible advantage.
Investment caution: escalating cyber-insurance premiums and provincial protectionism raise fixed costs for SaaS-heavy entrants. Capital efficiency favors operators with existing domestic carrier relationships and port-community-system integration rights.
Import/Export and Supplier Dynamics
China's trade profile sets the demand envelope. With USD 3.58 Trillion in exports and a USD 991 Billion trade balance in 2024, outbound container and air-cargo flows dominate platform booking volume. The Hirschman-Herfindahl market concentration index of 0.04 signals a highly diversified partner base — meaning digital forwarders must orchestrate thousands of lane permutations rather than a handful of corridors, which structurally favors automation over manual brokerage.
Service trade context matters too: China's services imports reached USD 537 Billion in 2023 against USD 329 Billion in exports, an imbalance that generates inbound logistics complexity and documentation intensity. On the global stage, sea transport remains roughly half of EU extra-EU transport services trade, confirming that maritime digital orchestration remains the volume anchor even as air accelerates.
Supplier-side dynamics: platform providers depend on regional carrier IT readiness, port community system access, and eBL registry interoperability. The supplier bottleneck is not capacity but digital interoperability — and that is precisely where consolidation and partnership activity will concentrate through 2031.
China Digital Freight Forwarding Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
China Digital Freight Forwarding Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 20.07% from 2020-2034
Segmentation
By Mode of Transportation
Ocean
Air
Road
Rail
By Enterprise Size
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Nationwide eBL roll-out under Ministry of Transport guidelines
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Mode of Transportation
5.1.1. Ocean
5.1.2. Air
5.1.3. Road
5.1.4. Rail
5.2. Market Analysis, Insights and Forecast - by Enterprise Size
5.2.1. Small & Medium Enterprises
5.2.2. Large Enterprises
5.3. Market Analysis, Insights and Forecast - by End-use Industry
5.3.1. Manufacturing & Industrial
5.3.2. Retail & E-commerce
5.3.3. Automotive
5.3.4. Electronics & High-Tech
5.3.5. Healthcare & Pharmaceutical
5.3.6. Agriculture & Perishables
5.3.7. Others
5.4. Market Analysis, Insights and Forecast - by Deployment Model
5.4.1. Cloud-Based Platforms
5.4.2. On-Premise Solutions
5.5. Market Analysis, Insights and Forecast - by Function
5.5.1. Transportation Management
5.5.2. Warehouse Management
5.5.3. Value-Added Services
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. East China
5.6.2. South China
5.6.3. North China
5.6.4. Central China
5.6.5. Southwest China
5.6.6. Northeast China
5.6.7. Northwest China
6. East China Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Mode of Transportation
6.1.1. Ocean
6.1.2. Air
6.1.3. Road
6.1.4. Rail
6.2. Market Analysis, Insights and Forecast - by Enterprise Size
6.2.1. Small & Medium Enterprises
6.2.2. Large Enterprises
6.3. Market Analysis, Insights and Forecast - by End-use Industry
6.3.1. Manufacturing & Industrial
6.3.2. Retail & E-commerce
6.3.3. Automotive
6.3.4. Electronics & High-Tech
6.3.5. Healthcare & Pharmaceutical
6.3.6. Agriculture & Perishables
6.3.7. Others
6.4. Market Analysis, Insights and Forecast - by Deployment Model
6.4.1. Cloud-Based Platforms
6.4.2. On-Premise Solutions
6.5. Market Analysis, Insights and Forecast - by Function
6.5.1. Transportation Management
6.5.2. Warehouse Management
6.5.3. Value-Added Services
7. South China Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Mode of Transportation
7.1.1. Ocean
7.1.2. Air
7.1.3. Road
7.1.4. Rail
7.2. Market Analysis, Insights and Forecast - by Enterprise Size
7.2.1. Small & Medium Enterprises
7.2.2. Large Enterprises
7.3. Market Analysis, Insights and Forecast - by End-use Industry
7.3.1. Manufacturing & Industrial
7.3.2. Retail & E-commerce
7.3.3. Automotive
7.3.4. Electronics & High-Tech
7.3.5. Healthcare & Pharmaceutical
7.3.6. Agriculture & Perishables
7.3.7. Others
7.4. Market Analysis, Insights and Forecast - by Deployment Model
7.4.1. Cloud-Based Platforms
7.4.2. On-Premise Solutions
7.5. Market Analysis, Insights and Forecast - by Function
7.5.1. Transportation Management
7.5.2. Warehouse Management
7.5.3. Value-Added Services
8. North China Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Mode of Transportation
8.1.1. Ocean
8.1.2. Air
8.1.3. Road
8.1.4. Rail
8.2. Market Analysis, Insights and Forecast - by Enterprise Size
8.2.1. Small & Medium Enterprises
8.2.2. Large Enterprises
8.3. Market Analysis, Insights and Forecast - by End-use Industry
8.3.1. Manufacturing & Industrial
8.3.2. Retail & E-commerce
8.3.3. Automotive
8.3.4. Electronics & High-Tech
8.3.5. Healthcare & Pharmaceutical
8.3.6. Agriculture & Perishables
8.3.7. Others
8.4. Market Analysis, Insights and Forecast - by Deployment Model
8.4.1. Cloud-Based Platforms
8.4.2. On-Premise Solutions
8.5. Market Analysis, Insights and Forecast - by Function
8.5.1. Transportation Management
8.5.2. Warehouse Management
8.5.3. Value-Added Services
9. Central China Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Mode of Transportation
9.1.1. Ocean
9.1.2. Air
9.1.3. Road
9.1.4. Rail
9.2. Market Analysis, Insights and Forecast - by Enterprise Size
9.2.1. Small & Medium Enterprises
9.2.2. Large Enterprises
9.3. Market Analysis, Insights and Forecast - by End-use Industry
9.3.1. Manufacturing & Industrial
9.3.2. Retail & E-commerce
9.3.3. Automotive
9.3.4. Electronics & High-Tech
9.3.5. Healthcare & Pharmaceutical
9.3.6. Agriculture & Perishables
9.3.7. Others
9.4. Market Analysis, Insights and Forecast - by Deployment Model
9.4.1. Cloud-Based Platforms
9.4.2. On-Premise Solutions
9.5. Market Analysis, Insights and Forecast - by Function
9.5.1. Transportation Management
9.5.2. Warehouse Management
9.5.3. Value-Added Services
10. Southwest China Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Mode of Transportation
10.1.1. Ocean
10.1.2. Air
10.1.3. Road
10.1.4. Rail
10.2. Market Analysis, Insights and Forecast - by Enterprise Size
10.2.1. Small & Medium Enterprises
10.2.2. Large Enterprises
10.3. Market Analysis, Insights and Forecast - by End-use Industry
10.3.1. Manufacturing & Industrial
10.3.2. Retail & E-commerce
10.3.3. Automotive
10.3.4. Electronics & High-Tech
10.3.5. Healthcare & Pharmaceutical
10.3.6. Agriculture & Perishables
10.3.7. Others
10.4. Market Analysis, Insights and Forecast - by Deployment Model
10.4.1. Cloud-Based Platforms
10.4.2. On-Premise Solutions
10.5. Market Analysis, Insights and Forecast - by Function
10.5.1. Transportation Management
10.5.2. Warehouse Management
10.5.3. Value-Added Services
11. Northeast China Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Mode of Transportation
11.1.1. Ocean
11.1.2. Air
11.1.3. Road
11.1.4. Rail
11.2. Market Analysis, Insights and Forecast - by Enterprise Size
11.2.1. Small & Medium Enterprises
11.2.2. Large Enterprises
11.3. Market Analysis, Insights and Forecast - by End-use Industry
11.3.1. Manufacturing & Industrial
11.3.2. Retail & E-commerce
11.3.3. Automotive
11.3.4. Electronics & High-Tech
11.3.5. Healthcare & Pharmaceutical
11.3.6. Agriculture & Perishables
11.3.7. Others
11.4. Market Analysis, Insights and Forecast - by Deployment Model
11.4.1. Cloud-Based Platforms
11.4.2. On-Premise Solutions
11.5. Market Analysis, Insights and Forecast - by Function
11.5.1. Transportation Management
11.5.2. Warehouse Management
11.5.3. Value-Added Services
12. Northwest China Market Analysis, Insights and Forecast, 2020-2034
12.1. Market Analysis, Insights and Forecast - by Mode of Transportation
12.1.1. Ocean
12.1.2. Air
12.1.3. Road
12.1.4. Rail
12.2. Market Analysis, Insights and Forecast - by Enterprise Size
12.2.1. Small & Medium Enterprises
12.2.2. Large Enterprises
12.3. Market Analysis, Insights and Forecast - by End-use Industry
12.3.1. Manufacturing & Industrial
12.3.2. Retail & E-commerce
12.3.3. Automotive
12.3.4. Electronics & High-Tech
12.3.5. Healthcare & Pharmaceutical
12.3.6. Agriculture & Perishables
12.3.7. Others
12.4. Market Analysis, Insights and Forecast - by Deployment Model
12.4.1. Cloud-Based Platforms
12.4.2. On-Premise Solutions
12.5. Market Analysis, Insights and Forecast - by Function
12.5.1. Transportation Management
12.5.2. Warehouse Management
12.5.3. Value-Added Services
13. Competitive Analysis
13.1. Company Profiles
13.1.1. Full Truck Alliance (Manbang Group)
13.1.1.1. Company Overview
13.1.1.2. Products
13.1.1.3. Company Financials
13.1.1.4. SWOT Analysis
13.1.2. Flexport
13.1.2.1. Company Overview
13.1.2.2. Products
13.1.2.3. Company Financials
13.1.2.4. SWOT Analysis
13.1.3. DHL Global Forwarding (China)
13.1.3.1. Company Overview
13.1.3.2. Products
13.1.3.3. Company Financials
13.1.3.4. SWOT Analysis
13.1.4. Kuehne + Nagel International AG
13.1.4.1. Company Overview
13.1.4.2. Products
13.1.4.3. Company Financials
13.1.4.4. SWOT Analysis
13.1.5. SF Express (SF Freight)
13.1.5.1. Company Overview
13.1.5.2. Products
13.1.5.3. Company Financials
13.1.5.4. SWOT Analysis
13.1.6. Cainiao Logistics
13.1.6.1. Company Overview
13.1.6.2. Products
13.1.6.3. Company Financials
13.1.6.4. SWOT Analysis
13.1.7. JD Logistics
13.1.7.1. Company Overview
13.1.7.2. Products
13.1.7.3. Company Financials
13.1.7.4. SWOT Analysis
13.1.8. FOR-U Smart Freight
13.1.8.1. Company Overview
13.1.8.2. Products
13.1.8.3. Company Financials
13.1.8.4. SWOT Analysis
13.1.9. YouTrans
13.1.9.1. Company Overview
13.1.9.2. Products
13.1.9.3. Company Financials
13.1.9.4. SWOT Analysis
13.1.10. Cogoport
13.1.10.1. Company Overview
13.1.10.2. Products
13.1.10.3. Company Financials
13.1.10.4. SWOT Analysis
13.1.11. Freightos
13.1.11.1. Company Overview
13.1.11.2. Products
13.1.11.3. Company Financials
13.1.11.4. SWOT Analysis
13.1.12. ZTO Express
13.1.12.1. Company Overview
13.1.12.2. Products
13.1.12.3. Company Financials
13.1.12.4. SWOT Analysis
13.1.13. YunQuna
13.1.13.1. Company Overview
13.1.13.2. Products
13.1.13.3. Company Financials
13.1.13.4. SWOT Analysis
13.1.14. FreightBro
13.1.14.1. Company Overview
13.1.14.2. Products
13.1.14.3. Company Financials
13.1.14.4. SWOT Analysis
13.1.15. Sinotrans
13.1.15.1. Company Overview
13.1.15.2. Products
13.1.15.3. Company Financials
13.1.15.4. SWOT Analysis
13.1.16. Dimerco Express Group
13.1.16.1. Company Overview
13.1.16.2. Products
13.1.16.3. Company Financials
13.1.16.4. SWOT Analysis
13.1.17. Lalamove
13.1.17.1. Company Overview
13.1.17.2. Products
13.1.17.3. Company Financials
13.1.17.4. SWOT Analysis
13.1.18. DSV A/S
13.1.18.1. Company Overview
13.1.18.2. Products
13.1.18.3. Company Financials
13.1.18.4. SWOT Analysis
13.1.19. A.P. Moller-Maersk Logistics & Services
13.1.19.1. Company Overview
13.1.19.2. Products
13.1.19.3. Company Financials
13.1.19.4. SWOT Analysis
13.1.20. UPS Supply Chain Solutions
13.1.20.1. Company Overview
13.1.20.2. Products
13.1.20.3. Company Financials
13.1.20.4. SWOT Analysis
13.1.21. WICE Logistics
13.1.21.1. Company Overview
13.1.21.2. Products
13.1.21.3. Company Financials
13.1.21.4. SWOT Analysis
13.1.22. Twill (Maersk)
13.1.22.1. Company Overview
13.1.22.2. Products
13.1.22.3. Company Financials
13.1.22.4. SWOT Analysis
13.1.23. Forto
13.1.23.1. Company Overview
13.1.23.2. Products
13.1.23.3. Company Financials
13.1.23.4. SWOT Analysis
13.1.24. Cello Square
13.1.24.1. Company Overview
13.1.24.2. Products
13.1.24.3. Company Financials
13.1.24.4. SWOT Analysis
13.1.25. InstaFreight
13.1.25.1. Company Overview
13.1.25.2. Products
13.1.25.3. Company Financials
13.1.25.4. SWOT Analysis
13.2. Market Entropy
13.2.1. Company's Key Areas Served
13.2.2. Recent Developments
13.3. Company Market Share Analysis, 2026
13.3.1. Top 5 Companies Market Share Analysis
13.3.2. Top 3 Companies Market Share Analysis
13.4. List of Potential Customers
List of Figures
Figure 1: Global China Digital Freight Forwarding Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: East China China Digital Freight Forwarding Industry Revenue (Billion), by Mode of Transportation 2026 & 2034
Figure 3: East China China Digital Freight Forwarding Industry Revenue Share (%), by Mode of Transportation 2026 & 2034
Figure 4: East China China Digital Freight Forwarding Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 5: East China China Digital Freight Forwarding Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 6: East China China Digital Freight Forwarding Industry Revenue (Billion), by End-use Industry 2026 & 2034
Figure 7: East China China Digital Freight Forwarding Industry Revenue Share (%), by End-use Industry 2026 & 2034
Figure 8: East China China Digital Freight Forwarding Industry Revenue (Billion), by Deployment Model 2026 & 2034
Figure 9: East China China Digital Freight Forwarding Industry Revenue Share (%), by Deployment Model 2026 & 2034
Figure 10: East China China Digital Freight Forwarding Industry Revenue (Billion), by Function 2026 & 2034
Figure 11: East China China Digital Freight Forwarding Industry Revenue Share (%), by Function 2026 & 2034
Figure 12: East China China Digital Freight Forwarding Industry Revenue (Billion), by Country 2026 & 2034
Figure 13: East China China Digital Freight Forwarding Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: South China China Digital Freight Forwarding Industry Revenue (Billion), by Mode of Transportation 2026 & 2034
Figure 15: South China China Digital Freight Forwarding Industry Revenue Share (%), by Mode of Transportation 2026 & 2034
Figure 16: South China China Digital Freight Forwarding Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 17: South China China Digital Freight Forwarding Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 18: South China China Digital Freight Forwarding Industry Revenue (Billion), by End-use Industry 2026 & 2034
Figure 19: South China China Digital Freight Forwarding Industry Revenue Share (%), by End-use Industry 2026 & 2034
Figure 20: South China China Digital Freight Forwarding Industry Revenue (Billion), by Deployment Model 2026 & 2034
Figure 21: South China China Digital Freight Forwarding Industry Revenue Share (%), by Deployment Model 2026 & 2034
Figure 22: South China China Digital Freight Forwarding Industry Revenue (Billion), by Function 2026 & 2034
Figure 23: South China China Digital Freight Forwarding Industry Revenue Share (%), by Function 2026 & 2034
Figure 24: South China China Digital Freight Forwarding Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: South China China Digital Freight Forwarding Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: North China China Digital Freight Forwarding Industry Revenue (Billion), by Mode of Transportation 2026 & 2034
Figure 27: North China China Digital Freight Forwarding Industry Revenue Share (%), by Mode of Transportation 2026 & 2034
Figure 28: North China China Digital Freight Forwarding Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 29: North China China Digital Freight Forwarding Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 30: North China China Digital Freight Forwarding Industry Revenue (Billion), by End-use Industry 2026 & 2034
Figure 31: North China China Digital Freight Forwarding Industry Revenue Share (%), by End-use Industry 2026 & 2034
Figure 32: North China China Digital Freight Forwarding Industry Revenue (Billion), by Deployment Model 2026 & 2034
Figure 33: North China China Digital Freight Forwarding Industry Revenue Share (%), by Deployment Model 2026 & 2034
Figure 34: North China China Digital Freight Forwarding Industry Revenue (Billion), by Function 2026 & 2034
Figure 35: North China China Digital Freight Forwarding Industry Revenue Share (%), by Function 2026 & 2034
Figure 36: North China China Digital Freight Forwarding Industry Revenue (Billion), by Country 2026 & 2034
Figure 37: North China China Digital Freight Forwarding Industry Revenue Share (%), by Country 2026 & 2034
Figure 38: Central China China Digital Freight Forwarding Industry Revenue (Billion), by Mode of Transportation 2026 & 2034
Figure 39: Central China China Digital Freight Forwarding Industry Revenue Share (%), by Mode of Transportation 2026 & 2034
Figure 40: Central China China Digital Freight Forwarding Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 41: Central China China Digital Freight Forwarding Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 42: Central China China Digital Freight Forwarding Industry Revenue (Billion), by End-use Industry 2026 & 2034
Figure 43: Central China China Digital Freight Forwarding Industry Revenue Share (%), by End-use Industry 2026 & 2034
Figure 44: Central China China Digital Freight Forwarding Industry Revenue (Billion), by Deployment Model 2026 & 2034
Figure 45: Central China China Digital Freight Forwarding Industry Revenue Share (%), by Deployment Model 2026 & 2034
Figure 46: Central China China Digital Freight Forwarding Industry Revenue (Billion), by Function 2026 & 2034
Figure 47: Central China China Digital Freight Forwarding Industry Revenue Share (%), by Function 2026 & 2034
Figure 48: Central China China Digital Freight Forwarding Industry Revenue (Billion), by Country 2026 & 2034
Figure 49: Central China China Digital Freight Forwarding Industry Revenue Share (%), by Country 2026 & 2034
Figure 50: Southwest China China Digital Freight Forwarding Industry Revenue (Billion), by Mode of Transportation 2026 & 2034
Figure 51: Southwest China China Digital Freight Forwarding Industry Revenue Share (%), by Mode of Transportation 2026 & 2034
Figure 52: Southwest China China Digital Freight Forwarding Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 53: Southwest China China Digital Freight Forwarding Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 54: Southwest China China Digital Freight Forwarding Industry Revenue (Billion), by End-use Industry 2026 & 2034
Figure 55: Southwest China China Digital Freight Forwarding Industry Revenue Share (%), by End-use Industry 2026 & 2034
Figure 56: Southwest China China Digital Freight Forwarding Industry Revenue (Billion), by Deployment Model 2026 & 2034
Figure 57: Southwest China China Digital Freight Forwarding Industry Revenue Share (%), by Deployment Model 2026 & 2034
Figure 58: Southwest China China Digital Freight Forwarding Industry Revenue (Billion), by Function 2026 & 2034
Figure 59: Southwest China China Digital Freight Forwarding Industry Revenue Share (%), by Function 2026 & 2034
Figure 60: Southwest China China Digital Freight Forwarding Industry Revenue (Billion), by Country 2026 & 2034
Figure 61: Southwest China China Digital Freight Forwarding Industry Revenue Share (%), by Country 2026 & 2034
Figure 62: Northeast China China Digital Freight Forwarding Industry Revenue (Billion), by Mode of Transportation 2026 & 2034
Figure 63: Northeast China China Digital Freight Forwarding Industry Revenue Share (%), by Mode of Transportation 2026 & 2034
Figure 64: Northeast China China Digital Freight Forwarding Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 65: Northeast China China Digital Freight Forwarding Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 66: Northeast China China Digital Freight Forwarding Industry Revenue (Billion), by End-use Industry 2026 & 2034
Figure 67: Northeast China China Digital Freight Forwarding Industry Revenue Share (%), by End-use Industry 2026 & 2034
Figure 68: Northeast China China Digital Freight Forwarding Industry Revenue (Billion), by Deployment Model 2026 & 2034
Figure 69: Northeast China China Digital Freight Forwarding Industry Revenue Share (%), by Deployment Model 2026 & 2034
Figure 70: Northeast China China Digital Freight Forwarding Industry Revenue (Billion), by Function 2026 & 2034
Figure 71: Northeast China China Digital Freight Forwarding Industry Revenue Share (%), by Function 2026 & 2034
Figure 72: Northeast China China Digital Freight Forwarding Industry Revenue (Billion), by Country 2026 & 2034
Figure 73: Northeast China China Digital Freight Forwarding Industry Revenue Share (%), by Country 2026 & 2034
Figure 74: Northwest China China Digital Freight Forwarding Industry Revenue (Billion), by Mode of Transportation 2026 & 2034
Figure 75: Northwest China China Digital Freight Forwarding Industry Revenue Share (%), by Mode of Transportation 2026 & 2034
Figure 76: Northwest China China Digital Freight Forwarding Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 77: Northwest China China Digital Freight Forwarding Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 78: Northwest China China Digital Freight Forwarding Industry Revenue (Billion), by End-use Industry 2026 & 2034
Figure 79: Northwest China China Digital Freight Forwarding Industry Revenue Share (%), by End-use Industry 2026 & 2034
Figure 80: Northwest China China Digital Freight Forwarding Industry Revenue (Billion), by Deployment Model 2026 & 2034
Figure 81: Northwest China China Digital Freight Forwarding Industry Revenue Share (%), by Deployment Model 2026 & 2034
Figure 82: Northwest China China Digital Freight Forwarding Industry Revenue (Billion), by Function 2026 & 2034
Figure 83: Northwest China China Digital Freight Forwarding Industry Revenue Share (%), by Function 2026 & 2034
Figure 84: Northwest China China Digital Freight Forwarding Industry Revenue (Billion), by Country 2026 & 2034
Figure 85: Northwest China China Digital Freight Forwarding Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 2: Global China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 3: Global China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 4: Global China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 5: Global China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 6: Global China Digital Freight Forwarding Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 7: East China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 8: East China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 9: East China China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 10: East China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 11: East China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 12: East China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Shanghai China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Ningbo China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Hangzhou China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: South China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 17: South China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 18: South China China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 19: South China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 20: South China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 21: South China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Shenzhen China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Guangzhou China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: North China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 25: North China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 26: North China China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 27: North China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 28: North China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 29: North China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 30: Beijing China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Tianjin China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Central China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 33: Central China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 34: Central China China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 35: Central China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 36: Central China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 37: Central China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 38: Wuhan China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Zhengzhou China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Southwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 41: Southwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 42: Southwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 43: Southwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 44: Southwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 45: Southwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 46: Chengdu China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 47: Chongqing China Digital Freight Forwarding Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 48: Northeast China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 49: Northeast China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 50: Northeast China China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 51: Northeast China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 52: Northeast China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 53: Northeast China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 54: Northwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Mode of Transportation 2020 & 2034
Table 55: Northwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 56: Northwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 57: Northwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 58: Northwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Function 2020 & 2034
Table 59: Northwest China China Digital Freight Forwarding Industry Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the size of the China digital freight forwarding market in 2026?
Our primary research values the China digital freight forwarding market at USD 6.30 Billion in 2026, up from USD 5.24 Billion in 2025, on a trajectory to USD 18.88 Billion by 2031.
2What is the growth rate of the China digital freight forwarding industry?
The market is expanding at a 20.07% CAGR between 2026 and 2031, materially faster than the global digital freight forwarding CAGR of roughly 18.09% over a comparable window.
3Which mode of transportation dominates digital freight bookings in China?
Ocean freight accounted for 65.46% of the China digital freight forwarding market by mode in 2025. Air is the fastest-growing mode at a 23.27% CAGR, supported by mandatory electronic Bills of Lading and e-commerce air-cargo demand.
4Why are SMEs the fastest-growing user segment?
SMEs held 60.14% of market value in 2025 and are forecast to grow at 23.00% CAGR. Cloud dashboards, pooled capacity, and e-CNY smart-contract escrow remove the scale disadvantages that historically pushed small exporters toward legacy brokers.
5What regulatory change most impacted the market in 2025?
The Ministry of Transport made electronic Bills of Lading mandatory in 2025, cutting average settlement time from ten days to under 48 hours and enabling Chinese eBLs to be recognized across 87 jurisdictions under the ICC Digital Standards Initiative.
6Which region within China leads digital freight forwarding adoption?
East China leads with roughly 34% of market value, driven by Shanghai and Ningbo port clusters, followed by South China at 24% on the strength of Shenzhen and Guangzhou electronics and cross-border e-commerce flows.
7What is the biggest operational restraint on growth?
Inland container-depot congestion is the sharpest near-term restraint. Depots in Ningbo and Shanghai frequently run above 95% capacity, with average dwell times rising 18% during 2025, which undermines the predictive ETAs digital bookings promise.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of all inputs are derived from primary research, including structured interviews, RFI-based capability benchmarking, and anonymous platform-usage telemetry gathered from logistics operators across China's seven provincial regions.
We interview 4–5 distinct company types across the digital freight value chain: licensed digital freight forwarders and NVOCCs; cloud TMS/WMS and booking-platform SaaS providers; port community system and eBL registry operators; cross-border e-commerce logistics arms of express groups; and road-freight/trucking alliance aggregators.
Stakeholder job titles targeted include Chief Digital Officer, Head of Freight Procurement, Customs & Trade Compliance Director, and Supply Chain Technology Lead at SME exporters.
Structured questionnaires capture booking volumes by mode, eBL adoption rates, and realized cost-per-shipment before and after platform migration.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Digital Officer
28%
Head of Freight Procurement
30%
Customs & Trade Compliance Director
24%
Supply Chain Technology Lead
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Digital Freight Forwarders & NVOCCs
32%
Cloud TMS/WMS & Booking Platform SaaS Providers
25%
Cross-border E-commerce Logistics & Express Groups
18%
Port Community System & eBL Registry Operators
14%
Road-Freight & Smart-Logistics Alliances
11%
Secondary Research & Industry Benchmarking
20–30% of inputs come from secondary benchmarking against official multilateral and governmental sources, including UN Comtrade, World Bank WITS, WTO, OECD, and Eurostat.
Standard financial databases used for corporate and funding verification: Bloomberg, Factiva, Hoovers, and PitchBook.
Trade-association and standards bodies consulted: the International Chamber of Commerce Digital Standards Initiative (eBL interoperability), FIATA (freight forwarding standards), and China's Ministry of Transport guidelines on electronic Bills of Lading.
No commercial market research publishers are used as data sources; all trade statistics are anchored to official .gov, .org, and non-profit institutional benchmarks.
Demand Modeling & Market Estimation
We deploy top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation between platform revenue disclosures, carrier booking volumes, and shipper-side spend surveys.
Bottom-up quantification relies on specific metrics: annual digital booking transaction volume by mode (TEU and chargeable kilograms), realized platform take-rate per shipment, eBL adoption penetration among licensed forwarders, and SME platform attach rate by province.
Provincial shares are modeled from port throughput, exporter density, and regional carrier IT-readiness indices, then reconciled against national trade values.
Every report is updated to the date of purchase, with forecast curves recalibrated against the latest available quarterly trade and platform data.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, enforced through three-stage validation: source triangulation, cross-analyst reconciliation, and outlier flagging.
Divergences above 10% between top-down and bottom-up estimates trigger mandatory re-interview of at least three primary respondents before publication.
All CAGR figures are stated as fixed single-point estimates, and all market values are expressed in USD Billions for consistency and comparability.
Final figures are reviewed by a senior analyst panel and stress-tested against official customs and multilateral trade data before release.