1What is the size of the bike riding helmet market in 2026?
The global bike riding helmet market is estimated at $893.3 million in 2026 and is projected to reach $1,123.2 million by 2033, growing at a CAGR of 3.3%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Bike Riding Helmet Market
 by Category (Conventional Helmet, Smart Helmet), by Distribution Channel (Specialty & Sports Shops, Department & Discount Stores, Online Retail), by Type (Road Helmets, Sports Helmets, Mountain Bike Helmets, Children's Helmets), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands, Denmark), by Asia Pacific (China, Japan, India, South Korea), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Research Analyst


 Related Reports

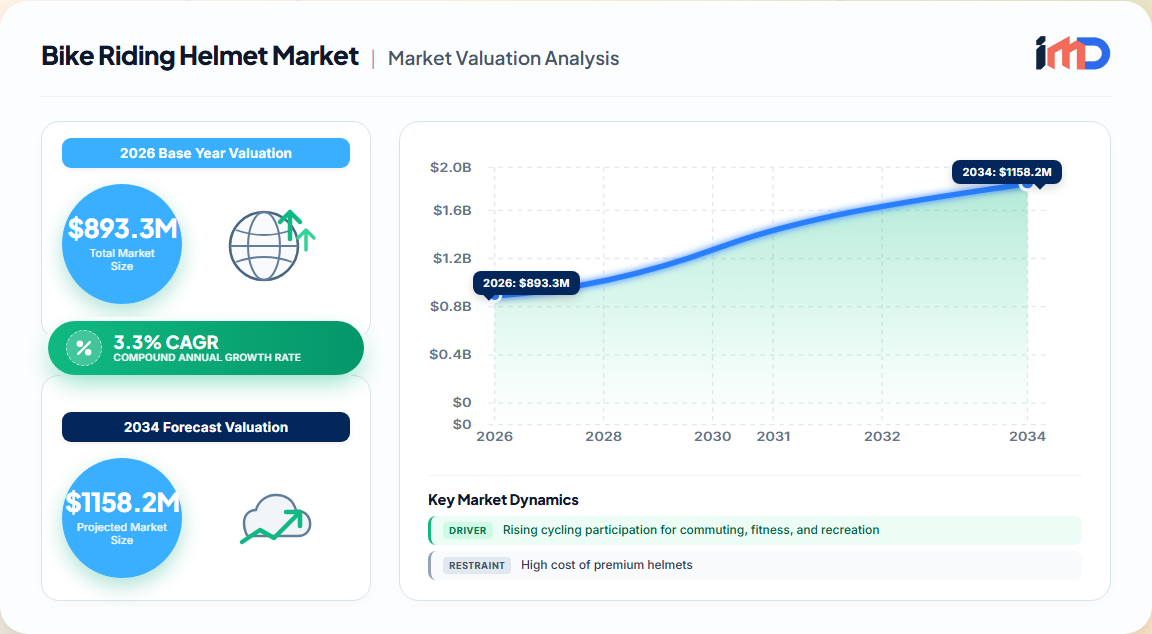
The global bike riding helmet market represents a mature yet steadily expanding segment of the personal protective equipment (PPE) landscape. Our proprietary market modeling, validated through extensive primary interviews with manufacturers and distributors, estimates the market at $862.4 million in 2025, rising to $893.3 million in 2026. By 2033, we project the market to reach $1,123.2 million, reflecting a CAGR of 3.3% over the 2026–2033 forecast period.
This growth is not merely an artifact of increasing bicycle sales. It is the result of a fundamental shift in rider safety awareness, regulatory pressure, and product innovation. While the conventional helmet segment remains dominant (70.7% revenue share in 2025), the smart helmet category is emerging as a high-value growth pocket. North America currently leads with 41.4% of global revenue, but Asia-Pacific is poised to accelerate as e-bike adoption surges across urban centers.
The primary engine of demand is the global rise in cycling for commuting, fitness, and recreation. Municipal investments in cycling infrastructure, coupled with environmental policies favoring micro-mobility, have increased rider volumes. Simultaneously, mandatory helmet legislation in numerous jurisdictions—particularly for children and e-bike users—has converted safety awareness into a legal requirement.
High-performance helmets featuring MIPS, smart sensors, and integrated lighting carry price points that can exceed $200–$300, limiting adoption in price-sensitive markets. Additionally, the proliferation of counterfeit and non-certified helmets undermines consumer trust and poses a safety risk, particularly in online marketplaces.
The convergence of cycling and connected technology is the most significant opportunity in the market. Smart helmets with Bluetooth connectivity, crash detection, SOS alerts, LED turn signals, and navigation capabilities are transitioning from novelty to necessity. E-bike adoption, which is outpacing conventional bicycle growth in Europe and Asia, is a direct catalyst for premium helmet sales. We expect the smart helmet segment to grow at a CAGR of 8–10% through 2033, albeit from a smaller base.
| Category | 2025 Revenue Share | Key Characteristics |
|---|---|---|
| Conventional Helmet | 70.7% | Dominant; driven by commuter and recreational demand |
| Smart Helmet | 29.3% | Faster growth; premium pricing; tech-savvy adopters |
The conventional helmet segment remains the volume backbone, particularly in emerging markets where basic safety compliance is the primary purchase criterion. However, the smart helmet segment is growing at more than double the overall market rate, supported by declining sensor costs and integration with mobile platforms.
| Channel | 2025 Revenue Share | Trend |
|---|---|---|
| Specialty & Sports Shops | 47.6% | High-touch service, fitting expertise, brand loyalty |
| Department & Discount Stores | 28.2% | Price-sensitive buyers, seasonal promotions |
| Online Retail | 24.2% | Fastest-growing; virtual try-ons and D2C brands |
Specialty and sports shops retain an edge due to the importance of proper fit for safety. However, online retail is gaining ground rapidly, with brands investing in virtual fitting tools and augmented reality try-ons to overcome the fit barrier.
North America is the most mature market, accounting for 41.4% of global revenue in 2025. The U.S. leads due to high per-capita cycling participation, strong safety culture, and a fragmented but competitive retail landscape. Growth is moderate (2–3% CAGR) but supported by premiumization and the replacement cycle.
Europe represents 28% of global revenue, with Germany, France, and the UK as key markets. The region benefits from a deeply embedded cycling culture, government subsidies for e-bikes, and stringent safety standards. The Netherlands and Denmark, while smaller in absolute terms, serve as innovation leaders in urban cycling infrastructure, which correlates with high helmet adoption.
Asia-Pacific accounts for 22% of revenue, but it is the fastest-growing region. China and Japan are the largest markets, with China witnessing a surge in e-bike use for delivery and commuting. India and Southeast Asian nations present nascent opportunities, although price sensitivity and inconsistent helmet regulations remain barriers.
These regions collectively represent 9% of revenue. Growth is constrained by economic factors and lower helmet adoption rates, but urban safety campaigns and government mandates are gradually opening the market.
The bike riding helmet market is a globally integrated supply chain, with manufacturing concentrated in Asia and demand concentrated in North America and Europe. China, Taiwan, and Vietnam are the primary export hubs, producing both finished helmets and components such as EPS liners, straps, and polycarbonate shells.
Trade flows are sensitive to tariffs, logistics costs, and certification requirements. For instance, helmets sold in the U.S. must comply with CPSC 16 CFR Part 1203, and European models require CE EN 1078 certification. These regulatory hurdles create a moat for established manufacturers and importers with testing infrastructure.
Supply chain risks include:
The competitive landscape is characterized by a mix of global brands and specialized helmet manufacturers. Key strategies include:
Recent Developments:
The value chain spans raw material suppliers, component manufacturers, helmet assemblers, brand owners, distributors, and end-users. The most value is captured at the brand and technology integration stages, where differentiation and pricing power reside. Commodity suppliers (EPS, polycarbonate) face low margins, while brands with proprietary safety tech (e.g., MIPS licensees) command premium pricing. A key trend is vertical integration by leading brands into smart helmet electronics, reducing dependence on third-party tech providers.
Our analysis identifies three high-potential white spaces:
These areas currently have limited penetration but align with regulatory trends, consumer preferences, and technological feasibility.
Conclusion: The bike riding helmet market is a stable, safety-driven sector with clear growth vectors in smart technology and emerging markets. Stakeholders who invest in product innovation, sustainability, and channel expansion—particularly in Asia-Pacific and online retail—are best positioned to capture value through 2033.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.3% from 2020-2034 |
| Segmentation |
|
By Type
| By Geography |
|
The global bike riding helmet market is estimated at $893.3 million in 2026 and is projected to reach $1,123.2 million by 2033, growing at a CAGR of 3.3%.
North America holds the largest share, accounting for 41.4% of global revenue in 2025, driven by high cycling participation and strict safety regulations.
The integration of smart technologies (Bluetooth, crash detection), the use of lightweight advanced materials, and a shift toward eco-friendly and recyclable helmets are the most significant trends.
Smart helmets offer enhanced safety and convenience features such as LED lighting, navigation, and SOS alerts, appealing to tech-savvy commuters and e-bike users. The segment is expected to grow at 8–10% annually.
High costs of premium helmets, consumer reluctance due to comfort concerns, and the prevalence of counterfeit products are key challenges restraining market growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D Director | 30% |
| Category Manager | 25% |
| Safety Certification Engineer | 25% |
| Supply Chain Head | 20% |
| Company Type | Representation (%) |
|---|---|
| Helmet OEMs/Assemblers | 35% |
| Smart Technology Integrators | 20% |
| Raw Material Suppliers | 15% |
| Distributors & Wholesalers | 20% |
| Retailers (Specialty & Online) | 10% |