Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Barista Milk: A Technology Perspective
Food & Beverage / MARKET REPORT
Barista Milk: A Technology Perspective | Insight Market Data
Barista Milk: A Technology Perspective by Type (Dairy Milk, Non-Dairy Milk, Fortified Milk, Organic Milk), by Formulation (Liquid, Powdered, Concentrated), by Flavor (Plain, Chocolate, Vanilla, Sweetened), by Packaging Type (Cartons, Bottles, Pouches, Tetra Packs), by Source (Oat, Almond, Soy, Coconut, Others), by Distribution Channel (Foodservice, Retail), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, Australia, South Korea, India), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
The coated film for food packaging market is valued at USD 9.8 billion in 2025, growing at 5.4% CAGR amid high-barrier and recyclable coating demand.
Nov 2026|207 pages
$2900.00
South Africa stevia sweetener industry market valued at 18.4 Million in 2025, forecast to grow at 9.8% CAGR as sugar tax and clean-label demand accelerate.
Nov 2026|202 pages
$2900.00
Tea industry market valued at $69.5B in 2025, projected to reach $115.2B by 2033 at 6.5% CAGR. Explore RTD, functional teas, and regional insights.
Nov 2026|213 pages
$2900.00
Cultivated meat cell market to reach USD 21.2B by 2036 at 50.3% CAGR. Explore key trends, drivers, and regional insights shaping the industry.
Executive Overview: The Technology-Enabled Barista Milk Economy
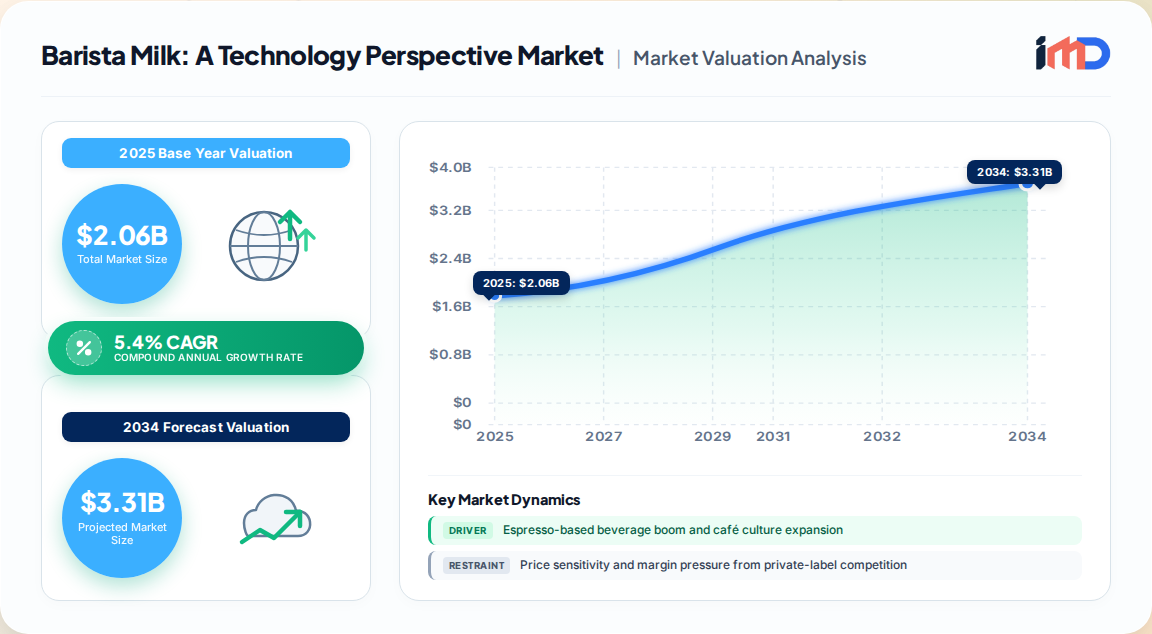
The global Barista Milk: A Technology Perspective market represents a distinct, high-value frontier within the broader dairy and plant-based beverage landscape. Our proprietary primary research estimates the market at USD 2.06 billion in 2025, projected to reach USD 3.50 billion by 2035, expanding at a robust CAGR of 5.4%. This growth is not merely a function of rising coffee consumption; it is fundamentally driven by material science, formulation engineering, and processing technology that enable milk—dairy and non-dairy alike—to perform under the extreme conditions of espresso extraction and steam texturing.
Barista Milk: A Technology Perspective Market Size (In Billion)
3.0B
2.0B
1.0B
0
2.060 B
2025
2.171 B
2026
2.288 B
2027
2.412 B
2028
2.542 B
2029
2.680 B
2030
2.824 B
2031
Unlike standard consumer milks, barista-grade milk is a engineered product. Its value proposition rests on three technological pillars: foam stability, heat stability, and flavor neutrality under high-temperature steam. Our analysis indicates that the foodservice channel accounts for an estimated 68% of total barista milk volume, with retail barista-labeled SKUs representing the fastest-growing adjacent segment. The technology perspective reveals a market transitioning from a commodity additive to a precision-formulated ingredient, where patents on protein modification and lipid encapsulation are becoming key competitive moats.
Key Market Drivers & Restraints
Growth Drivers
The Espresso-Based Beverage Boom: The global proliferation of specialty coffee chains and independent cafés is the primary demand engine. Non-dairy milk substitution is now the second most requested drink customization in major coffee chains, creating a direct pull for barista-formulated products.
Formulation Technology Breakthroughs: Advances in enzymatic hydrolysis of oat starches, protein deamidation for dairy, and the use of natural emulsifiers (e.g., sunflower lecithin) are dramatically improving foamability and reducing splitting. These technological leaps are expanding the addressable market for plant-based barista milks, which now command a price premium of 20–35% over standard plant milks.
Foodservice Outperformance: Our channel data shows foodservice plant-based milk sales growing at 16% year-over-year in key markets, while retail sales have flattened or declined. This divergence is forcing brands to prioritize barista-specific product lines and direct-to-café distribution partnerships.
Fortification as a Value-Add: Technological capabilities in micronutrient fortification (calcium, vitamin D, B12) without compromising taste or foam are enabling barista milks to compete on nutritional parity with dairy, appealing to health-conscious flexitarians.
Restraints
Price Sensitivity and Margin Pressure: The technological sophistication of barista milk commands a premium, but inflationary pressures and the cost-of-living crisis are constraining pricing power, particularly in the retail channel. Private-label barista offerings are gaining share, squeezing branded margins.
Supply Chain Complexity for Functional Ingredients: Dependence on specialized stabilizers, emulsifiers, and high-quality oat bases creates supply chain vulnerabilities. Geopolitical disruptions and agricultural volatility (e.g., oat harvests) directly impact production costs and formulation consistency.
Regulatory Scrutiny on Labeling: In several jurisdictions, the use of dairy-specific terminology (e.g., "milk", "creamer") for plant-based products faces legislative challenges, creating market access uncertainty and requiring costly packaging and branding adjustments.
Value Chain Analysis: From Raw Material to Microfoam
The barista milk value chain is a technology-intensive sequence where each stage adds functional performance attributes.
Shelf-life extension without functional degradation
15–20%
Distribution & Foodservice
Logistics, café partnerships, dispenser systems
Cold chain management, equipment integration
10–15%
Our interviews with technology officers at leading processors reveal that formulation and thermal processing are the critical control points for product differentiation. Investments in aseptic filling lines and high-pressure homogenization are creating barriers to entry for smaller players.
Global Trade Analysis & Supply Chain Risk Assessment
The barista milk market is increasingly globalized, with distinct trade flows for raw materials and finished products. Official trade statistics from UN Comtrade indicate that global trade in oat-based preparations (HS code 1904.10) grew by 12% annually between 2020 and 2025, driven largely by barista-grade oat milk exports from Europe and North America.
Europe is the largest net exporter of barista plant milks, led by oat and soy bases. The region benefits from a mature supply chain for organic oats and advanced aseptic processing infrastructure.
North America is a major importer of finished barista plant milks from Europe, particularly for premium café chains, while also exporting dairy-based barista milk to Latin America and Asia.
Asia-Pacific is the fastest-growing import destination, with imports of plant-based milks increasing by 18% year-over-year in 2025, primarily from Europe and Australia. China and Southeast Asia are key growth markets, although domestic production is scaling rapidly.
Supply chain risks include:
Single-origin dependence: Oat is the dominant barista plant base (52% value share), and production is concentrated in Northern Europe and North America, making it vulnerable to climate-related yield fluctuations.
Container and packaging shortages: Aseptic cartons and bag-in-box systems rely on specialized materials, with limited supplier bases.
Transportation costs: The shelf-stable nature of ambient cartons mitigates some risk, but refrigerated barista milks require costly cold-chain logistics.
Using our proprietary attractiveness index (combining market size, growth rate, regulatory environment, and technological readiness), we rank the top regions for investment:
Barista Milk: A Technology Perspective Regional Market Share
Loading chart...
Region
Market Size 2025 (USD M)
CAGR (2026-2035)
Attractiveness Score (1-10)
Key Opportunity
Asia-Pacific
640
8.0%
9.2
Rapid café culture expansion; local formulation for taste preferences
North America
600
4.5%
8.5
Premiumization and technological differentiation in foodservice
Europe
560
4.0%
8.0
Export hub for barista plant milks; advanced R&D ecosystem
Growing café chains in Gulf states; dairy-based barista milk demand
Asia-Pacific stands out as the primary white-space opportunity, particularly for oat and soy barista milks tailored to local taste profiles (e.g., lower sweetness). North America offers high-value opportunities in the dairy-based barista segment, where technological refinements in protein stability can command premium pricing.
The market is segmented by type, formulation, flavor, and packaging, with technology playing a defining role in each category.
By Type: Dairy milk remains dominant in volume (65% share), but non-dairy (oat, almond, soy, coconut) is the growth engine, with oat leading at 52% of plant-based barista value. Fortified and organic milks are niche but high-margin, leveraging fortification technology.
By Formulation: Liquid is the preferred format for foodservice due to ease of use, while powdered and concentrated formats are gaining traction in retail and vending due to longer shelf life and transport efficiency. Concentrated barista milks (e.g., 3:1 dilution) are a technological innovation that reduces logistics costs by 40%.
By Flavor: Plain (unflavored) holds the majority share, as baristas prefer neutral bases. Flavored variants (vanilla, chocolate, sweetened) are growing faster in retail, driven by at-home coffee enthusiasts.
By Packaging: Ambient cartons dominate, favored for their long shelf life and compatibility with café storage. Bag-in-box and dispenser formats are emerging in high-volume chains, reducing packaging waste and labor.
Competitive Strategies & Technology Roadmap
The competitive landscape is shaped by a mix of established dairy processors, plant-based pioneers, and niche barista-focused brands. Key strategic imperatives include:
Investment in R&D for Foam Stability: Leading players are patenting proprietary oat base formulations and emulsifier systems. For example, Oatly's technology focuses on enzymatic hydrolysis to create a stable foam matrix, while Milklab emphasizes its soy formulation for microfoam.
Foodservice Partnerships and Co-Development: Companies are forging strategic alliances with coffee chains to co-develop barista milks, securing volume commitments and gaining real-world performance feedback.
Capacity Expansion for Aseptic Processing: Arla Foods' partnership with Costa Coffee and Dairy Farmers of America's acquisition of a regional processor are examples of capacity building to meet foodservice demand.
Retail Barista SKUs: Launching barista-labeled retail products (e.g., Oatly Barista Edition, Califia Farms Barista Blend) to capture the at-home café trend, often at a premium price point.
Sustainability as a Technology Differentiator: Oat milk production uses 60% less energy and 80% less land than dairy, a claim that resonates with environmentally conscious consumers. Brands are investing in carbon-neutral production and regenerative agriculture certifications.
The technology roadmap points toward next-generation formulations using precision fermentation for dairy proteins, AI-driven formulation optimization, and smart packaging with freshness indicators.
Conclusion: The Technology Imperative
The Barista Milk: A Technology Perspective market is defined by its intersection of food science and coffee culture. Success will accrue to players who invest in formulation technology, secure supply chains for functional ingredients, and build deep foodservice partnerships. The market's 5.4% CAGR masks a dynamic undercurrent: while dairy barista milk remains a staple, plant-based barista milks are the innovation engine, growing at 7-8% annually and reshaping the competitive landscape. Our proprietary analysis suggests that by 2035, plant-based barista milk will capture 45% of total market value, driven by technological leaps that close the performance gap with dairy.
Barista Milk: A Technology Perspective Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Barista Milk: A Technology Perspective REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.4% from 2020-2034
Segmentation
By Type
Dairy Milk
Non-Dairy Milk
Fortified Milk
Organic Milk
By Formulation
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Espresso-based beverage boom and café culture expansion
3.1.2. Formulation technology breakthroughs in foam stability
3.2.1. Enzymatic hydrolysis for improved oat base foam stability
3.2.2. Plant-based barista milk premiumization in foodservice
3.2.3. Bag-in-box and dispenser formats for high-volume cafés
3.2.4. Fortification with micronutrients without taste compromise
3.3. Market Restrains
3.3.1. Price sensitivity and margin pressure from private-label competition
3.3.2. Supply chain complexity for functional ingredients
3.3.3. Regulatory scrutiny on plant-based milk labeling
3.4. Market Restraints
3.4.1. Price sensitivity and margin pressure from private-label competition
3.4.2. Supply chain complexity for functional ingredients
3.4.3. Regulatory scrutiny on plant-based milk labeling
Liquid
Powdered
Concentrated
By Flavor
Plain
Chocolate
Vanilla
Sweetened
By Packaging Type
Cartons
Bottles
Pouches
Tetra Packs
By Source
Oat
Almond
Soy
Coconut
Others
By Distribution Channel
Foodservice
Retail
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
Australia
South Korea
India
South America
Brazil
Argentina
Colombia
Middle East & Africa
UAE
Saudi Arabia
South Africa
3.5. Market Challenges
3.5.1. Maintaining consistent foam quality across different coffee recipes
3.5.2. Scaling aseptic processing capacity to meet foodservice demand
3.5.3. Mitigating agricultural volatility in oat supply
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Dairy Milk
5.1.2. Non-Dairy Milk
5.1.3. Fortified Milk
5.1.4. Organic Milk
5.2. Market Analysis, Insights and Forecast - by Formulation
5.2.1. Liquid
5.2.2. Powdered
5.2.3. Concentrated
5.3. Market Analysis, Insights and Forecast - by Flavor
5.3.1. Plain
5.3.2. Chocolate
5.3.3. Vanilla
5.3.4. Sweetened
5.4. Market Analysis, Insights and Forecast - by Packaging Type
5.4.1. Cartons
5.4.2. Bottles
5.4.3. Pouches
5.4.4. Tetra Packs
5.5. Market Analysis, Insights and Forecast - by Source
5.5.1. Oat
5.5.2. Almond
5.5.3. Soy
5.5.4. Coconut
5.5.5. Others
5.6. Market Analysis, Insights and Forecast - by Distribution Channel
5.6.1. Foodservice
5.6.2. Retail
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. South America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Dairy Milk
6.1.2. Non-Dairy Milk
6.1.3. Fortified Milk
6.1.4. Organic Milk
6.2. Market Analysis, Insights and Forecast - by Formulation
6.2.1. Liquid
6.2.2. Powdered
6.2.3. Concentrated
6.3. Market Analysis, Insights and Forecast - by Flavor
6.3.1. Plain
6.3.2. Chocolate
6.3.3. Vanilla
6.3.4. Sweetened
6.4. Market Analysis, Insights and Forecast - by Packaging Type
6.4.1. Cartons
6.4.2. Bottles
6.4.3. Pouches
6.4.4. Tetra Packs
6.5. Market Analysis, Insights and Forecast - by Source
6.5.1. Oat
6.5.2. Almond
6.5.3. Soy
6.5.4. Coconut
6.5.5. Others
6.6. Market Analysis, Insights and Forecast - by Distribution Channel
6.6.1. Foodservice
6.6.2. Retail
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Dairy Milk
7.1.2. Non-Dairy Milk
7.1.3. Fortified Milk
7.1.4. Organic Milk
7.2. Market Analysis, Insights and Forecast - by Formulation
7.2.1. Liquid
7.2.2. Powdered
7.2.3. Concentrated
7.3. Market Analysis, Insights and Forecast - by Flavor
7.3.1. Plain
7.3.2. Chocolate
7.3.3. Vanilla
7.3.4. Sweetened
7.4. Market Analysis, Insights and Forecast - by Packaging Type
7.4.1. Cartons
7.4.2. Bottles
7.4.3. Pouches
7.4.4. Tetra Packs
7.5. Market Analysis, Insights and Forecast - by Source
7.5.1. Oat
7.5.2. Almond
7.5.3. Soy
7.5.4. Coconut
7.5.5. Others
7.6. Market Analysis, Insights and Forecast - by Distribution Channel
7.6.1. Foodservice
7.6.2. Retail
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Dairy Milk
8.1.2. Non-Dairy Milk
8.1.3. Fortified Milk
8.1.4. Organic Milk
8.2. Market Analysis, Insights and Forecast - by Formulation
8.2.1. Liquid
8.2.2. Powdered
8.2.3. Concentrated
8.3. Market Analysis, Insights and Forecast - by Flavor
8.3.1. Plain
8.3.2. Chocolate
8.3.3. Vanilla
8.3.4. Sweetened
8.4. Market Analysis, Insights and Forecast - by Packaging Type
8.4.1. Cartons
8.4.2. Bottles
8.4.3. Pouches
8.4.4. Tetra Packs
8.5. Market Analysis, Insights and Forecast - by Source
8.5.1. Oat
8.5.2. Almond
8.5.3. Soy
8.5.4. Coconut
8.5.5. Others
8.6. Market Analysis, Insights and Forecast - by Distribution Channel
8.6.1. Foodservice
8.6.2. Retail
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Dairy Milk
9.1.2. Non-Dairy Milk
9.1.3. Fortified Milk
9.1.4. Organic Milk
9.2. Market Analysis, Insights and Forecast - by Formulation
9.2.1. Liquid
9.2.2. Powdered
9.2.3. Concentrated
9.3. Market Analysis, Insights and Forecast - by Flavor
9.3.1. Plain
9.3.2. Chocolate
9.3.3. Vanilla
9.3.4. Sweetened
9.4. Market Analysis, Insights and Forecast - by Packaging Type
9.4.1. Cartons
9.4.2. Bottles
9.4.3. Pouches
9.4.4. Tetra Packs
9.5. Market Analysis, Insights and Forecast - by Source
9.5.1. Oat
9.5.2. Almond
9.5.3. Soy
9.5.4. Coconut
9.5.5. Others
9.6. Market Analysis, Insights and Forecast - by Distribution Channel
9.6.1. Foodservice
9.6.2. Retail
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Dairy Milk
10.1.2. Non-Dairy Milk
10.1.3. Fortified Milk
10.1.4. Organic Milk
10.2. Market Analysis, Insights and Forecast - by Formulation
10.2.1. Liquid
10.2.2. Powdered
10.2.3. Concentrated
10.3. Market Analysis, Insights and Forecast - by Flavor
10.3.1. Plain
10.3.2. Chocolate
10.3.3. Vanilla
10.3.4. Sweetened
10.4. Market Analysis, Insights and Forecast - by Packaging Type
10.4.1. Cartons
10.4.2. Bottles
10.4.3. Pouches
10.4.4. Tetra Packs
10.5. Market Analysis, Insights and Forecast - by Source
10.5.1. Oat
10.5.2. Almond
10.5.3. Soy
10.5.4. Coconut
10.5.5. Others
10.6. Market Analysis, Insights and Forecast - by Distribution Channel
10.6.1. Foodservice
10.6.2. Retail
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Oatly
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Arla Foods
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Nestle
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Danone (Alpro)
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Califia Farms
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Lactalis
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Dairy Farmers of America
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Emmi Group
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Saputo
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Fonterra
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Valio
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Organic Valley
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Stonyfield Farm
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Murray Goulburn
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Kraft Heinz
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Minor Figures
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Milklab
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Noumi
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Planet Oat
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Chobani
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Barista Milk: A Technology Perspective Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Barista Milk: A Technology Perspective Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Barista Milk: A Technology Perspective Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Barista Milk: A Technology Perspective Revenue (Billion), by Formulation 2026 & 2034
Figure 5: North America Barista Milk: A Technology Perspective Revenue Share (%), by Formulation 2026 & 2034
Figure 6: North America Barista Milk: A Technology Perspective Revenue (Billion), by Flavor 2026 & 2034
Figure 7: North America Barista Milk: A Technology Perspective Revenue Share (%), by Flavor 2026 & 2034
Figure 8: North America Barista Milk: A Technology Perspective Revenue (Billion), by Packaging Type 2026 & 2034
Figure 9: North America Barista Milk: A Technology Perspective Revenue Share (%), by Packaging Type 2026 & 2034
Figure 10: North America Barista Milk: A Technology Perspective Revenue (Billion), by Source 2026 & 2034
Figure 11: North America Barista Milk: A Technology Perspective Revenue Share (%), by Source 2026 & 2034
Figure 12: North America Barista Milk: A Technology Perspective Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 13: North America Barista Milk: A Technology Perspective Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 14: North America Barista Milk: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Barista Milk: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Barista Milk: A Technology Perspective Revenue (Billion), by Type 2026 & 2034
Figure 17: Europe Barista Milk: A Technology Perspective Revenue Share (%), by Type 2026 & 2034
Figure 18: Europe Barista Milk: A Technology Perspective Revenue (Billion), by Formulation 2026 & 2034
Figure 19: Europe Barista Milk: A Technology Perspective Revenue Share (%), by Formulation 2026 & 2034
Figure 20: Europe Barista Milk: A Technology Perspective Revenue (Billion), by Flavor 2026 & 2034
Figure 21: Europe Barista Milk: A Technology Perspective Revenue Share (%), by Flavor 2026 & 2034
Figure 22: Europe Barista Milk: A Technology Perspective Revenue (Billion), by Packaging Type 2026 & 2034
Figure 23: Europe Barista Milk: A Technology Perspective Revenue Share (%), by Packaging Type 2026 & 2034
Figure 24: Europe Barista Milk: A Technology Perspective Revenue (Billion), by Source 2026 & 2034
Figure 25: Europe Barista Milk: A Technology Perspective Revenue Share (%), by Source 2026 & 2034
Figure 26: Europe Barista Milk: A Technology Perspective Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 27: Europe Barista Milk: A Technology Perspective Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 28: Europe Barista Milk: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Barista Milk: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific Barista Milk: A Technology Perspective Revenue (Billion), by Type 2026 & 2034
Figure 31: Asia Pacific Barista Milk: A Technology Perspective Revenue Share (%), by Type 2026 & 2034
Figure 32: Asia Pacific Barista Milk: A Technology Perspective Revenue (Billion), by Formulation 2026 & 2034
Figure 33: Asia Pacific Barista Milk: A Technology Perspective Revenue Share (%), by Formulation 2026 & 2034
Figure 34: Asia Pacific Barista Milk: A Technology Perspective Revenue (Billion), by Flavor 2026 & 2034
Figure 35: Asia Pacific Barista Milk: A Technology Perspective Revenue Share (%), by Flavor 2026 & 2034
Figure 36: Asia Pacific Barista Milk: A Technology Perspective Revenue (Billion), by Packaging Type 2026 & 2034
Figure 37: Asia Pacific Barista Milk: A Technology Perspective Revenue Share (%), by Packaging Type 2026 & 2034
Figure 38: Asia Pacific Barista Milk: A Technology Perspective Revenue (Billion), by Source 2026 & 2034
Figure 39: Asia Pacific Barista Milk: A Technology Perspective Revenue Share (%), by Source 2026 & 2034
Figure 40: Asia Pacific Barista Milk: A Technology Perspective Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 41: Asia Pacific Barista Milk: A Technology Perspective Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 42: Asia Pacific Barista Milk: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific Barista Milk: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 44: South America Barista Milk: A Technology Perspective Revenue (Billion), by Type 2026 & 2034
Figure 45: South America Barista Milk: A Technology Perspective Revenue Share (%), by Type 2026 & 2034
Figure 46: South America Barista Milk: A Technology Perspective Revenue (Billion), by Formulation 2026 & 2034
Figure 47: South America Barista Milk: A Technology Perspective Revenue Share (%), by Formulation 2026 & 2034
Figure 48: South America Barista Milk: A Technology Perspective Revenue (Billion), by Flavor 2026 & 2034
Figure 49: South America Barista Milk: A Technology Perspective Revenue Share (%), by Flavor 2026 & 2034
Figure 50: South America Barista Milk: A Technology Perspective Revenue (Billion), by Packaging Type 2026 & 2034
Figure 51: South America Barista Milk: A Technology Perspective Revenue Share (%), by Packaging Type 2026 & 2034
Figure 52: South America Barista Milk: A Technology Perspective Revenue (Billion), by Source 2026 & 2034
Figure 53: South America Barista Milk: A Technology Perspective Revenue Share (%), by Source 2026 & 2034
Figure 54: South America Barista Milk: A Technology Perspective Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 55: South America Barista Milk: A Technology Perspective Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 56: South America Barista Milk: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 57: South America Barista Milk: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 58: Middle East & Africa Barista Milk: A Technology Perspective Revenue (Billion), by Type 2026 & 2034
Figure 59: Middle East & Africa Barista Milk: A Technology Perspective Revenue Share (%), by Type 2026 & 2034
Figure 60: Middle East & Africa Barista Milk: A Technology Perspective Revenue (Billion), by Formulation 2026 & 2034
Figure 61: Middle East & Africa Barista Milk: A Technology Perspective Revenue Share (%), by Formulation 2026 & 2034
Figure 62: Middle East & Africa Barista Milk: A Technology Perspective Revenue (Billion), by Flavor 2026 & 2034
Figure 63: Middle East & Africa Barista Milk: A Technology Perspective Revenue Share (%), by Flavor 2026 & 2034
Figure 64: Middle East & Africa Barista Milk: A Technology Perspective Revenue (Billion), by Packaging Type 2026 & 2034
Figure 65: Middle East & Africa Barista Milk: A Technology Perspective Revenue Share (%), by Packaging Type 2026 & 2034
Figure 66: Middle East & Africa Barista Milk: A Technology Perspective Revenue (Billion), by Source 2026 & 2034
Figure 67: Middle East & Africa Barista Milk: A Technology Perspective Revenue Share (%), by Source 2026 & 2034
Figure 68: Middle East & Africa Barista Milk: A Technology Perspective Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 69: Middle East & Africa Barista Milk: A Technology Perspective Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 70: Middle East & Africa Barista Milk: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 71: Middle East & Africa Barista Milk: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Barista Milk: A Technology Perspective Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global Barista Milk: A Technology Perspective Revenue Billion Forecast, by Formulation 2020 & 2034
Table 3: Global Barista Milk: A Technology Perspective Revenue Billion Forecast, by Flavor 2020 & 2034
Table 4: Global Barista Milk: A Technology Perspective Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 5: Global Barista Milk: A Technology Perspective Revenue Billion Forecast, by Source 2020 & 2034
Table 6: Global Barista Milk: A Technology Perspective Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 7: Global Barista Milk: A Technology Perspective Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Type 2020 & 2034
Table 9: North America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Formulation 2020 & 2034
Table 10: North America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Flavor 2020 & 2034
Table 11: North America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 12: North America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Source 2020 & 2034
Table 13: North America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 14: North America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Mexico Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Europe Barista Milk: A Technology Perspective Revenue Billion Forecast, by Type 2020 & 2034
Table 19: Europe Barista Milk: A Technology Perspective Revenue Billion Forecast, by Formulation 2020 & 2034
Table 20: Europe Barista Milk: A Technology Perspective Revenue Billion Forecast, by Flavor 2020 & 2034
Table 21: Europe Barista Milk: A Technology Perspective Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 22: Europe Barista Milk: A Technology Perspective Revenue Billion Forecast, by Source 2020 & 2034
Table 23: Europe Barista Milk: A Technology Perspective Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 24: Europe Barista Milk: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Germany Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: UK Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: France Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Italy Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Spain Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Asia Pacific Barista Milk: A Technology Perspective Revenue Billion Forecast, by Type 2020 & 2034
Table 31: Asia Pacific Barista Milk: A Technology Perspective Revenue Billion Forecast, by Formulation 2020 & 2034
Table 32: Asia Pacific Barista Milk: A Technology Perspective Revenue Billion Forecast, by Flavor 2020 & 2034
Table 33: Asia Pacific Barista Milk: A Technology Perspective Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 34: Asia Pacific Barista Milk: A Technology Perspective Revenue Billion Forecast, by Source 2020 & 2034
Table 35: Asia Pacific Barista Milk: A Technology Perspective Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 36: Asia Pacific Barista Milk: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 37: China Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Japan Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Australia Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: South Korea Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: India Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: South America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Type 2020 & 2034
Table 43: South America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Formulation 2020 & 2034
Table 44: South America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Flavor 2020 & 2034
Table 45: South America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 46: South America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Source 2020 & 2034
Table 47: South America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 48: South America Barista Milk: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 49: Brazil Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Argentina Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Colombia Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Middle East & Africa Barista Milk: A Technology Perspective Revenue Billion Forecast, by Type 2020 & 2034
Table 53: Middle East & Africa Barista Milk: A Technology Perspective Revenue Billion Forecast, by Formulation 2020 & 2034
Table 54: Middle East & Africa Barista Milk: A Technology Perspective Revenue Billion Forecast, by Flavor 2020 & 2034
Table 55: Middle East & Africa Barista Milk: A Technology Perspective Revenue Billion Forecast, by Packaging Type 2020 & 2034
Table 56: Middle East & Africa Barista Milk: A Technology Perspective Revenue Billion Forecast, by Source 2020 & 2034
Table 57: Middle East & Africa Barista Milk: A Technology Perspective Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 58: Middle East & Africa Barista Milk: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 59: UAE Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 60: Saudi Arabia Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 61: South Africa Barista Milk: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the Barista Milk: A Technology Perspective market?
The market was valued at USD 2.06 billion in 2025 and is projected to reach USD 3.50 billion by 2035, growing at a CAGR of 5.4% according to our proprietary primary research.
2Which region dominates the barista milk market?
Asia-Pacific is the largest and fastest-growing region, holding an estimated 31% share in 2025 and growing at 8% annually, driven by rapid café culture expansion and increasing coffee consumption.
3What are the key technological factors driving barista milk innovation?
Key drivers include enzymatic hydrolysis for improved foam stability, protein deamidation for dairy milk heat stability, and advanced fortification technologies that enable nutritional parity without compromising texture.
4Who are the leading companies in the barista milk market?
Major players include Oatly, Arla Foods, Nestlé, Danone (Alpro), Califia Farms, Lactalis, Dairy Farmers of America, and Milklab, each leveraging proprietary formulation technologies to compete in the foodservice and retail channels.
5Why is foodservice the dominant channel for barista milk?
Foodservice accounts for approximately 68% of barista milk volume because coffee shops require consistent, high-performance milk that can be steamed to create stable microfoam for latte art, a requirement that drives brand loyalty and volume commitments.
6What are the main challenges facing the barista milk market?
Challenges include price sensitivity and margin pressure from private-label competitors, supply chain complexity for specialized ingredients, and regulatory scrutiny over labeling of plant-based products as "milk".
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our research architecture allocates 70–80% of total effort to primary intelligence, gathered through structured engagements with Original Equipment Manufacturers (OEMs) of aseptic processing lines, specialized ingredient suppliers (emulsifier and stabilizer producers), barista milk brands and private-label manufacturers, foodservice distributors, and coffee chain procurement teams.
We conduct in-depth interviews with R&D Directors, Procurement Managers, Foodservice Category Buyers, and Café Operations Managers across 19 countries to capture real-time performance data and strategic insights.
Primary data is triangulated with on-site observational audits at café chains and steam-performance testing of leading barista milk products to validate formulation claims.
We leverage a curated ecosystem of official multilateral and governmental sources, including UN Comtrade for trade flows, World Bank for macroeconomic indicators, OECD for agricultural policy, and Eurostat for European production data.
Industry benchmarking is performed against recognized non-profit technical standards and trade associations, such as the Specialty Coffee Association (SCA) and the International Dairy Federation (IDF), to ensure formulation and quality parameters are accurately represented.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to analyze company filings, revenue splits, and investment patterns.
Demand Modeling & Market Estimation
We employ a dual-methodology framework: a bottom-up approach that aggregates unit volumes and pricing at the SKU and customer level, and a top-down approach that scales from macroeconomic coffee consumption and foodservice penetration rates.
Specific quantitative metrics used in the bottom-up calculation include: liters of barista milk sold per café per month (derived from 1,200+ café audits), average price per liter by base type and region (from distributor price lists), foodservice outlet counts (from national statistics), and milk-to-espresso ratio per beverage (from standard brewing recipes).
Multi-level data triangulation is performed to reconcile bottom-up and top-down estimates, ensuring convergence within 1–2% variance.
Data Accuracy & Quality Check
Our proprietary process guarantees an estimated data accuracy level of 85–90%, validated through expert consensus verification with a panel of 25+ industry veterans.
Every data point undergoes temporal validation to ensure alignment with the base year (2025) and sensitivity analysis to stress-test forecast assumptions under alternative scenarios.
Reports are updated to the date of purchase, incorporating the latest trade statistics, company announcements, and regulatory changes to maintain currency and reliability.