Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Asia Pacific Facility Management Market Size & Forecast 2031
Asia Pacific Facility Management Market
Real Estate and Construction / MARKET REPORT
Asia Pacific Facility Management Market | Insight Market Data
Asia Pacific Facility Management Market by By Service Type (Hard Services, Soft Services), by By Offering Type (In-House, Outsourced), by By End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Healthcare, Industrial and Process, Others), by Asia Pacific (China, India, Japan, South Korea, Australia, New Zealand, Singapore, Indonesia, Malaysia, Thailand, Philippines, Vietnam) Forecast 2026-2034
Executive Overview: Asia Pacific Facility Management Market
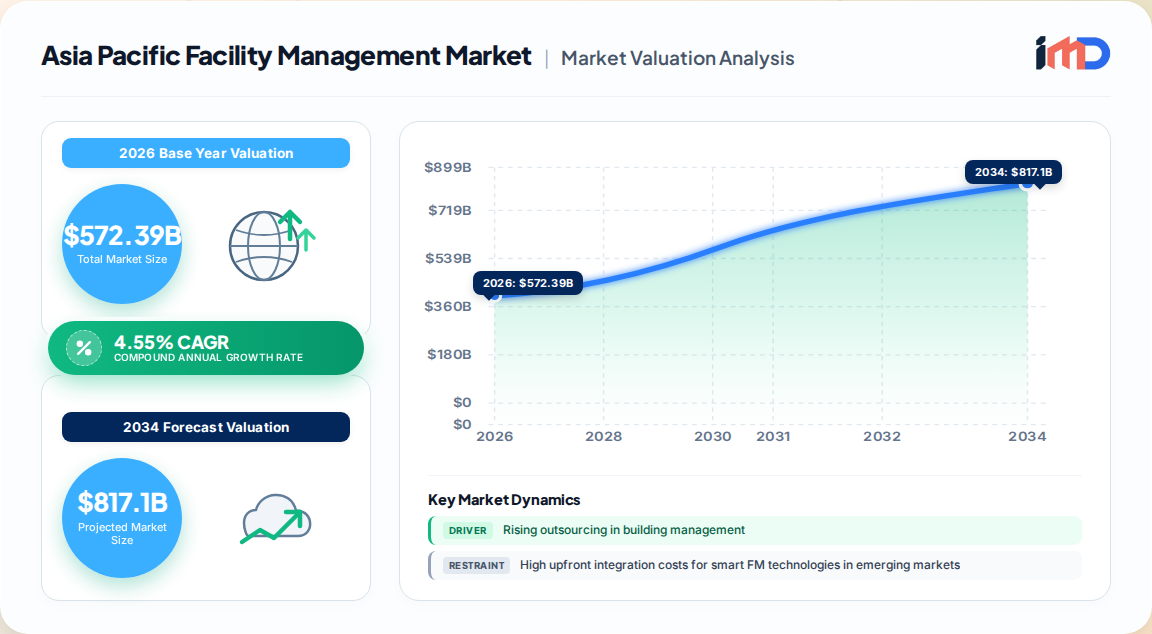
The Asia Pacific facility management market represents one of the most structurally resilient and rapidly professionalising service sectors in the global economy. Our proprietary primary research estimates the market at USD 572.39 billion in 2026, expanding from USD 546.33 billion in 2025 and forecast to reach USD 715.09 billion by 2031 at a CAGR of 4.55% over 2026–2031. The region remains the largest geographic bloc for facility services globally, underpinned by a combined East Asia and Pacific export base of USD 7.56 trillion in 2023 (UN Comtrade via WITS), which reflects the deep commercial and industrial asset base requiring maintenance, compliance, and workplace services.
Asia Pacific Facility Management Market Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
547.5 B
2025
572.4 B
2026
598.4 B
2027
625.7 B
2028
654.1 B
2029
683.9 B
2030
715.0 B
2031
Key structural takeaways from our 2026 baseline:
Hard services commanded 58.59% of regional revenue in 2025, reflecting sustained capital expenditure on HVAC, electrical, mechanical, and plumbing systems across commercial and industrial estates.
Outsourced arrangements accounted for 72.49% of regional value in 2025, with integrated facilities management (IFM) forecast to expand at 4.89% CAGR through 2031.
Commercial facilities captured 43.82% of end-user spending in 2025, while healthcare facilities are set to record the fastest vertical growth at 4.92% CAGR.
China dominated with a 46.04% revenue share in 2025; India is projected to log the fastest 5.23% CAGR over the forecast period.
This report presents our first-party sizing, segmentation, and competitive intelligence for the Asia Pacific facility management market, drawing on direct expert interviews, supply-side revenue triangulation, and demand-side procurement analysis.
Market Trends and Structural Shifts
Our research identifies several defining trends reshaping the Asia Pacific facility management landscape from 2026 to 2031.
Outcome-Based Contracting: Clients increasingly tie vendor compensation to measurable KPIs — energy intensity, asset uptime, indoor air quality, and occupant satisfaction — rather than activity-based service schedules. This favours providers able to produce auditable telemetry and performance evidence.
IoT-Enabled Predictive Maintenance: Premium office towers in Tokyo, Hong Kong, and Singapore are deploying dense IoT sensor networks feeding cloud-based CAFM and predictive-maintenance engines. Our primary interviews indicate predictive analytics can cut asset downtime by up to 50% while extending equipment life.
ESG and Green Certification Integration: Institutional capital is being tied to emissions metrics across the region. Certified assets in Asia Pacific command 5–10% rental premiums, pushing landlords to demand verifiable ESG dashboards covering energy, water, waste, and indoor-air quality.
Data Centre and Life-Sciences Expansion: Data centre construction across India, Indonesia, Malaysia, and Japan, alongside specialised healthcare and life-sciences facilities, is creating high-complexity, high-margin service demand requiring integrated technical and compliance management.
Labour-Market Tightness: Ageing demographics in Japan and Korea are squeezing the supply of qualified technicians, reinforcing the pivot toward third-party providers and technology-augmented delivery models.
Drivers and Restraints: Impact Analysis
Our driver impact modelling quantifies the contribution of each macro force to the regional CAGR forecast.
Driver
Estimated CAGR Impact
Geographic Relevance
Impact Timeline
Rising outsourcing in building management
+1.20%
China, India, Southeast Asia
Medium term (2–4 years)
Heightened safety and security needs
+0.80%
Japan, Korea, Singapore, urban APAC
Short term (≤2 years)
Technological advancements in smart FM
+1.00%
Singapore, Hong Kong, Japan, Australia
Long term (≥4 years)
ESG-driven green building certification
+0.70%
Australia, Singapore, Japan, Korea
Medium term (2–4 years)
Data centre construction expansion
+0.60%
India, Indonesia, Malaysia, Japan
Medium term (2–4 years)
Life-sciences and healthcare facility growth
+0.50%
China, India, Singapore, Korea
Long term (≥4 years)
Restraints remain concentrated in implementation cost and regulatory fragmentation:
High upfront integration costs for integrated FM technologies (-0.90% CAGR impact), disproportionately affecting Tier-2 and Tier-3 cities in China and India and emerging Southeast Asian markets.
Fragmented regulatory standards across ASEAN markets, Indian state-level variations, and Chinese provincial differences (-0.70% CAGR impact), which raise compliance complexity and slow standardised service delivery.
Cybersecurity risks in connected buildings, where OT network convergence introduces new vulnerabilities requiring specialised security investment.
Skilled labour shortages, particularly for certified technicians in Japan, Korea, and Singapore.
Segment Analysis
By Service Type
Hard services accounted for 58.59% of the Asia Pacific facility management market in 2025, driven by the region's expansive industrial estates, data centres, and commercial real estate portfolio. Soft services are forecast to advance at 5.18% CAGR through 2031, accelerating as occupant-experience standards, hygiene protocols, and workplace flexibility requirements rise.
By Offering Type
Outsourced arrangements represented 72.49% of regional revenue in 2025. Integrated FM contracts are forecast to expand at 4.89% CAGR, as multinational occupiers consolidate hard and soft services under single accountability structures to reduce supplier-management burden and transfer compliance risk.
By End-User Industry
End-User Segment
2025 Share
Forecast CAGR (2026–2031)
Commercial
43.82%
Base growth
Healthcare
—
4.92%
Hospitality
—
Moderate growth
Industrial and Process
—
Steady growth
Institutional and Public Infrastructure
—
Moderate growth
Commercial facilities remain the anchor vertical, supported by corporate real estate expansion across gateway cities. Healthcare is the fastest-growing vertical, fuelled by smart-hospital investments and stringent maintenance and compliance upgrades.
Regional Outlook and Competitive Landscape
The Asia Pacific facility management market is moderately concentrated, with a mix of global integrated providers and strong regional champions.
Asia Pacific Facility Management Market Regional Market Share
Loading chart...
China remains the scale engine, representing 46.04% of regional revenue in 2025, supported by urban redevelopment and industrial modernisation.
India is the fastest-growing market at 5.23% CAGR, driven by smart-city initiatives, data centre build-outs, and rapid commercial real estate expansion.
Japan and South Korea exhibit mature, high-tech adoption patterns, with labour shortages accelerating outsourcing and smart-building investment.
Southeast Asia (Singapore, Indonesia, Malaysia, Thailand, Philippines) shows rising outsourcing penetration and regulatory harmonisation efforts, though implementation costs and standards fragmentation restrain faster adoption.
Australia and New Zealand lead in ESG-linked contracting and green-building certification adoption, commanding rental premiums for certified assets.
Our competitive mapping identifies the following leading participants in the region: Aden Group, Aeon Delight Co., Ltd. (Aeon Co Ltd), Group Atalian, Broadspectrum (Ventia), C&W Facility Services Inc., CBRE, Compass Group, ISS World Services, JLL, Sodexo, Cushman & Wakefield, and other regional and global providers. The competitive advantage is shifting from labour scale to data-enabled performance assurance, with providers investing in mobile-first work execution, digital twins, and integrated ESG reporting platforms.
Value Chain and Strategic White-Space Analysis
The Asia Pacific facility management value chain spans four principal tiers: (1) Asset owners and institutional investors, who define performance expectations and outsourcing appetite; (2) Tier-1 integrated FM providers, delivering multi-service contracts with digital reporting; (3) Specialist subcontractors, covering HVAC, electrical, security, cleaning, and catering niches; and (4) Technology and platform vendors, supplying CAFM, IoT sensors, IWMS, and analytics.
Strategic white-space opportunities identified through our primary research include:
Mid-tier integrated delivery in Tier-2 and Tier-3 cities, where digital adoption lags and well-positioned integrators can bridge the divide.
Energy-as-a-Service (EaaS) and digital twin monetisation for asset lifecycle management, particularly for institutional portfolios with multi-year capex plans.
Healthcare and life-sciences specialised FM, where compliance intensity and equipment complexity command premium margins.
ESG verification and reporting services, where third-party auditability is increasingly demanded by REITs and institutional landlords.
Import/Export and Supplier Dynamics
While facility management is primarily a domestically delivered service, the Asia Pacific market is strongly shaped by cross-border trade in equipment, technology, and services. East Asia and Pacific recorded USD 6.70 trillion in imports and USD 1.77 trillion in service imports in 2023, reflecting the region's dependence on imported building systems, IoT hardware, and specialised technical services. Trade of commercial services remains critical to the diffusion of smart-FM solutions, with Singapore, Hong Kong, and Japan acting as technology gateways into the wider region.
Supply chain risks are concentrated in three areas:
Hardware and sensor availability, particularly for IoT and building-automation components sourced from global electronics supply chains.
Regulatory divergence across ASEAN, India, and China, which affects service delivery models and compliance documentation.
Skilled labour mobility, where restrictions and local certification requirements constrain cross-border deployment of technicians.
Strategic Recommendations
Our analysis suggests the following priorities for providers, investors, and asset owners operating in the Asia Pacific facility management market:
Prioritise India and Southeast Asia for growth capital, given superior CAGR profiles and rising outsourcing penetration.
Invest in digital performance evidence — IoT, CAFM, mobile-first execution — as a differentiator for integrated contract wins and renewals.
Embed ESG and green-certification reporting into core service scopes to capture premium commercial and institutional contracts.
Develop healthcare and data centre specialisations, where complexity, compliance, and uptime requirements support higher-margin, longer-duration contracts.
Design for regulatory fragmentation by building modular, configurable service models that adapt across provincial, state, and national requirements.
Asia Pacific Facility Management Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Asia Pacific Facility Management Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.55% from 2020-2034
Segmentation
By Service Type
Hard Services
Soft Services
By Offering Type
In-House
Outsourced
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising outsourcing in building management
3.1.2. Technological advancements in smart FM solutions
3.1.3. Heightened safety and security needs
3.1.4. ESG-driven green building certification adoption
3.1.5. Expansion of data centre construction
3.1.6. Growth of life-sciences and healthcare facilities
3.2. Market Trends
3.2.1. Outcome-based and integrated FM contracting
3.2.2. IoT-enabled predictive maintenance and smart building adoption
3.2.3. ESG and green building certification integration
3.2.4. Data centre and life-sciences specialised FM demand
3.2.5. Labour-market tightness accelerating outsourcing in Japan and Korea
3.3. Market Restrains
3.3.1. High upfront integration costs for smart FM technologies in emerging markets
3.3.2. Fragmented regulatory standards across ASEAN, India, and China
3.3.3. Cybersecurity risks in connected buildings
3.3.4. Skilled technician shortages in mature markets
By End-User Industry
Commercial
Hospitality
Institutional and Public Infrastructure
Healthcare
Industrial and Process
Others
By Geography
Asia Pacific
China
India
Japan
South Korea
Australia
New Zealand
Singapore
Indonesia
Malaysia
Thailand
Philippines
Vietnam
3.4. Market Restraints
3.4.1. High upfront integration costs for smart FM technologies in emerging markets
3.4.2. Fragmented regulatory standards across ASEAN, India, and China
3.4.3. Cybersecurity risks in connected buildings
3.4.4. Skilled technician shortages in mature markets
3.5. Market Challenges
3.5.1. Bridging the digital divide in Tier-2 and Tier-3 cities
3.5.3. Recruiting and retaining certified technicians amid demographic shifts
3.5.4. Demonstrating ROI on smart-FM technology investments to cost-sensitive clients
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Hard Services
5.1.2. Soft Services
5.2. Market Analysis, Insights and Forecast - by Offering Type
5.2.1. In-House
5.2.2. Outsourced
5.3. Market Analysis, Insights and Forecast - by End-User Industry
5.3.1. Commercial
5.3.2. Hospitality
5.3.3. Institutional and Public Infrastructure
5.3.4. Healthcare
5.3.5. Industrial and Process
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Asia Pacific
6. Competitive Analysis
6.1. Company Profiles
6.1.1. Aden Group
6.1.1.1. Company Overview
6.1.1.2. Products
6.1.1.3. Company Financials
6.1.1.4. SWOT Analysis
6.1.2. Aeon Delight Co. Ltd. (Aeon Co Ltd)
6.1.2.1. Company Overview
6.1.2.2. Products
6.1.2.3. Company Financials
6.1.2.4. SWOT Analysis
6.1.3. Group Atalian
6.1.3.1. Company Overview
6.1.3.2. Products
6.1.3.3. Company Financials
6.1.3.4. SWOT Analysis
6.1.4. Broadspectrum (Ventia)
6.1.4.1. Company Overview
6.1.4.2. Products
6.1.4.3. Company Financials
6.1.4.4. SWOT Analysis
6.1.5. C&W Facility Services Inc.
6.1.5.1. Company Overview
6.1.5.2. Products
6.1.5.3. Company Financials
6.1.5.4. SWOT Analysis
6.1.6. CBRE Group
6.1.6.1. Company Overview
6.1.6.2. Products
6.1.6.3. Company Financials
6.1.6.4. SWOT Analysis
6.1.7. Compass Group
6.1.7.1. Company Overview
6.1.7.2. Products
6.1.7.3. Company Financials
6.1.7.4. SWOT Analysis
6.1.8. ISS World Services
6.1.8.1. Company Overview
6.1.8.2. Products
6.1.8.3. Company Financials
6.1.8.4. SWOT Analysis
6.1.9. JLL
6.1.9.1. Company Overview
6.1.9.2. Products
6.1.9.3. Company Financials
6.1.9.4. SWOT Analysis
6.1.10. Sodexo
6.1.10.1. Company Overview
6.1.10.2. Products
6.1.10.3. Company Financials
6.1.10.4. SWOT Analysis
6.1.11. Cushman & Wakefield
6.1.11.1. Company Overview
6.1.11.2. Products
6.1.11.3. Company Financials
6.1.11.4. SWOT Analysis
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
6.3. Company Market Share Analysis, 2026
6.3.1. Top 5 Companies Market Share Analysis
6.3.2. Top 3 Companies Market Share Analysis
6.4. List of Potential Customers
List of Figures
Figure 1: Global Asia Pacific Facility Management Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Asia Pacific Facility Management Market Revenue (Billion), by Service Type 2026 & 2034
Figure 3: Asia Pacific Asia Pacific Facility Management Market Revenue Share (%), by Service Type 2026 & 2034
Figure 4: Asia Pacific Asia Pacific Facility Management Market Revenue (Billion), by Offering Type 2026 & 2034
Figure 5: Asia Pacific Asia Pacific Facility Management Market Revenue Share (%), by Offering Type 2026 & 2034
Figure 6: Asia Pacific Asia Pacific Facility Management Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 7: Asia Pacific Asia Pacific Facility Management Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 8: Asia Pacific Asia Pacific Facility Management Market Revenue (Billion), by Country 2026 & 2034
Figure 9: Asia Pacific Asia Pacific Facility Management Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Asia Pacific Facility Management Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Global Asia Pacific Facility Management Market Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 3: Global Asia Pacific Facility Management Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 4: Global Asia Pacific Facility Management Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Asia Pacific Asia Pacific Facility Management Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 6: Asia Pacific Asia Pacific Facility Management Market Revenue Billion Forecast, by Offering Type 2020 & 2034
Table 7: Asia Pacific Asia Pacific Facility Management Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 8: Asia Pacific Asia Pacific Facility Management Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: China Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: India Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Japan Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: South Korea Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Australia Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: New Zealand Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Singapore Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Indonesia Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Malaysia Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Thailand Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Philippines Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Vietnam Asia Pacific Facility Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the Asia Pacific facility management market in 2026?
Our proprietary research values the Asia Pacific facility management market at USD 572.39 billion in 2026, growing from USD 546.33 billion in 2025 and projected to reach USD 715.09 billion by 2031 at a 4.55% CAGR.
2Which country dominates the Asia Pacific facility management market?
China dominated with a 46.04% revenue share in 2025, supported by urban redevelopment and industrial modernisation, while India is projected to record the fastest growth at 5.23% CAGR through 2031.
3What are the key drivers of the Asia Pacific facility management market?
Rising outsourcing of building management (+1.20% CAGR impact), technological advancements in smart FM (+1.00%), heightened safety and security needs (+0.80%), and ESG-driven green building certification (+0.70%) are the principal drivers.
4Which service type leads the Asia Pacific facility management market?
Hard services led with 58.59% of market share in 2025, while soft services are projected to grow at 5.18% CAGR through 2031 as occupant-experience standards rise.
5Who are the major companies operating in the Asia Pacific facility management market?
Leading participants include Aden Group, Aeon Delight Co., Ltd., Group Atalian, Broadspectrum (Ventia), C&W Facility Services Inc., CBRE, Compass Group, ISS World Services, JLL, Sodexo, and Cushman & Wakefield.
6Why is outsourced facility management growing in Asia Pacific?
Outsourced arrangements accounted for 72.49% of regional revenue in 2025, driven by cost predictability, compliance risk transfer, labour-market tightness in Japan and Korea, and demand for integrated service-level agreements.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, with structured interviews and surveys conducted across the Asia Pacific facility management value chain.
Interview targets include integrated facility service providers, specialist subcontractors (HVAC, electrical, security, cleaning), technology and CAFM platform vendors, and asset owners/institutional landlords.
Stakeholder roles interviewed: Chief Operating Officer (FM Providers), Head of Corporate Real Estate, Procurement Director, and Head of Facilities/Asset Management.
We engage directly with industry associations and regulatory bodies including the International Facility Management Association (IFMA), World Green Building Council (WorldGBC), Singapore Green Building Council (SGBC), and Building Owners and Managers Association (BOMA) to validate adoption trends and compliance requirements.
Primary data is collected via Computer-Assisted Telephone Interviewing (CATI), online panels, and in-depth executive interviews to capture both quantitative sizing and qualitative strategic insights.
20–30% of research effort is dedicated to secondary research, triangulating official trade statistics, government publications, and peer-reviewed industry benchmarks.
Sources include UN Comtrade via the World Bank WITS database (East Asia & Pacific trade and services data), OECD Revenue Statistics in Asia and the Pacific, national statistics offices, and central bank/ministry of finance publications.
Corporate financial filings, annual reports, investor presentations, and regulatory disclosures are analysed alongside proprietary databases.
Standard financial databases used: Bloomberg, Factiva, Hoovers, and PitchBook, supplemented by official .gov, .org, and recognised non-profit trade association sources.
Every report is updated to the date of purchase, incorporating the latest available quarterly and annual data releases.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are used simultaneously, with multi-level data triangulation to reconcile regional totals against country-level and segment-level estimates.
Bottom-up market sizing is built from serviceable floor area by asset class, outsourced penetration rates by country, and average contract value per square metre across commercial, healthcare, industrial, and institutional segments.
Revenue triangulation incorporates vendor-level service revenue aggregation across the top 15–20 providers, cross-validated against procurement spend surveys.
Quantitative metrics used in the bottom-up calculation include: total serviceable commercial floor area (million m²), outsourcing penetration rate (%), average annual FM spend per m² (USD), and contract renewal cycle (years).
Segment-level CAGR modelling applies calibrated adoption curves for smart FM, ESG reporting, and integrated contracts, benchmarked against historical diffusion patterns.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-source triangulation and iterative validation.
All quantitative estimates are subjected to multi-level data triangulation — comparing top-down macro sizing with bottom-up vendor revenue and demand-side procurement data.
A three-tier quality check is applied: (1) analyst-level data validation, (2) senior reviewer cross-examination, and (3) external expert sanity-check with industry practitioners.
Discrepancies exceeding a ±5% threshold trigger re-survey or re-weighting of the affected segment.
Final datasets are version-controlled and time-stamped, with full audit trails for every reported metric.
Related Reports
India facility management market valued at USD 2.86 Billion in 2025, growing at 10.66% CAGR to reach USD 7.13 Billion by 2034, led by South India.
Nov 2026|198 pages
$2900.00
CUSTOM INTELLIGENCE
Tailored for you
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
Analyst at Providence Strategic Partners at Petaling Jaya
Jared Wan
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report
Internationalization Director
Santiago Mejia Molina
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.
Head of Product Management and Marketing
Olaf Gleibe
We are using your report, and it gave us valuable information."
Regional Director, Marketing and Business Development
Lina Lim
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.
VP of Sales
DIGGLE Representative
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
Property And Casualty Reinsurance Market valued at USD 398.3 Billion in 2024, projected to reach USD 1,245.46 Billion by 2035 at a 10.92% CAGR.
Nov 2026|245 pages
$2900.00
IP valuation market valued at $14.16 Billion in 2026, reaching $30.75 Billion by 2034 at a 10.18% CAGR, driven by M&A and IP-backed finance.
Nov 2026|216 pages
$2900.00
The global residential real estate market is valued at USD 11.6 trillion in 2026 and is projected to reach USD 15.53 trillion by 2031, growing at a 6.05% CAGR.
Nov 2026|243 pages
$2900.00
Post-construction cleaning demand patterns: a $24.6B niche growing at 7.4% CAGR to 2035, driven by handover cycles, green certification and labor shifts.