1How large is the APAC specialty food processing ingredient market?
Our proprietary research sizes the market at USD 33.86 billion in 2026, up from USD 31.93 billion in 2025, and projects USD 45.46 billion by 2031 at a 6.04% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 APAC Specialty Food processing Ingredient Market
 by Product Type (Functional Food Ingredients, Specialty Starch and Texturants, Food Flavors and Enhancers, Specialty Fats and Oils, Sugar Substitutes, Acidulants, Preservatives, Emulsifiers, Colors, Enzymes, F&B Starter Cultures, Nutraceuticals), by Application (Meat, Poultry and Seafood, Dairy Products, Beverages, Bakery and Confectionery, Convenience Foods, Plant-Based Food and Beverage, Dietary Supplements, Snacks, Breakfast Cereals, Frozen Food, Baby Food, Sauces), by Asia-Pacific (China, India, Japan, South Korea, Australia, New Zealand, Thailand, Malaysia, Vietnam, Philippines, Indonesia, Singapore, Rest of APAC) Forecast 2026-2034

Research Associate


 Related Reports

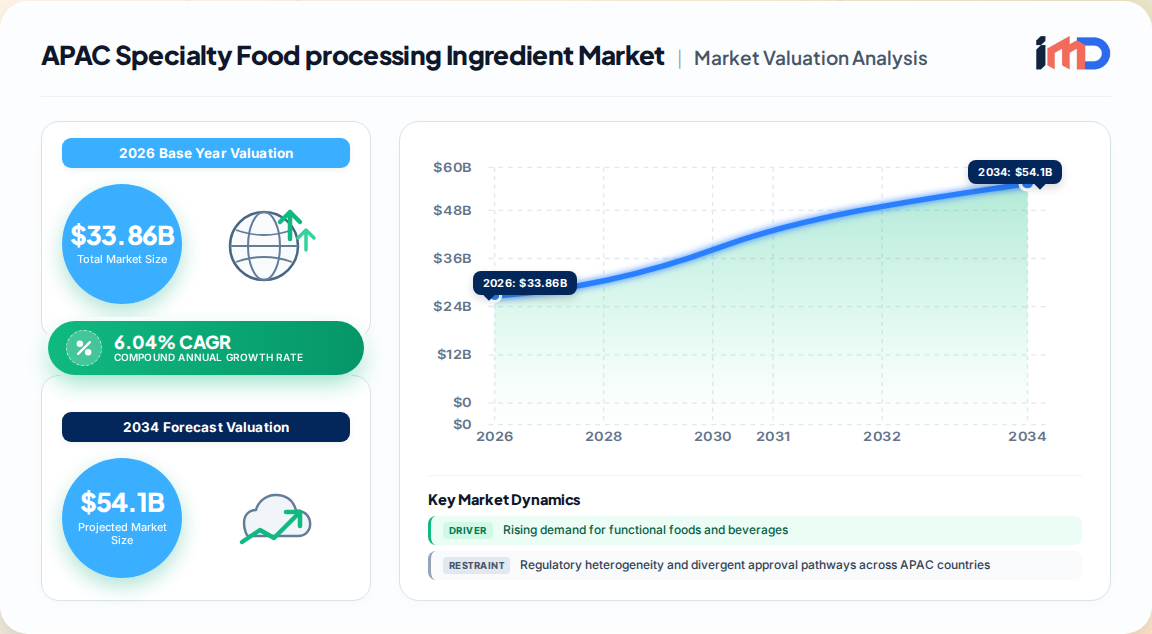
The Asia-Pacific specialty food processing ingredient market is a high-conviction growth engine within the global food value chain. Our proprietary primary research and direct interviews with formulators, ingredient technologists and procurement leads size the market at USD 33.86 billion in 2026, expanding at a 6.04% CAGR to reach USD 45.46 billion by 2031. The 2025 base-year valuation stands at USD 31.93 billion, confirming sustained double-digit absolute dollar additions each year.
Growth is anchored in structural demand-side shifts — urbanization, middle-class expansion and rising household incomes — that are reconfiguring how food is processed, packaged and consumed across the region. Manufacturers are simultaneously upgrading portfolios through precision fermentation, enzyme technology and alternative protein platforms to satisfy demand for functional, plant-based and clean-label formulations featuring specialized flavors, texturants, proteins and lipid systems.
Market concentration is moderate. Multinational ingredient houses leverage integrated value chains and global R&D depth, while regional and bio-based specialists capture defensible positions in fermentation-derived and functional segments. The regulatory landscape is converging favorably: Singapore's novel food pathway and Japan's function-claim system have materially shortened commercialization timelines for innovative ingredients.
Key structural benchmarks from our in-house modeling:
Our driver-attribution model isolates five material growth levers, each quantified for impact on the regional CAGR forecast.
| Driver | Estimated CAGR Impact | Strongest Geographies | Impact Horizon |
|---|---|---|---|
| Surge in functional foods and beverages demand | +1.5% | APAC core, Southeast Asia spillover | Long term (4+ years) |
| Health and wellness awareness | +1.2% | Urban China, India, Japan | Medium term (2–4 yrs) |
| Natural, clean-label and organic preference | +1.1% | Japan, Australia, urban China, South Korea | Long term (4+ years) |
| Convenience and ready-to-eat adoption | +1.0% | Urban China, India, Indonesia | Medium term (2–4 yrs) |
| Plant-based and vegan dietary shift | +0.9% | China, India, Australia, Singapore | Medium term (2–4 yrs) |
Japan's function-claim framework is a decisive enabler: evidence-based ingredient differentiation sustains premium pricing in women's health and cognitive nutrition despite economic headwinds. Singapore's planned extension of Nutri-Grade labeling to sauces and seasonings by 2027 is already redirecting formulation priorities toward enzyme-based sugar and sodium reduction technologies, shifting ingredient selection criteria from cost to functionality.
In functional nutrition, capital formation signals accelerating innovation pipelines. Precision fermentation ventures producing animal-free lactoferrin and beta-lactoglobulin for sports nutrition have attracted significant Series A funding, while AI-enhanced fermentation platforms converting agricultural byproducts into functional ingredients are compressing development cycles. Suppliers with robust regulatory documentation and clinical substantiation are capturing disproportionate value.
Growth is real but not frictionless. Our restraint-impact analysis identifies the following binding constraints:
By product type, food flavors and enhancers held 14.82% of regional share in 2025, reflecting their universal formulation role. Specialty fats and oils lead growth at 7.09% CAGR, driven by bakery, confectionery and plant-based formulation needs. Functional food ingredients retain the broadest adoption base, while nutraceuticals post elevated growth on preventive-healthcare demand.
By application, beverages led with 22.15% revenue share in 2025. Plant-based food and beverage applications are the fastest-growing vertical at 7.12% CAGR, requiring specialized texturants, flavor-masking systems and functional lipids to replicate animal-based sensory experiences. Transglutaminase-based texture technologies and expanded dairy-alternative ingredient portfolios are enabling hybrid solutions where microbial proteins enhance both nutrition and taste.
| Segment Dimension | Leading Segment (2025) | Fastest-Growing Segment | Growth Rate |
|---|---|---|---|
| Product — Flavors & Enhancers | 14.82% share | Specialty Fats & Oils | 7.09% CAGR |
| Application — Beverages | 22.15% share | Plant-Based F&B | 7.12% CAGR |
| Ingredient — Functional Food Ingredients | Dominant adoption | Nutraceuticals | High CAGR |
| Application — Bakery & Confectionery | Major volume share | Functional Foods & Beverages | Above market |
China's 40.05% value share is defended by scale advantages, integrated ingredient frameworks and a rapidly formalizing regulatory environment. India's 7.06% CAGR represents the region's most attractive incremental opportunity, supported by food-processing expansion, rising per-capita income and urban health awareness. Japan and South Korea anchor premium, function-claim-driven demand with high willingness to pay for clinically substantiated ingredients. Australia and New Zealand supply clean-label and dairy-based specialty inputs while importing functional systems. Southeast Asia — led by Indonesia, Vietnam, Thailand, Malaysia, the Philippines and Singapore — is the emerging volume frontier, with Singapore functioning as the region's regulatory and innovation gateway.
We characterize the competitive field as moderately fragmented, with integrated multinationals alongside bio-based challengers. Strategic activity concentrates in four arenas:
Companies distinguishing themselves combine integrated value chains, local sourcing resilience and documented safety datasets — the three criteria our interviews identify as decisive in winning regional formulation mandates.
The value chain runs from agricultural feedstock and fermentation inputs through primary processing and specialty refinement, into application-specific formulation and co-manufacturing, and finally to brand owners and foodservice operators. Value concentration is highest in clinical substantiation and application formulation — precisely where regional suppliers remain underweight.
Three white spaces merit investment attention:
Trade flows are asymmetric: China and Southeast Asia are net importers of high-value functional proteins, cultures and specialty enzymes, while Australia and New Zealand export dairy-derived and clean-label inputs. Japan imports premium functional compounds while exporting fermentation expertise and equipment. Supply-chain risk concentrates in single-origin enzyme and culture inputs, cold-chain dependence for probiotics, and freight volatility on intra-Asian routes. Our recommendation: dual-source critical enzymes, localize blending where feasible, and embed regulatory documentation into supplier qualification to shorten launch cycles.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.04% from 2020-2034 |
| Segmentation |
|
By Application
| By Geography |
|
Our proprietary research sizes the market at USD 33.86 billion in 2026, up from USD 31.93 billion in 2025, and projects USD 45.46 billion by 2031 at a 6.04% CAGR.
China commands 40.05% of regional market value in 2025, while India is the fastest-growing country market at a 7.06% CAGR from 2026 to 2031.
Specialty fats and oils expand at 7.09% CAGR through 2031, ahead of the overall market, driven by bakery, confectionery and plant-based formulation demand.
Beverages held 22.15% revenue share in 2025, while plant-based food and beverage applications grow fastest at 7.12% CAGR to 2031.
Plant-based formulators require specialized texturants, flavor-masking systems and functional lipids; this application grows at 7.12% CAGR, creating premium pricing for suppliers with sensory-replication capabilities.
Singapore's novel food pathway and Japan's function-claim system materially reduce time-to-market for innovative ingredients, rewarding suppliers with strong clinical and safety documentation.
Major participants include Cargill, Kerry Group, Tate & Lyle, ADM, International Flavors & Fragrances, Ingredion, Givaudan, Sensient Technologies, Chr. Hansen and Royal DSM.
Divergent country regulations, raw material price volatility, probiotic stability constraints and the capital intensity of clinical substantiation are the principal constraints on growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 31% |
| Head of R&D / Application Formulation Lead | 28% |
| Regulatory Affairs Manager | 22% |
| Supply Chain Director | 19% |
| Company Type | Representation (%) |
|---|---|
| Fermentation & Bio-based Ingredient Producers | 24% |
| Specialty Enzyme & Culture Suppliers | 19% |
| Flavor & Texturant Houses | 23% |
| Contract Formulators & Co-manufacturers | 17% |
| Brand Owner Procurement & R&D Teams | 17% |