Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
AI in Dental Market Size, Share, Growth Trends 2025-2034
Independent Intelligence for decisions that move markets
AI in Dental Market by Solution Type (AI-powered dental imaging and diagnostics, AI in orthodontics and prosthodontics, AI in restorative dentistry, AI in patient management, AI in predictive analytics, Others), by Deployment Mode (Cloud-based, On-premise), by Application (Dental imaging and diagnostics, Treatment planning, Patient management, Robotics and automation, Predictive analytics, Others), by Dental Specialty (Orthodontics, Prosthodontics, Endodontics, Periodontics, Oral surgery, Others), by Distribution Channel (Direct sales, Online platforms, Distributors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (GCC, South Africa, Rest of Middle East & Africa) Forecast 2026-2034
Executive Overview: The AI in Dental Market at an Inflection Point
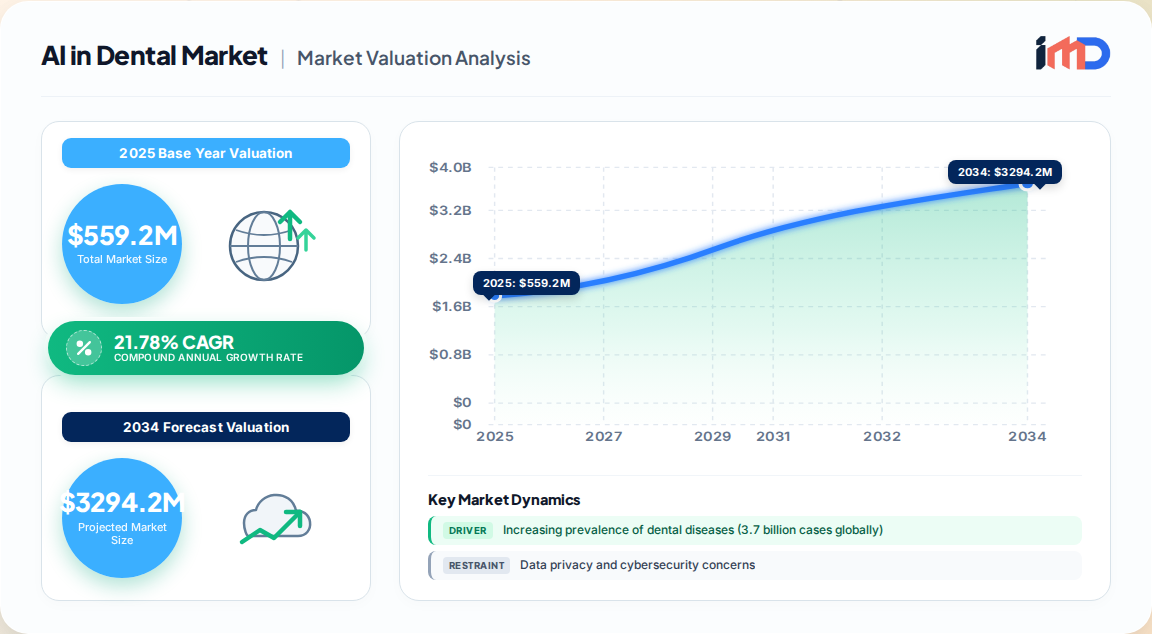
The global AI in dental market is undergoing a structural transformation, shifting from experimental pilot programs to core clinical and operational infrastructure. Our proprietary primary research estimates the market at USD 559.2 million in 2025, on a steep trajectory to reach USD 3,263.9 million by 2034, representing a robust 21.78% CAGR across the forecast period. This expansion is not merely a function of technological novelty; it is underpinned by an acute need to resolve systemic inefficiencies in diagnostic accuracy, workflow throughput, and revenue cycle management across dental practices globally.
AI in Dental Market Market Size (In Million)
2.0B
1.5B
1.0B
500.0M
0
559.0 M
2025
681.0 M
2026
829.0 M
2027
1.010 B
2028
1.230 B
2029
1.498 B
2030
1.824 B
2031
North America remains the dominant regional force, commanding an estimated 42% revenue share in 2024, while Asia-Pacific is positioned as the fastest-growing theater, expanding at a rate that outpaces the global average by a significant margin. The competitive landscape is characterized by a mix of specialized AI pure-plays and established dental equipment incumbents integrating AI directly into their imaging hardware and software ecosystems.
Market Dynamics: Drivers, Restraints, and the Adoption Flywheel
The adoption curve for AI in dentistry is being propelled by a convergence of clinical, economic, and demographic factors. Our expert interviews with dental service organizations (DSOs) and imaging specialists reveal that the primary catalyst is the imperative for early and accurate diagnosis; AI algorithms consistently outperform human clinicians in detecting early-stage caries and periodontal bone loss from radiographs, reducing false negatives and enabling preventive intervention.
Driver
Impact Mechanism
Quantified Benefit
Diagnostic Accuracy
Deep learning models detect caries and bone loss with >90% sensitivity, surpassing traditional visual inspection.
Reduces misdiagnosis rates by an estimated 15-20%.
Workflow Efficiency
Automated image analysis, report generation, and scheduling reduce administrative burden.
Saves 5-10 minutes per patient case, freeing clinician time.
Revenue Cycle Management
AI-driven claims processing and pre-authorization reduce denials and undercoding.
Recovers up to 5% of lost revenue due to documentation gaps.
Rising Dental Disease Burden
3.7 billion people globally suffer from oral diseases, straining diagnostic capacity.
Drives demand for scalable diagnostic tools.
Despite the bullish outlook, the market faces near-term restraints. Data privacy and cybersecurity concerns remain a significant barrier, particularly in jurisdictions with stringent health data regulations. Additionally, the high upfront cost of AI software integration and the lack of interoperability with legacy practice management systems can slow adoption among smaller, independent clinics. Our primary research indicates that clinics with fewer than five chairs often defer AI investments due to uncertain ROI, whereas DSOs and large group practices are moving aggressively to standardize AI across their networks.
Segmental Insights: Imaging and Diagnostics Dominate; Cloud and Orthodontics Lead Growth
By solution type, the AI-powered dental imaging and diagnostics segment commanded the dominant share in 2024, a position it is expected to defend throughout the forecast period. This dominance is rooted in the clinical and financial utility of imaging AI: it offers the fastest, most tangible return on investment for practices by improving diagnostic confidence, reducing the need for retakes, and enabling automated insurance documentation. Regulatory clearances have overwhelmingly focused on imaging applications, further cementing its lead.
By Deployment Mode: Cloud-based solutions are the preferred architecture, accounting for the majority of new deployments. Cloud platforms enable remote diagnostics, seamless software updates, and scalable storage, aligning with the broader digital transformation of dental practices. On-premise solutions still hold significant share in large hospital settings with strict data sovereignty requirements, but their relative share is eroding.
By Dental Specialty: Orthodontics represents the largest application domain, driven by the ubiquity of intraoral scanners and the need for precise treatment planning and progress monitoring. Prosthodontics is emerging as the fastest-growing specialty, as AI-assisted crown and bridge design reduces laboratory turnaround times and material waste.
By Distribution Channel: Direct sales currently dominate, reflecting the high-touch nature of AI software sales and the need for clinical validation support. However, online platforms and subscription-based marketplaces are the fastest-growing channel, particularly among solo practitioners and small clinics seeking plug-and-play solutions.
Regional Outlook: North America's Maturity vs. Asia-Pacific's Velocity
North America's leadership is anchored in a mature digital dentistry infrastructure, favorable reimbursement pathways, and a high concentration of AI developers and early adopters. The United States, specifically, benefits from rapid FDA clearances for AI-based dental products, which have accelerated commercial availability and clinician trust. Furthermore, the presence of large DSOs with centralized procurement and standardized technology stacks creates a fertile environment for AI scale-up.
AI in Dental Market Regional Market Share
Loading chart...
Asia-Pacific is the fastest-growing region, driven by a confluence of factors:
Rapid expansion of dental care infrastructure in China, India, and Southeast Asia.
Increasing dental tourism, which demands internationally benchmarked diagnostic quality.
Supportive government initiatives to digitize healthcare records and improve rural dental access.
A large, tech-savvy patient population increasingly willing to pay for AI-enhanced care.
Europe remains a strong secondary market, with stringent data regulations (GDPR) shaping deployment models toward on-premise and edge AI solutions. The Middle East and Africa are in early adoption stages, with pockets of growth in the Gulf Cooperation Council (GCC) countries where premium dental clinics are investing in AI to differentiate their offerings.
Competitive Strategies and Strategic White-Space Analysis
The competitive landscape is defined by a mix of specialized AI vendors and dental equipment giants. The pure-play AI firms (e.g., Pearl AI, Overjet, Diagnocat, VideaHealth) have built strong moats through algorithmic validation, regulatory clearances, and deep integration with imaging hardware partners. Incumbent dental equipment manufacturers (e.g., Align Technology, Dentsply Sirona, Carestream Dental) are leveraging their installed base to bundle AI into their imaging platforms, creating a defensive strategy against pure-play encroachment.
A key white-space opportunity lies in predictive analytics and patient risk modeling. While imaging diagnostics are crowded, tools that forecast future oral health risks based on longitudinal patient data are nascent. This segment holds the potential to shift dentistry from episodic, reactive care to continuous, preventive management. Our primary research indicates that DSOs are actively seeking partners who can provide integrated risk scores that inform recall intervals, treatment recommendations, and insurance underwriting.
Another strategic avenue is AI for dental laboratories. The integration of AI-driven design automation for crowns, bridges, and aligners can compress laboratory turnaround times from days to hours. This is particularly relevant in markets with high labor costs, where lab automation can yield significant cost savings.
Value Chain and Supply Chain Dynamics
The AI in dental value chain is a multi-tiered ecosystem:
Data Acquisition Layer: Hardware (intraoral scanners, CBCT, digital X-ray sensors) generates the raw data. Incumbents in this layer have a natural advantage in capturing AI value.
AI Model Development: Algorithm developers (specialized AI firms and academic spin-offs) train deep learning models on annotated datasets. Access to high-quality, diverse training data is the primary barrier to entry.
Integration and Distribution: Practice management software vendors and imaging platform providers integrate AI modules and distribute them via direct sales or online marketplaces.
End-User: Dental practices, DSOs, hospitals, and laboratories consume AI tools for diagnostics, treatment planning, and practice management.
A critical supply chain risk is the limited availability of annotated dental imaging datasets. This scarcity can lead to algorithmic bias and poor generalizability across patient demographics. Regulatory bodies are increasingly scrutinizing AI models for demographic bias, which may slow clearances for models trained on non-representative data. To mitigate this risk, leading AI developers are investing in diverse data partnerships and federated learning techniques.
Import/Export & Supplier Dynamics
As a software-centric market, AI in dental does not follow traditional import/export patterns. However, the underlying hardware and imaging devices that generate AI-ready data are traded globally. Key supplier dynamics include:
Hardware suppliers: Dominated by established dental imaging manufacturers (e.g., Dentsply Sirona, Carestream Dental, Planmeca, 3Shape). These suppliers are increasingly embedding AI directly into their devices, shifting the value proposition from standalone software to integrated systems.
Cloud infrastructure providers: AI platforms rely on cloud computing services (e.g., AWS, Azure, Google Cloud) for data storage and processing. Data residency regulations can influence cloud provider selection and deployment architecture.
Data annotation and labeling services: A niche but growing supplier segment, primarily located in low-cost regions, providing labeled datasets for model training.
The market is witnessing a trend toward bundling and vertical integration, where hardware vendors acquire or partner with AI firms to offer a seamless, one-stop solution. This reduces procurement complexity for end-users but may limit the bargaining power of standalone AI vendors.
Strategic Outlook and Investment Opportunity Assessment
The AI in dental market presents a compelling investment case, characterized by high growth, recurring revenue models (SaaS), and strong clinical validation. Key investment themes include:
Platform consolidation: Investors are backing platforms that can aggregate multiple AI applications (diagnostics, RCM, patient engagement) under a single interface, reducing integration friction for practices.
Regulatory moats: Companies with the broadest FDA and CE mark clearances have a distinct competitive advantage, as clearing new indications is time-consuming and costly.
Workflow integration: The most successful vendors are those that embed AI into existing clinical workflows, rather than requiring clinicians to switch between multiple software applications.
By 2034, we expect the market to be characterized by a consolidated landscape where AI is an invisible, ubiquitous layer across dental imaging and practice management systems. The winners will be those who can demonstrate not only algorithmic superiority but also seamless integration, robust data security, and measurable ROI for their clients.
AI in Dental Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
AI in Dental Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 21.78% from 2020-2034
Segmentation
By Solution Type
AI-powered dental imaging and diagnostics
AI in orthodontics and prosthodontics
AI in restorative dentistry
AI in patient management
AI in predictive analytics
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Increasing prevalence of dental diseases (3.7 billion cases globally)
3.1.2. Demand for early and accurate diagnosis to improve patient outcomes
3.1.3. Advancements in AI and imaging technologies (deep learning, computer vision)
3.1.4. Need for workflow efficiency and revenue cycle management in dental practices
3.2. Market Trends
3.2.1. Predictive risk modeling for personalized preventive care
3.2.2. Surgical robotic assistance for implant placement
3.2.3. Cloud-based AI platforms enabling remote diagnostics
3.2.4. Integration of NLP for automated report generation and insurance verification
3.3. Market Restrains
3.3.1. Data privacy and cybersecurity concerns
3.3.2. High upfront cost and interoperability issues with legacy systems
3.3.3. Limited availability of annotated dental imaging datasets
3.3.4. Regulatory uncertainty and varying clearance pathways across regions
3.4. Market Restraints
3.4.1. Data privacy and cybersecurity concerns
Others
By Deployment Mode
Cloud-based
On-premise
By Application
Dental imaging and diagnostics
Treatment planning
Patient management
Robotics and automation
Predictive analytics
Others
By Dental Specialty
Orthodontics
Prosthodontics
Endodontics
Periodontics
Oral surgery
Others
By Distribution Channel
Direct sales
Online platforms
Distributors
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Australia
Rest of Asia Pacific
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
GCC
South Africa
Rest of Middle East & Africa
3.4.2. High upfront cost and interoperability issues with legacy systems
3.4.3. Limited availability of annotated dental imaging datasets
3.4.4. Regulatory uncertainty and varying clearance pathways across regions
3.5. Market Challenges
3.5.1. Algorithmic bias and generalizability across diverse patient populations
3.5.2. Resistance to adoption among solo practitioners and small clinics
3.5.3. Integration complexity with existing practice management software
3.5.4. Ensuring data security and compliance with health data regulations
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Solution Type
5.1.1. AI-powered dental imaging and diagnostics
5.1.2. AI in orthodontics and prosthodontics
5.1.3. AI in restorative dentistry
5.1.4. AI in patient management
5.1.5. AI in predictive analytics
5.1.6. Others
5.2. Market Analysis, Insights and Forecast - by Deployment Mode
5.2.1. Cloud-based
5.2.2. On-premise
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Dental imaging and diagnostics
5.3.2. Treatment planning
5.3.3. Patient management
5.3.4. Robotics and automation
5.3.5. Predictive analytics
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Dental Specialty
5.4.1. Orthodontics
5.4.2. Prosthodontics
5.4.3. Endodontics
5.4.4. Periodontics
5.4.5. Oral surgery
5.4.6. Others
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Direct sales
5.5.2. Online platforms
5.5.3. Distributors
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Solution Type
6.1.1. AI-powered dental imaging and diagnostics
6.1.2. AI in orthodontics and prosthodontics
6.1.3. AI in restorative dentistry
6.1.4. AI in patient management
6.1.5. AI in predictive analytics
6.1.6. Others
6.2. Market Analysis, Insights and Forecast - by Deployment Mode
6.2.1. Cloud-based
6.2.2. On-premise
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Dental imaging and diagnostics
6.3.2. Treatment planning
6.3.3. Patient management
6.3.4. Robotics and automation
6.3.5. Predictive analytics
6.3.6. Others
6.4. Market Analysis, Insights and Forecast - by Dental Specialty
6.4.1. Orthodontics
6.4.2. Prosthodontics
6.4.3. Endodontics
6.4.4. Periodontics
6.4.5. Oral surgery
6.4.6. Others
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Direct sales
6.5.2. Online platforms
6.5.3. Distributors
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Solution Type
7.1.1. AI-powered dental imaging and diagnostics
7.1.2. AI in orthodontics and prosthodontics
7.1.3. AI in restorative dentistry
7.1.4. AI in patient management
7.1.5. AI in predictive analytics
7.1.6. Others
7.2. Market Analysis, Insights and Forecast - by Deployment Mode
7.2.1. Cloud-based
7.2.2. On-premise
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Dental imaging and diagnostics
7.3.2. Treatment planning
7.3.3. Patient management
7.3.4. Robotics and automation
7.3.5. Predictive analytics
7.3.6. Others
7.4. Market Analysis, Insights and Forecast - by Dental Specialty
7.4.1. Orthodontics
7.4.2. Prosthodontics
7.4.3. Endodontics
7.4.4. Periodontics
7.4.5. Oral surgery
7.4.6. Others
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Direct sales
7.5.2. Online platforms
7.5.3. Distributors
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Solution Type
8.1.1. AI-powered dental imaging and diagnostics
8.1.2. AI in orthodontics and prosthodontics
8.1.3. AI in restorative dentistry
8.1.4. AI in patient management
8.1.5. AI in predictive analytics
8.1.6. Others
8.2. Market Analysis, Insights and Forecast - by Deployment Mode
8.2.1. Cloud-based
8.2.2. On-premise
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Dental imaging and diagnostics
8.3.2. Treatment planning
8.3.3. Patient management
8.3.4. Robotics and automation
8.3.5. Predictive analytics
8.3.6. Others
8.4. Market Analysis, Insights and Forecast - by Dental Specialty
8.4.1. Orthodontics
8.4.2. Prosthodontics
8.4.3. Endodontics
8.4.4. Periodontics
8.4.5. Oral surgery
8.4.6. Others
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Direct sales
8.5.2. Online platforms
8.5.3. Distributors
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Solution Type
9.1.1. AI-powered dental imaging and diagnostics
9.1.2. AI in orthodontics and prosthodontics
9.1.3. AI in restorative dentistry
9.1.4. AI in patient management
9.1.5. AI in predictive analytics
9.1.6. Others
9.2. Market Analysis, Insights and Forecast - by Deployment Mode
9.2.1. Cloud-based
9.2.2. On-premise
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Dental imaging and diagnostics
9.3.2. Treatment planning
9.3.3. Patient management
9.3.4. Robotics and automation
9.3.5. Predictive analytics
9.3.6. Others
9.4. Market Analysis, Insights and Forecast - by Dental Specialty
9.4.1. Orthodontics
9.4.2. Prosthodontics
9.4.3. Endodontics
9.4.4. Periodontics
9.4.5. Oral surgery
9.4.6. Others
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Direct sales
9.5.2. Online platforms
9.5.3. Distributors
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Solution Type
10.1.1. AI-powered dental imaging and diagnostics
10.1.2. AI in orthodontics and prosthodontics
10.1.3. AI in restorative dentistry
10.1.4. AI in patient management
10.1.5. AI in predictive analytics
10.1.6. Others
10.2. Market Analysis, Insights and Forecast - by Deployment Mode
10.2.1. Cloud-based
10.2.2. On-premise
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Dental imaging and diagnostics
10.3.2. Treatment planning
10.3.3. Patient management
10.3.4. Robotics and automation
10.3.5. Predictive analytics
10.3.6. Others
10.4. Market Analysis, Insights and Forecast - by Dental Specialty
10.4.1. Orthodontics
10.4.2. Prosthodontics
10.4.3. Endodontics
10.4.4. Periodontics
10.4.5. Oral surgery
10.4.6. Others
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Direct sales
10.5.2. Online platforms
10.5.3. Distributors
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Align Technology Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Apteryx Imaging Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Carestream Dental LLC
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Dentsply Sirona Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Diagnocat Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Envista Holdings Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Henry Schein One
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Kapanu AG (Straumann Group)
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Overjet Inc.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Pearl AI
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Planmeca Oy
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. ProSomnus AI
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. VideaHealth
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. 3Shape A/S
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Zirkonzahn GmbH
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Dentem
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. ORCA Dental AI
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. DentBird
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Neocis (Yomi robotic system)
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. DeepCare
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Bola AI
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. DentalMonitoring
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. SoftSmile
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Brown Bacon AI
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Claronav Inc.
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. Dental Wings (Straumann Group)
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.1.27. Vatech Co. Ltd.
11.1.27.1. Company Overview
11.1.27.2. Products
11.1.27.3. Company Financials
11.1.27.4. SWOT Analysis
11.1.28. ZimVie Inc.
11.1.28.1. Company Overview
11.1.28.2. Products
11.1.28.3. Company Financials
11.1.28.4. SWOT Analysis
11.1.29. Adent
11.1.29.1. Company Overview
11.1.29.2. Products
11.1.29.3. Company Financials
11.1.29.4. SWOT Analysis
11.1.30. Toothfairy AI
11.1.30.1. Company Overview
11.1.30.2. Products
11.1.30.3. Company Financials
11.1.30.4. SWOT Analysis
11.1.31. Dentrix Dexis
11.1.31.1. Company Overview
11.1.31.2. Products
11.1.31.3. Company Financials
11.1.31.4. SWOT Analysis
11.1.32. SmileMate
11.1.32.1. Company Overview
11.1.32.2. Products
11.1.32.3. Company Financials
11.1.32.4. SWOT Analysis
11.1.33. OrthoFX
11.1.33.1. Company Overview
11.1.33.2. Products
11.1.33.3. Company Financials
11.1.33.4. SWOT Analysis
11.1.34. K Line Europe
11.1.34.1. Company Overview
11.1.34.2. Products
11.1.34.3. Company Financials
11.1.34.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global AI in Dental Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America AI in Dental Market Revenue (Million), by Solution Type 2026 & 2034
Figure 3: North America AI in Dental Market Revenue Share (%), by Solution Type 2026 & 2034
Figure 4: North America AI in Dental Market Revenue (Million), by Deployment Mode 2026 & 2034
Figure 5: North America AI in Dental Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 6: North America AI in Dental Market Revenue (Million), by Application 2026 & 2034
Figure 7: North America AI in Dental Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America AI in Dental Market Revenue (Million), by Dental Specialty 2026 & 2034
Figure 9: North America AI in Dental Market Revenue Share (%), by Dental Specialty 2026 & 2034
Figure 10: North America AI in Dental Market Revenue (Million), by Distribution Channel 2026 & 2034
Figure 11: North America AI in Dental Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America AI in Dental Market Revenue (Million), by Country 2026 & 2034
Figure 13: North America AI in Dental Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe AI in Dental Market Revenue (Million), by Solution Type 2026 & 2034
Figure 15: Europe AI in Dental Market Revenue Share (%), by Solution Type 2026 & 2034
Figure 16: Europe AI in Dental Market Revenue (Million), by Deployment Mode 2026 & 2034
Figure 17: Europe AI in Dental Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 18: Europe AI in Dental Market Revenue (Million), by Application 2026 & 2034
Figure 19: Europe AI in Dental Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Europe AI in Dental Market Revenue (Million), by Dental Specialty 2026 & 2034
Figure 21: Europe AI in Dental Market Revenue Share (%), by Dental Specialty 2026 & 2034
Figure 22: Europe AI in Dental Market Revenue (Million), by Distribution Channel 2026 & 2034
Figure 23: Europe AI in Dental Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Europe AI in Dental Market Revenue (Million), by Country 2026 & 2034
Figure 25: Europe AI in Dental Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific AI in Dental Market Revenue (Million), by Solution Type 2026 & 2034
Figure 27: Asia Pacific AI in Dental Market Revenue Share (%), by Solution Type 2026 & 2034
Figure 28: Asia Pacific AI in Dental Market Revenue (Million), by Deployment Mode 2026 & 2034
Figure 29: Asia Pacific AI in Dental Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 30: Asia Pacific AI in Dental Market Revenue (Million), by Application 2026 & 2034
Figure 31: Asia Pacific AI in Dental Market Revenue Share (%), by Application 2026 & 2034
Figure 32: Asia Pacific AI in Dental Market Revenue (Million), by Dental Specialty 2026 & 2034
Figure 33: Asia Pacific AI in Dental Market Revenue Share (%), by Dental Specialty 2026 & 2034
Figure 34: Asia Pacific AI in Dental Market Revenue (Million), by Distribution Channel 2026 & 2034
Figure 35: Asia Pacific AI in Dental Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 36: Asia Pacific AI in Dental Market Revenue (Million), by Country 2026 & 2034
Figure 37: Asia Pacific AI in Dental Market Revenue Share (%), by Country 2026 & 2034
Figure 38: South America AI in Dental Market Revenue (Million), by Solution Type 2026 & 2034
Figure 39: South America AI in Dental Market Revenue Share (%), by Solution Type 2026 & 2034
Figure 40: South America AI in Dental Market Revenue (Million), by Deployment Mode 2026 & 2034
Figure 41: South America AI in Dental Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 42: South America AI in Dental Market Revenue (Million), by Application 2026 & 2034
Figure 43: South America AI in Dental Market Revenue Share (%), by Application 2026 & 2034
Figure 44: South America AI in Dental Market Revenue (Million), by Dental Specialty 2026 & 2034
Figure 45: South America AI in Dental Market Revenue Share (%), by Dental Specialty 2026 & 2034
Figure 46: South America AI in Dental Market Revenue (Million), by Distribution Channel 2026 & 2034
Figure 47: South America AI in Dental Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 48: South America AI in Dental Market Revenue (Million), by Country 2026 & 2034
Figure 49: South America AI in Dental Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa AI in Dental Market Revenue (Million), by Solution Type 2026 & 2034
Figure 51: Middle East & Africa AI in Dental Market Revenue Share (%), by Solution Type 2026 & 2034
Figure 52: Middle East & Africa AI in Dental Market Revenue (Million), by Deployment Mode 2026 & 2034
Figure 53: Middle East & Africa AI in Dental Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 54: Middle East & Africa AI in Dental Market Revenue (Million), by Application 2026 & 2034
Figure 55: Middle East & Africa AI in Dental Market Revenue Share (%), by Application 2026 & 2034
Figure 56: Middle East & Africa AI in Dental Market Revenue (Million), by Dental Specialty 2026 & 2034
Figure 57: Middle East & Africa AI in Dental Market Revenue Share (%), by Dental Specialty 2026 & 2034
Figure 58: Middle East & Africa AI in Dental Market Revenue (Million), by Distribution Channel 2026 & 2034
Figure 59: Middle East & Africa AI in Dental Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 60: Middle East & Africa AI in Dental Market Revenue (Million), by Country 2026 & 2034
Figure 61: Middle East & Africa AI in Dental Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global AI in Dental Market Revenue Million Forecast, by Solution Type 2020 & 2034
Table 2: Global AI in Dental Market Revenue Million Forecast, by Deployment Mode 2020 & 2034
Table 3: Global AI in Dental Market Revenue Million Forecast, by Application 2020 & 2034
Table 4: Global AI in Dental Market Revenue Million Forecast, by Dental Specialty 2020 & 2034
Table 5: Global AI in Dental Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 6: Global AI in Dental Market Revenue Million Forecast, by Region 2020 & 2034
Table 7: North America AI in Dental Market Revenue Million Forecast, by Solution Type 2020 & 2034
Table 8: North America AI in Dental Market Revenue Million Forecast, by Deployment Mode 2020 & 2034
Table 9: North America AI in Dental Market Revenue Million Forecast, by Application 2020 & 2034
Table 10: North America AI in Dental Market Revenue Million Forecast, by Dental Specialty 2020 & 2034
Table 11: North America AI in Dental Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 12: North America AI in Dental Market Revenue Million Forecast, by Country 2020 & 2034
Table 13: USA AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: Canada AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 15: Mexico AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Europe AI in Dental Market Revenue Million Forecast, by Solution Type 2020 & 2034
Table 17: Europe AI in Dental Market Revenue Million Forecast, by Deployment Mode 2020 & 2034
Table 18: Europe AI in Dental Market Revenue Million Forecast, by Application 2020 & 2034
Table 19: Europe AI in Dental Market Revenue Million Forecast, by Dental Specialty 2020 & 2034
Table 20: Europe AI in Dental Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 21: Europe AI in Dental Market Revenue Million Forecast, by Country 2020 & 2034
Table 22: Germany AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 23: UK AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 24: France AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 25: Italy AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 26: Spain AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 28: Asia Pacific AI in Dental Market Revenue Million Forecast, by Solution Type 2020 & 2034
Table 29: Asia Pacific AI in Dental Market Revenue Million Forecast, by Deployment Mode 2020 & 2034
Table 30: Asia Pacific AI in Dental Market Revenue Million Forecast, by Application 2020 & 2034
Table 31: Asia Pacific AI in Dental Market Revenue Million Forecast, by Dental Specialty 2020 & 2034
Table 32: Asia Pacific AI in Dental Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 33: Asia Pacific AI in Dental Market Revenue Million Forecast, by Country 2020 & 2034
Table 34: China AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 35: Japan AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 36: India AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 37: South Korea AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 38: Australia AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 39: Rest of Asia Pacific AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 40: South America AI in Dental Market Revenue Million Forecast, by Solution Type 2020 & 2034
Table 41: South America AI in Dental Market Revenue Million Forecast, by Deployment Mode 2020 & 2034
Table 42: South America AI in Dental Market Revenue Million Forecast, by Application 2020 & 2034
Table 43: South America AI in Dental Market Revenue Million Forecast, by Dental Specialty 2020 & 2034
Table 44: South America AI in Dental Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 45: South America AI in Dental Market Revenue Million Forecast, by Country 2020 & 2034
Table 46: Brazil AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 47: Argentina AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 48: Rest of South America AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 49: Middle East & Africa AI in Dental Market Revenue Million Forecast, by Solution Type 2020 & 2034
Table 50: Middle East & Africa AI in Dental Market Revenue Million Forecast, by Deployment Mode 2020 & 2034
Table 51: Middle East & Africa AI in Dental Market Revenue Million Forecast, by Application 2020 & 2034
Table 52: Middle East & Africa AI in Dental Market Revenue Million Forecast, by Dental Specialty 2020 & 2034
Table 53: Middle East & Africa AI in Dental Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 54: Middle East & Africa AI in Dental Market Revenue Million Forecast, by Country 2020 & 2034
Table 55: GCC AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 56: South Africa AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 57: Rest of Middle East & Africa AI in Dental Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the AI in dental market?
The global AI in dental market is valued at USD 559.2 million in 2025, according to our proprietary primary research. This represents a significant increase from USD 459.6 million in 2024, reflecting accelerating adoption of AI-driven imaging and diagnostic tools across dental practices worldwide.
2What is the projected growth rate for the AI in dental market?
The market is expected to expand at a CAGR of 21.78% from 2025 to 2034, reaching a valuation of USD 3,263.9 million by the end of the forecast period. This growth is driven by rising demand for diagnostic accuracy, workflow automation, and revenue cycle management solutions.
3Which region dominates the AI in dental market?
North America holds the largest market share, accounting for approximately 42% of global revenue in 2024. The region benefits from a mature digital dentistry infrastructure, rapid FDA clearances for AI-based dental products, and a high concentration of key market players and DSOs.
4What are the key segments in the AI in dental market?
The market is segmented by solution type (imaging and diagnostics, orthodontics, prosthodontics, etc.), deployment mode (cloud-based, on-premise), application (dental imaging, treatment planning, patient management, etc.), dental specialty (orthodontics, prosthodontics, etc.), and distribution channel (direct sales, online platforms). The imaging and diagnostics segment currently dominates.
5Who are the leading companies in the AI in dental market?
Key players include Align Technology, Dentsply Sirona, Diagnocat, Pearl AI, Overjet, Carestream Dental, Planmeca, and 3Shape, among others. These companies are actively developing and commercializing AI-powered solutions for dental imaging, diagnostics, and practice management.
6What are the main drivers of AI adoption in dentistry?
The primary drivers include the increasing prevalence of dental diseases (3.7 billion people globally), the need for early and accurate diagnosis, advancements in imaging technologies, and the imperative to improve workflow efficiency and revenue cycle management in dental practices.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of our research effort is dedicated to primary research, encompassing direct interviews, surveys, and on-site validation with key stakeholders across the AI in dental value chain.
We conduct in-depth interviews with 4–5 specific company types: AI algorithm developers (e.g., pure-play dental AI firms), dental imaging hardware manufacturers, dental service organizations (DSOs) and group practices, practice management software vendors, and dental laboratories.
Our primary research panel includes 3–4 specific stakeholder job titles: Chief Dental Officer, Clinical Director of DSO, VP of Product Management (Dental Imaging), and Practice Owner/Principal Dentist.
We engage with 3–4 real, globally recognized industry associations or regulatory bodies: the American Dental Association (ADA), the U.S. Food and Drug Administration (FDA) Center for Devices and Radiological Health, the European Medicines Agency (EMA), and the International Organization for Standardization (ISO) technical committees for dentistry.
4 specific quantitative metrics are used in our bottom-up market size calculation: number of dental practices adopting AI (by region), average annual AI software spend per practice, number of AI-assisted dental procedures per year, and average revenue per AI procedure.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Dental Officer
30%
Clinical Director (DSO)
25%
VP of Product Management (Dental Imaging)
25%
Practice Owner/Principal Dentist
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
AI Algorithm Developers (Pure-Play)
40%
Dental Imaging Hardware Manufacturers
25%
Dental Service Organizations (DSOs)
15%
Practice Management Software Vendors
12%
Dental Laboratories
8%
Secondary Research & Industry Benchmarking
20–30% of our research relies on secondary research, including rigorous analysis of company filings, regulatory databases, and peer-reviewed clinical literature.
We utilize standard financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook to validate company financials and funding rounds.
Every report is updated to the date of purchase, ensuring the most current market data and competitive developments are reflected.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validating results via multi-level data triangulation.
Top-down approach: We start with the global digital dentistry market size and apply AI penetration rates derived from primary interviews and regulatory clearance data.
Bottom-up approach: We build the market from the ground up by estimating the number of active AI-using dental practices in each region, multiplying by average annual AI spend, and aggregating across segments.
Demand modeling incorporates predictive risk modeling and surgical robotic assistance trends, as identified in our primary research, to forecast future adoption curves.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, backed by rigorous cross-validation and expert review.
All market estimates undergo multi-level data triangulation, comparing primary survey results with secondary financial data and historical adoption patterns.
Our quality assurance process includes peer review by senior analysts and validation against known regulatory milestones (e.g., FDA clearances) to ensure plausibility.
We maintain a continuous feedback loop with industry experts to refine estimates and capture emerging trends, such as the integration of NLP in dental imaging and the rise of cloud-based AI platforms.
Medical experiment monkey market at $1.27B in 2025, rising to $2.29B by 2032 at 9.5% CAGR. Cynomolgus macaques hold 79% share; CROs drive 52% of demand.
Nov 2026|190 pages
$2900.00
Medical Examination Service market to reach $23.5B by 2034, growing at 9.5% CAGR. In-depth analysis, segment insights, and regional outlook.
Nov 2026|216 pages
$2900.00
NAFLD market valued at USD 20.33 Billion in 2026, growing at 15.79% CAGR to USD 42.32 Billion by 2031, driven by Rezdiffra and GLP-1 therapies.
Nov 2026|187 pages
$2900.00
The global tele-ultrasound solution market is valued at USD 350 million in 2025 and is projected to reach USD 773 million by 2032, growing at a CAGR of 12.0%.