1What is the current size of the acrylic sheets market?
The global acrylic sheets market was valued at USD 5.31 billion in 2025 and is projected to reach USD 10.17 billion by 2035, growing at a CAGR of 6.7% during the forecast period.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Acrylic Sheets Market
 by Type (Cast Acrylic Sheets (Cell Cast, Continuous Cast), Extruded Acrylic Sheets), by Application (Construction & Architecture, Automotive & Transportation, Signage & Displays, Healthcare & Medical, Furniture & Interiors, Electronics & Electrical, Sanitary Ware, Aerospace & Defense), by Product Type (UV Resistant, UV Transmitting), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Russia), by Asia-Pacific (China, India, Japan, South Korea, Indonesia, Malaysia, Thailand, Vietnam), by Middle East & Africa (GCC, South Africa), by South America (Brazil, Argentina) Forecast 2026-2034

Senior Analyst


 Related Reports

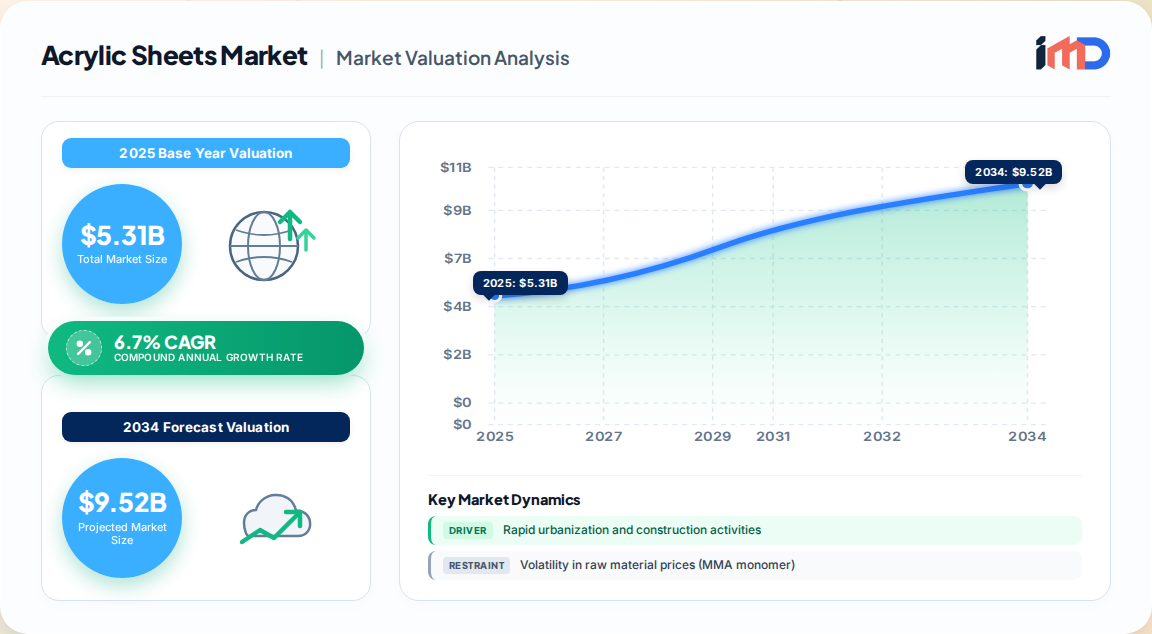
The global acrylic sheets market is experiencing robust expansion, driven by accelerating demand across construction, automotive, signage, and healthcare sectors. Our proprietary primary research estimates the market at USD 5.31 billion in 2025, projected to reach USD 10.17 billion by 2035, registering a CAGR of 6.7% over the forecast period. Acrylic sheets, composed of polymethyl methacrylate (PMMA), offer a compelling combination of optical clarity, lightweight durability, UV resistance, and design versatility, positioning them as a superior alternative to glass in numerous applications.
This comprehensive analysis draws on exclusive interviews with industry stakeholders across the value chain, validated against official trade statistics and manufacturing data. The market's trajectory is shaped by rapid urbanization in emerging economies, technological advancements in sheet manufacturing, and a pronounced shift toward sustainable, recyclable materials. The competitive landscape is moderately consolidated, with leading chemical and materials companies driving innovation through product differentiation and strategic capacity expansions.
The market is segmented into cast acrylic sheets and extruded acrylic sheets. Cast acrylic sheets dominate with a 66.4% share in 2022, owing to superior optical clarity, surface finish, and durability. The casting process yields sheets with excellent machinability and resistance to solvents, making them ideal for high-end signage, architectural glazing, and automotive components. However, extruded acrylic sheets are gaining traction due to cost advantages and high-volume production capabilities, particularly in applications where optical perfection is less critical.
Within cast acrylic sheets, cell-cast sheets are the preferred choice for premium applications, while continuous-cast sheets are witnessing faster growth due to automated production efficiencies and consistent thickness control. Continuous-cast sheets are increasingly adopted in large-scale architectural and signage projects.
Asia-Pacific is the largest and fastest-growing regional market, accounting for over 50% of global revenue. Rapid urbanization, infrastructure development, and expanding automotive production in China, India, Japan, and Southeast Asia are the primary growth drivers. China alone consumes more than 30% of global acrylic sheets. The region's construction sector is projected to grow at 6.5% annually, creating substantial demand for acrylic glazing and architectural elements. Government initiatives such as India's 'Smart Cities Mission' and China's 'Belt and Road Initiative' are expected to further stimulate market growth.
North America is the largest market by revenue in certain segments, driven by robust demand for premium architectural materials, renovation activities, and advanced signage solutions. The United States and Canada are key contributors, with a strong presence of leading manufacturers. The region's focus on energy-efficient buildings and sustainable materials is expected to drive innovation and adoption of high-performance acrylic sheets.
Europe represents a mature market with a strong emphasis on design, sustainability, and regulatory compliance. Germany, France, and the UK are the leading markets. The region's construction sector is recovering, and demand for acrylic sheets in energy-efficient glazing and interior design is growing. Stringent environmental regulations are pushing manufacturers toward eco-friendly production methods.
The Middle East & Africa region is the fastest-growing regional market, albeit from a smaller base. High purchasing power, luxury infrastructure projects, and expanding healthcare sectors in the GCC countries are driving demand. Africa's construction sector is also picking up, with acrylic sheets increasingly used in signage and interior applications.
South America is a relatively small but growing market, with Brazil and Argentina leading demand. Construction and automotive sectors are the primary end-users, and market growth is tied to economic recovery and infrastructure investments.
The global acrylic sheets market is moderately consolidated, with key players competing on product quality, innovation, and geographic reach. Leading companies include Mitsubishi Chemical Corporation, Rohm and Haas, Evonik Industries, Plaskolite, Altuglas International, 3A Composites, Aristech Acrylics, SABIC, Kuraray Co., Ltd., Acrylic Sheet Company, and Margacipta Wirasentosa, among others.
Strategic initiatives focus on capacity expansions, product differentiation, and sustainability:
Recent developments include the introduction of nanostructured acrylic glass with enhanced scratch resistance, and the commercialization of chemically recycled acrylic sheets, aligning with circular economy principles.
The acrylic sheets value chain encompasses raw material suppliers (MMA producers), sheet manufacturers, distributors, and end-users. Key raw materials include methyl methacrylate (MMA), initiators, and additives. MMA production is concentrated among large chemical companies, and its price is closely tied to crude oil and natural gas prices.
Manufacturing processes include cell casting, continuous casting, and extrusion. Cell casting, though energy-intensive, yields superior optical quality, while continuous casting and extrusion offer cost advantages for mass production. The supply chain is moderately concentrated, with the top five manufacturers accounting for approximately 45% of global capacity.
Trade flows are significant, with Asia-Pacific being a net exporter of acrylic sheets, while North America and Europe are net importers. China is the largest exporter, followed by South Korea and Taiwan. The United States and Germany are major importers, reflecting strong domestic demand.
Supply chain risks include geopolitical tensions affecting trade routes, environmental regulations impacting production costs, and the availability of skilled labor. Manufacturers are increasingly adopting local-for-local strategies to mitigate these risks.
Global trade in acrylic sheets is substantial, with Asia-Pacific as the dominant exporting region. According to official trade statistics, China exported over 1.2 million metric tons of acrylic sheets in 2023, primarily to North America and Europe. South Korea, Taiwan, and Japan are also significant exporters. The United States and Germany are the largest importers, driven by strong demand from construction and automotive sectors.
Key suppliers of MMA include Mitsubishi Chemical, Evonik, Dow, and BASF, which also participate in sheet manufacturing. The supply chain is integrated to varying degrees, with some companies controlling both MMA production and sheet fabrication. This vertical integration provides cost advantages and supply security.
Trade policies, such as anti-dumping duties and tariffs, can influence trade flows. For instance, the US imposed anti-dumping duties on certain acrylic sheets from China in 2022, leading to a shift in sourcing to other Asian countries. Manufacturers are advised to monitor trade regulations and diversify their supplier base to mitigate risks.
The acrylic sheets market is poised for sustained growth, with a CAGR of 6.7% from 2025 to 2035. The market will be propelled by urbanization, infrastructure development, and the increasing substitution of glass with lightweight, durable acrylic materials. Technological innovations, such as UV-resistant and scratch-resistant coatings, will expand application possibilities. However, volatility in raw material prices and competition from substitutes remain challenges.
Stakeholders should focus on strategic investments in high-growth regions, sustainable product development, and supply chain resilience to capitalize on emerging opportunities. The shift toward a circular economy and the adoption of recycled acrylic sheets present a significant avenue for differentiation and long-term value creation.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.7% from 2020-2034 |
| Segmentation |
|
By Product Type
| By Geography |
|
The global acrylic sheets market was valued at USD 5.31 billion in 2025 and is projected to reach USD 10.17 billion by 2035, growing at a CAGR of 6.7% during the forecast period.
Asia-Pacific is the largest and fastest-growing market, accounting for over 50% of global revenue, driven by rapid urbanization and infrastructure development in China and India. North America and Europe are also significant markets, with a focus on premium and sustainable products.
Key drivers include rising construction activities, increasing demand for lightweight materials in automotive, growing signage and retail display industries, and the shift toward sustainable and recyclable materials. Technological advancements in manufacturing and customization are also fueling growth.
Construction and architecture is the largest application segment, holding a 35.4% share in 2022, followed by signage and displays. The automotive segment is the fastest-growing, with a CAGR of 7% through 2035.
Leading companies include Mitsubishi Chemical Corporation, Rohm and Haas, Evonik Industries, Plaskolite, Altuglas International, 3A Composites, Aristech Acrylics, SABIC, Kuraray Co., Ltd., and Acrylic Sheet Company, among others.
Challenges include volatility in raw material prices (especially MMA monomer), competition from substitutes like glass and polycarbonate, environmental regulations on solvent emissions, and supply chain disruptions due to geopolitical tensions.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Directors | 30% |
| Plant Operations Managers | 25% |
| R&D and Product Development Heads | 25% |
| Sustainability and Regulatory Affairs Officers | 20% |
| Company Type | Representation (%) |
|---|---|
| Acrylic Sheet Manufacturers | 35% |
| Raw Material Suppliers (MMA Producers) | 20% |
| Distributors & Wholesalers | 25% |
| End-Users (Construction, Automotive, Signage, etc.) | 20% |